Changes in Employer Coverage for GLP-1 Weight Loss Drugs
As open enrollment season approaches, many employees might find that coverage for GLP-1 weight loss medications is noticeably absent from their benefits options.
Increasingly, employers are either cutting coverage entirely or offering less substantial benefits when it comes to these drugs. In some instances, they’ve opted to provide employees with something else—like access to weight management programs managed by third parties.
Covering GLP-1 drugs can be a significant financial burden for businesses, often costing between $500 to $600 per user each month. Despite the expense, some companies believe that the investment is worthwhile due to the health benefits for their employees. “We’ve spent about $250 million or more on GLPs, an increase from zero four or five years ago,” said Bank of America CEO Brian Moynihan in a recent CNBC interview. “We notice a very positive effect on our workforce. We’re definitely negotiating hard on pricing, but the long-term health benefits make it a smart investment.”
However, the rising costs of healthcare are pushing more employers, including larger firms, to reconsider their coverage of GLP-1 drugs for weight loss. A recent WTW annual health benefits survey revealed that 53% of employers with over 100 employees offer GLP-1 coverage, down from 57% last year. This marks the first decrease in three years. Additionally, 16% of employers who currently provide coverage are contemplating removing it, up from 9% the previous year.
A related survey from Marsh, involving more than 1,800 U.S. employers, indicates that health insurance costs per employee are expected to rise by an average of 8.2% in 2027, marking the highest increase since 2003. GLP-1 usage is projected to account for one percentage point of this cost increase, contributing to the growing hesitation among employers to maintain coverage.
“Employers are trying to find a balance between compassion for their employees and managing costs,” noted Caroline Susie from Marsh’s health management practice.
If GLP-1 coverage is indeed dropped, some workers with employer-sponsored health plans might be directed towards alternatives, although these may not provide the same level of support as full health insurance. Here are some options being explored.
Direct-to-Consumer Programs
Some companies are encouraging employees to purchase GLP-1 medications through direct-to-consumer platforms, such as Novo Nordisk’s NovoCare or Eli Lilly’s LillyDirect. The WTW survey revealed that 8% of employers are currently pursuing this route, with 28% considering it.
According to Seth Friedman from Gallagher, around 20% to 30% of their clients are opting not to cover GLP-1s in 2027 and instead are guiding employees to direct purchase methods. This shift could result in significant savings for employers. A Gallup poll showed that the number of American adults using GLP-1 medications for weight loss has risen to 11% in 2026, significantly up from just 3% in 2024.
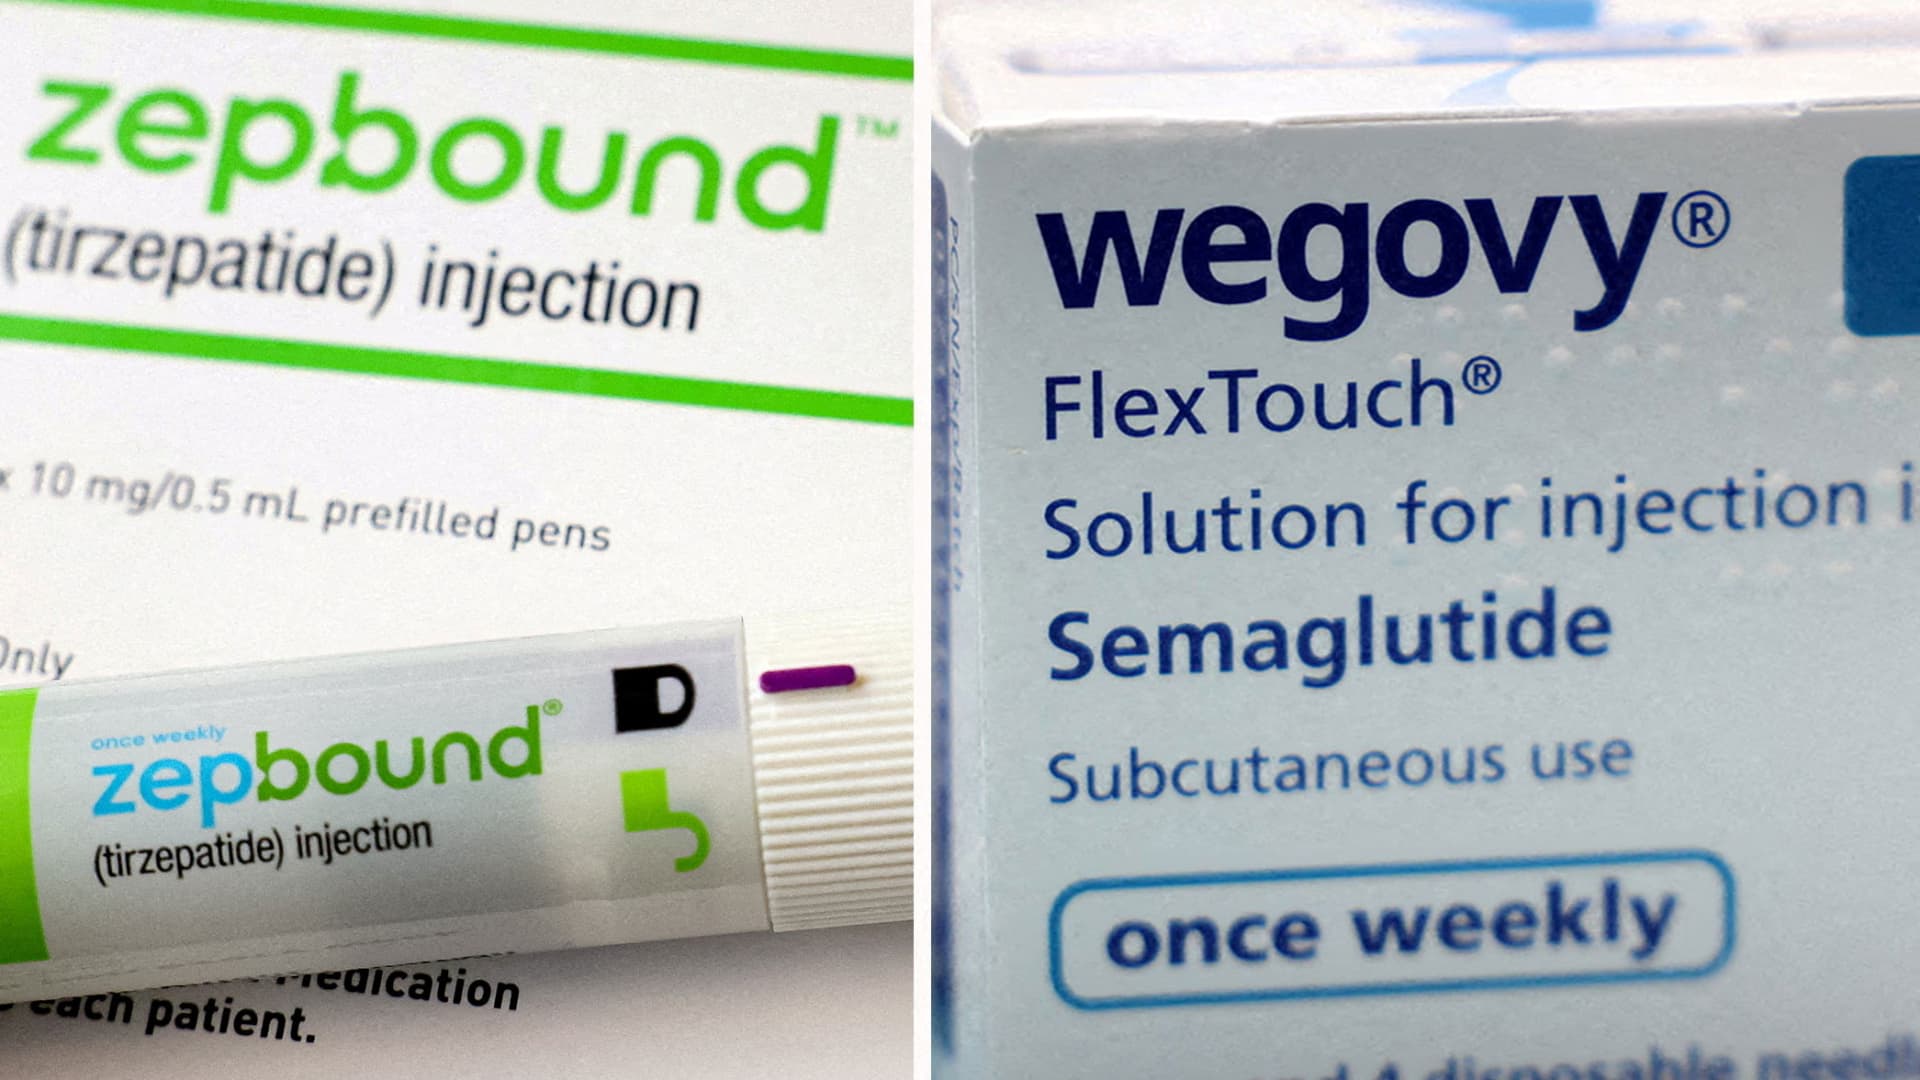
Interestingly, many individuals may choose to finance these drugs themselves, even if their employers don’t subsidize them. For example, the starting price for the lowest dose of Novo’s Wegovy for those paying out-of-pocket is currently $149 per month for the pill and $199 for the injection. These prices may change in 2027, and Novo Nordisk has indicated that promotional pricing could be adjusted or discontinued.
Direct-to-Employer Programs
Some firms are exploring direct-to-employer models, where they remove GLP-1 coverage from their traditional pharmacy program but offer to reimburse a portion of employees’ out-of-pocket expenses.
“These alternative models can help employers access better pricing and gain more control over their expenditures without offering the drugs through their pharmacy benefit manager,” explained a spokesperson for Vida Health, which collaborates with employers on such plans.
Employers have the flexibility to tailor these programs to meet their employees’ needs while saving significantly compared to traditional GLP-1 benefits via pharmacy benefit managers, noted Alysha Fluno from Marsh.
Weight Management Programs
Many employers are also turning to outside organizations like CVS Weight Management, Noom, Omada Health, UnitedHealthcare, Vida, and Virta to offer weight management programs, either alongside or as a replacement for GLP-1 coverage. Some companies were already providing these types of support, but others have only established them since reducing GLP-1 benefits.
According to data from Marsh, 25% of employers with over 500 employees had partnered with vendors for lifestyle and nutrition support. These services, commonly funded by the employers, are typically cheaper than GLP-1 coverage and can include coaching on diet, exercise, and other health topics, with costs ranging from $65 to $100 per employee each month.
Service providers report positive outcomes, with some studies indicating that a majority of participants maintain or continue to lose weight after discontinuing GLP-1 therapy. However, according to Gallagher’s Friedman, motivating employees to consistently engage with these programs can be difficult, particularly when they know they can simply obtain a prescription for GLP-1 medications.
Using FSA and HSA Funds for GLP-1
While flexible spending accounts (FSA) and health savings accounts (HSA) are not complete substitutes for a comprehensive health plan, GLP-1 medications can be reimbursed through these accounts when prescribed for a specific medical condition like obesity. However, one drawback of using an HSA is that the funds do not grow tax-free for later use in retirement.
For 2026, individuals can contribute up to $4,400 to an HSA for self-only coverage, and up to $8,750 for family coverage. This amount will increase in 2027 to $4,500 for individuals and $9,000 for families. The IRS has yet to announce the contribution limits for FSAs for 2027.
“These benefits are intended to help cover out-of-pocket expenses,” emphasized Andrew Stocker from Voya Financial. “Employers really need to inform their employees about the benefits that are available.”