France’s Growing Crisis and Its Implications
President Trump recently stated that France is burning, and while he’s correct about the fires, he misinterprets what’s fueling them.
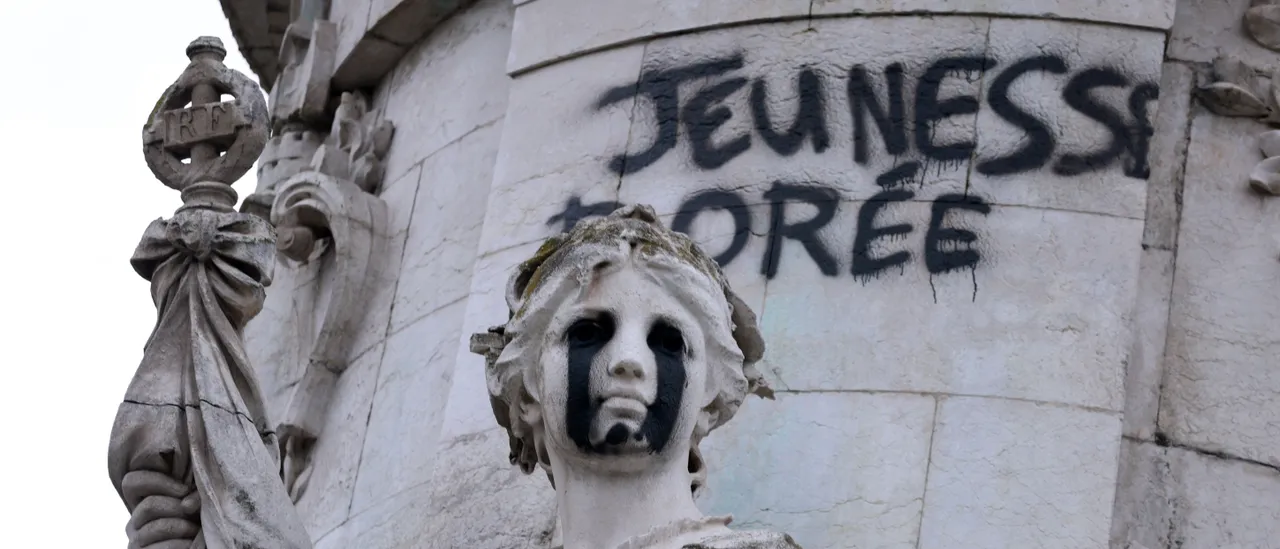
On October 17, somewhere between 550,000 and 800,000 protesters marched across various cities in France. By the end of the day, a historic town hall in Limoges was set ablaze, and about 1,800 individuals were taken into custody. This event followed weeks of student protests that had already disrupted numerous schools. In his response, President Trump attributed the unrest to immigration, urging the French to tighten their borders.
However, the demonstrators had a different message. Their anger stems from the rising cost of living, overstretched public services, and a future that feels increasingly unattainable. It’s fundamentally an issue tied to financial strains, which could eventually affect the U.S. if left unaddressed.
Let’s consider the financial situation in France. The country’s debt sits at around 120 percent of its GDP. Next year, it plans to allocate approximately 74 billion euros just to manage this debt—this figure surpasses what is spent on education or defense. Add to that the fact that borrowing costs have reached their highest levels in 24 years. In just under a year, two prime ministers have lost their positions over budgetary disputes, demonstrating the severe challenge any administration faces when attempting to tackle these issues.
Now, turning to our situation in the U.S.
The Congressional Budget Office forecasts that net interest on our national debt will roughly double to about $2.1 trillion by 2036. This amount would consume nearly half of all revenue collected by Washington. Presently, we already spend more on interest than we do on national defense.
There isn’t a single moment of crisis; rather, it’s a gradual downward spiral, putting pressure on every other function the government is expected to fulfill.
Next, we must consider wealth distribution in the country.
A recent Federal Reserve survey indicated that between 2022 and 2025, the median net worth of households headed by individuals aged 75 and older will see an increase of about 38 percent. In contrast, households led by those under 35 will see a decline of 23 percent. It turns out that Americans aged 55 and older now hold approximately $140 trillion, representing about three-quarters of the nation’s total wealth.
It’s important not to point fingers at older generations; many have worked diligently and saved for their futures. However, a society where the younger population is falling behind while the older generation thrives, and where the burden of debt falls on the young, isn’t sustainable.
Bringing these elements together creates a troubling picture. An increasing portion of the budget is allocated for interest payments, while younger generations struggle to find affordable housing or build savings. It feels like a competition for increasingly limited resources.
This mirrors the situation in France, where pensioners, students, farmers, and unions are all expressing valid frustrations in the streets. The government is stretched too thin to address everyone’s needs, as funds have already been allocated elsewhere.
What is needed is a long-term growth strategy alongside a serious discussion about fiscal limits. After all, genuine growth is the only real solution. A swiftly growing economy can manage its debts, keep its commitments, and provide genuine opportunities for young people. Achieving this involves increasing infrastructure, expanding workforce training, and supporting entrepreneurship. It requires reforms before the bond markets force solutions upon us.
Unfortunately, neither political party seems to fully grasp that. One treats deficits as issues for the future while making tax cuts. The other proposes new expenditures without addressing funding sources. Both are inclined to defer the impending crisis until after the next election.
If we want to avoid the turmoil seen in France, it’s essential for our country to adopt a sense of fiscal accountability and maturity. This doesn’t necessarily mean drastic cuts to benefits but calls for a sustainable, long-term strategy that requires effort, compromise, and bipartisan teamwork, rather than simply pandering to party lines to maintain support.
This is why many Americans seem to be distancing themselves from both parties. Independents have surged to become the largest voting group, and they are neither confused nor disengaged. They’re frustrated with a political system that continues to push long-term considerations onto others.
With the midterm elections looming just weeks away, it’s crucial for voters to challenge candidates with a vital question: What’s your plan for economic growth, and what sacrifices are you willing to make to achieve it? If they don’t have a clear answer, they may not be adequately prepared for what lies ahead.
France serves as a potent reminder of where this trajectory can lead. We still have the opportunity to choose a different path, but time is of the essence, and the cost of inaction is rising.