Health Insurance Rate Hikes in Pennsylvania Prompt Calls for Federal Action
HARRISBURG — With health insurance companies proposing significant rate increases, the Shapiro administration finds itself limited in its ability to cap these hikes and is urging federal action.
In the past nine months, nearly 202,000 individuals have dropped their plans through the state’s marketplace, Pennie. This decline followed Congress’s decision to let subsidies expire, leading to a surge in premium costs.
Consumer advocates and healthcare professionals worry that this number could escalate further if the Pennsylvania Insurance Department approves the proposed 2027 rate increases by insurers. They are part of a coalition that is urging the agency to either decrease or freeze the proposed rates.
According to Matt Yarnell, president of SEIU Healthcare Pennsylvania, “Pennsylvania families are being squeezed from every direction, and now insurance corporations want to make it worse by demanding double-digit rate hikes while posting billions in profits and paying their executives eight-figure salaries.”
The insurance department is responsible for reviewing the annual rate filings from health insurers, and it plans to release the final rates prior to open enrollment, which takes place from Nov. 1 to Jan. 15 each year.
Insurers are seeking to raise average rates for individual plans by 10% to 40%, and for small group plans by 4% to 34%. In comparison, the rate increase range for 2024 was between -3.5% and 13% for individual policyholders and around 4.1% for small groups.
However, a spokesperson clarified that the department does not have the power to “uniformly freeze all health insurance rate increases.” According to state law, rates must not be “excessive, inadequate, or unfairly discriminatory,” leaving actuaries to assess these factors during their reviews.
The actuaries evaluate historical data, along with the companies’ projections related to medical claims, advancements in technology, and general healthcare costs.
Rates can be disapproved if an insurer fails to provide adequate justification, yet a spokesperson did not respond to inquiries about whether any filings have been rejected recently, although experts couldn’t recall any such incidents.
During the review process, the department can raise concerns and discuss modifications with insurers. Meanwhile, last year, insurance firms largely achieved their desired rate increases, some even exceeding their initial requests. Rising costs for care and medications were commonly cited, alongside the loss of enhanced premium tax credits.
Independence Blue Cross and Highmark, the only insurers to respond to requests for comments, cited similar reasons for their current proposals, claiming they balance patient costs while maintaining financial stability.
Health policy experts point to the cessation of enhanced federal subsidies as a major contributor to soaring premiums and a resulting drop in younger, healthier individuals opting out of coverage. State Insurance Commissioner Michael Humphreys previously warned of this trend.
Additionally, significant factors driving costs higher include prescription medications, physician services, and hospital care, according to Meredith Rosenthal, a Harvard health policy expert. Interestingly, Rosenthal noted that increased insurer profits do not appear to be causing the significant premium growth observed.
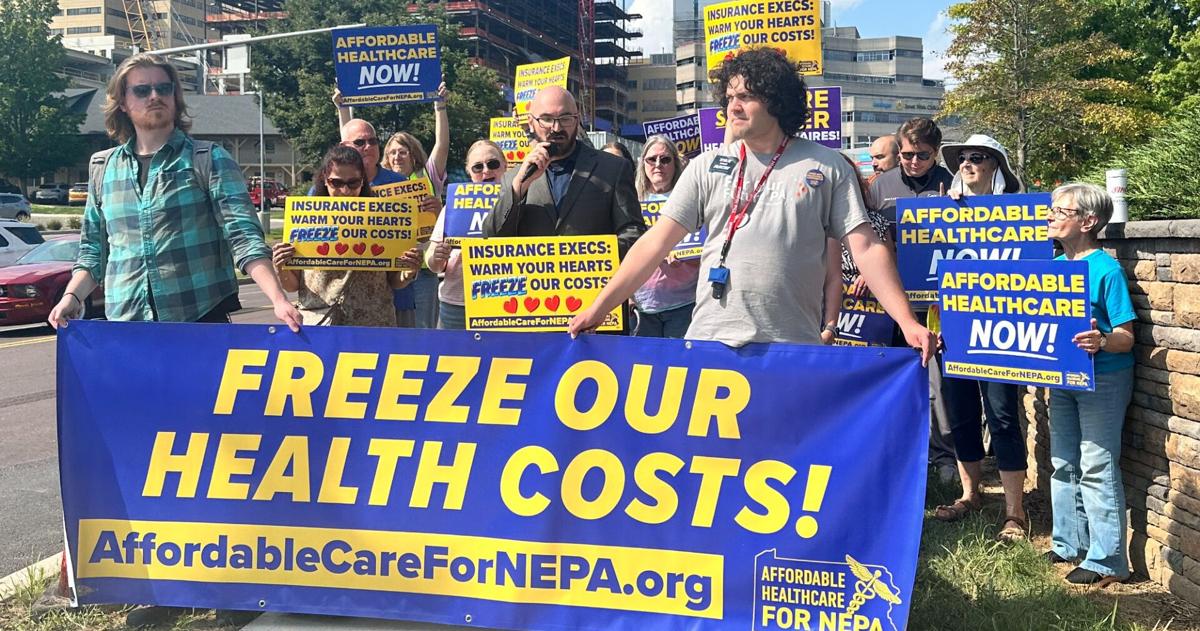
Still, insurance companies are often blamed for rising costs, which is echoed by the coalition Affordable Healthcare for PA. This group, which includes various healthcare professionals, argues that insurers prioritize their profits over consumers, even as they boost administrative salaries and expand their operations.
The coalition organized protests outside the headquarters of major insurance companies in August, with advocacy director Kristin Volchansky stating, “When people are struggling so much to afford just basic necessities in healthcare, there’s more that’s required of these providers.”
The group also criticized Geisinger, a health system that provides insurance, citing extravagant compensation packages reported by its leadership and significant profits noted by its parent company, Kaiser Permanente.
Geisinger did not provide comments regarding its rate proposals to media inquiries.
Members of the coalition who met with the insurance department in August expressed skepticism about the agency’s ability to make impactful changes to the proposed rate hikes.
Patrick Keenan, director of policy at the Pennsylvania Health Access Network, noted that Pennsylvania’s insurance regulators have moderate power compared to others across the country, aiming to protect consumers while ensuring a competitive market.
Keenan described the state’s situation as “at a breaking point,” emphasizing the need for proactive measures to ensure that more people can maintain their healthcare coverage.
Humphreys mentioned in a recent interview that he hopes the final rates will be lower than those proposed. He acknowledged the public’s frustrations with rising costs and the challenge of balancing claims payments without unnecessary premium increases.
Rosie Lapowsky, spokesperson for Governor Josh Shapiro, stated that rising healthcare costs are a direct consequence of decisions made by previous administrations, particularly impacting working families.
The Shapiro administration is committed to holding insurance companies accountable while striving to minimize rate increases.