U.S. Home Sales Decline in July
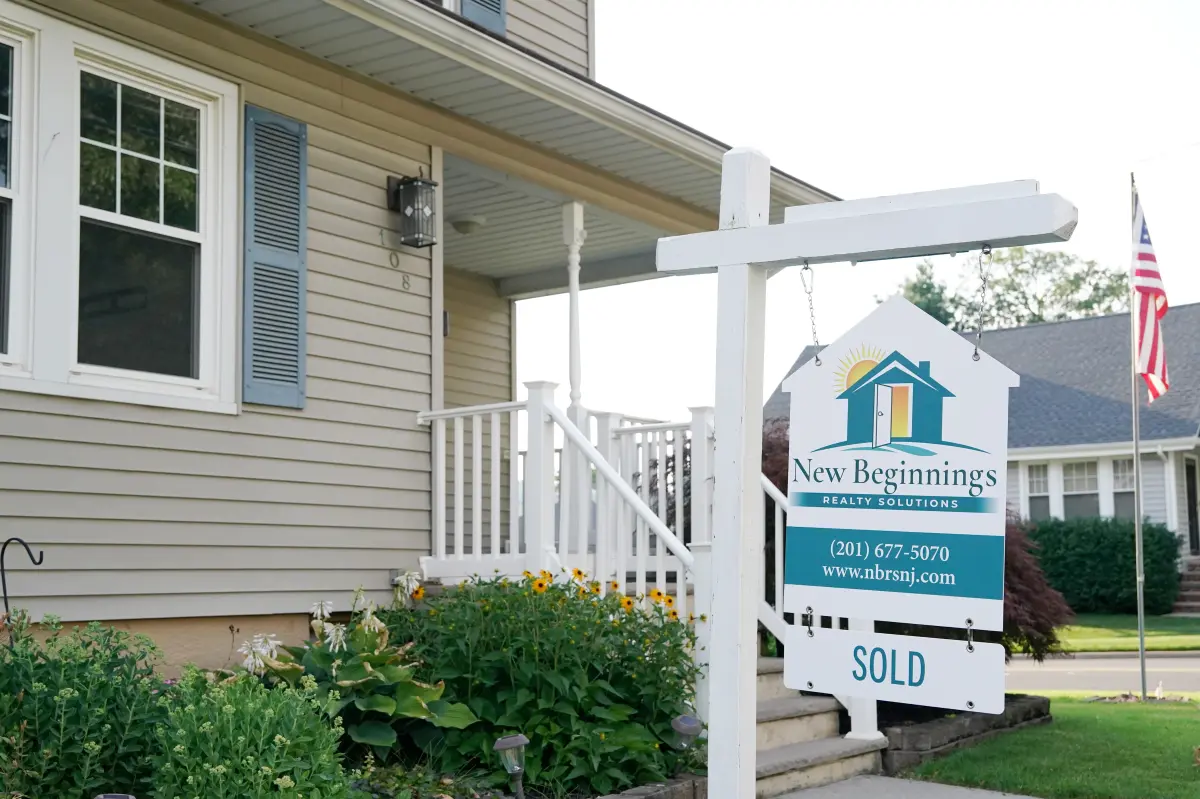
Sales of previously owned homes in the United States saw another decline in July. The high prices and rising mortgage rates are proving tough for many potential buyers.
According to the National Association of Realtors, existing home sales dropped by 1.7% from June, landing at an annual rate of 4.06 million units, which is just above the 4.05 million that economists predicted, based on FactSet data.
Interestingly, July sales were up by 0.7% compared to the previous year.
Prices continued to climb, reaching record levels for July. The median sale price stood at $434,100, a 2% increase from the previous year.
Recent data from Freddie Mac indicated that the 30-year fixed mortgage rate jumped to 6.69%, the highest it has been in over a year. This marks the fifth consecutive week of rising average interest rates, adding another layer of difficulty for those looking to purchase homes.
NAR’s Chief Economist Lawrence Yun commented, “Despite the environment of rising mortgage rates, home sales have remained surprisingly stable. If average mortgage rates return to around 6%, we could see a healthier housing market.”
Current home sales have been hovering around 4 million annually for approximately three years, which is considerably below the historical norm of about 5.2 million.
The U.S. housing market has been on a downslide since 2022, when mortgage rates began to increase from their pandemic lows. Last year’s used home sales were essentially stagnated, marking the lowest levels in 30 years.
Much of the sluggish sales can be attributed to rising mortgage rates, which have been climbing recently amidst international tensions, particularly with the war between the U.S. and Iran. This situation has fueled inflation expectations, affecting long-term bond yields that influence mortgage pricing.
Inventory levels didn’t fare much better, remaining well below historical averages. By the end of July, there were about 1.54 million unsold homes, down 1.9% from June of the previous year and 0.6% from July. This is significantly lower than the typical pre-pandemic levels of around 2 million units.
As for market balance, current inventory represents a supply of about 4.6 months at the ongoing sales rate. Generally, a balanced market between buyers and sellers is identified by a supply of five to six months.
Regionally, home prices in the Northeast continued to rise at a higher rate compared to the rest of the country, with a 5.2% increase year-on-year driven by inventory shortages.
Moreover, first-time homebuyers made up 29% of sales, which is slightly down from 33% in June but a small rise from 28% in July 2025. Historically, first-time buyers constituted nearly 40% of the market.