Soaring Auto Loan Payments Strain American Consumers
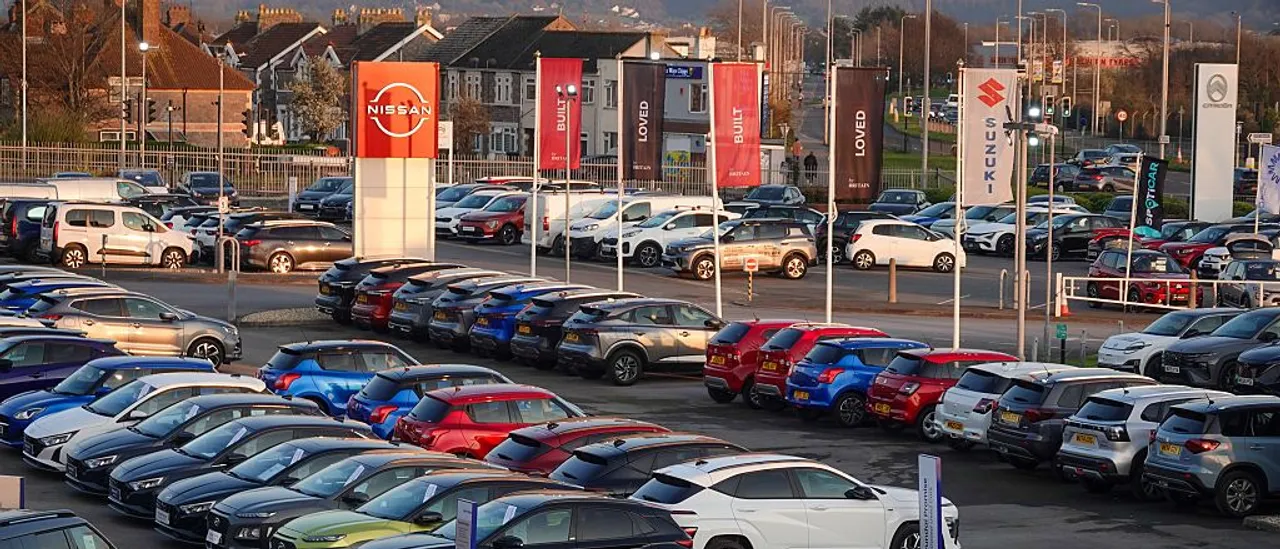
It appears that over one in five Americans financing new cars are now stuck with monthly payments of at least $1,000—this is a new high. A recent report from automotive research firm Edmunds indicates that many buyers are taking on larger loans to keep up with the rising prices of vehicles.
This trend is raising eyebrows, especially as Americans have accumulated more than $1.7 trillion in vehicle debt, which, by the way, surpasses the total outstanding credit card debt in the nation. There are also growing worries about longer repayment periods and increasing defaults among higher-risk borrowers. It makes you wonder whether consumers can really keep up with this auto debt.
During the third quarter, a record 21.2% of financed new car purchases had monthly payments of at least $1,000, up from 19.1% the previous year. That’s quite a leap, don’t you think? The average monthly payment has also reached a record $787, with the average amount financed climbing to $44,664, which is higher than $42,744 from the same time in 2025.
Additionally, people seem to be extending their car loans over longer terms. In fact, more than one in four financed new cars, specifically 25.5%, now come with repayment terms of at least 84 months. This is another record—it’s, well, a bit concerning, frankly.
These extended repayment periods mean that vehicles become even more expensive over time. Edmunds estimates that the average new-car borrower will pay around $9,938 in interest over the life of the loan, despite the average annual percentage rate holding steady at 7%. It raises a few eyebrows, right?
The difficulty is especially pronounced for Americans buying used vehicles through finance companies. As of June, the average interest rate for those loans reached 15.92%, according to data from the Federal Reserve Bank of St. Louis. If we take the Federal Reserve’s average used-car loan amount—around $24,958—and assume a repayment period of approximately 66 months, a borrower could be staring down monthly payments of about $570. That’s no small change.
Over the length of that loan, they might end up paying around $12,656 just in interest, which means about a third of every dollar they repay would go toward interest instead of the principal. That’s, um, quite a significant chunk. This calculation assumes a fixed-rate loan with equal monthly payments and no extra fees.
An October analysis from Reuters Breakingviews raises further alarm bells. It suggests that these prolonged repayment periods are leaving some higher-risk borrowers with debts on cars that could become unreliable before their loans are even paid off. A startling statistic is that over 30% of subprime auto loans issued in the first half of 2026 are set to remain unpaid until the financed cars are over 12 years old. That’s a big jump from just 7% at the end of 2019.
The financial strain is also evident in delinquency statistics. An October report from KBRA indicated that 6.64% of borrowers in its non-prime auto loan-backed securities index were at least 60 days overdue on payments in September, an increase from 6.39% in August. In contrast, the rate for prime borrowers was only 0.57%. It’s a bit of a discrepancy, wouldn’t you say?
Americans who are already finding it tough to manage their current cars might also struggle to get out from under those loans. Nearly 30% of vehicles traded toward new purchases during the second quarter were carrying negative equity, meaning the owners owed more than the cars were worth, according to other findings from Edmunds. That’s quite problematic.
Those owners were about $6,884 underwater on average, which complicates things quite a bit, as they face the daunting possibility of incorporating that debt into their next car purchase. The Federal Reserve Bank of New York noted that outstanding auto loan balances hit $1.713 trillion in the second quarter, compared to $1.263 trillion for credit cards. Although delinquency rates across most household credit types remained relatively stable, new auto loan delinquencies are still at high levels.