Banking institutions and non-bank financial entities (NBFIs) function under the same central bank, but finance companies that are well-managed seem to be facing stricter rules concerning deposits, lending, and loan adjustments. Meanwhile, banks have been steadily encroaching on services traditionally offered by non-banks, as highlighted by top executives in the NBFI sector during a recent discussion.
Their argument is that the issue extends beyond just poorly managed NBFIs or bad governance. It appears that regulations put in place to tackle issues with certain failing finance companies are now creating difficulties for those institutions that are actually well-run.
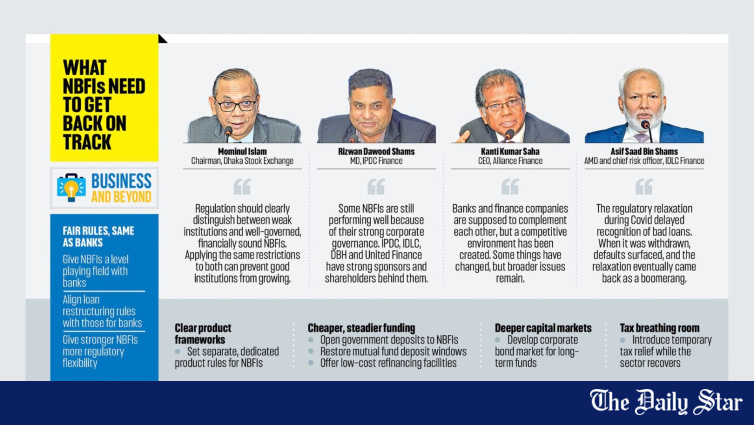
Regulation should clearly distinguish between weak institutions and well-governed, financially sound NBFIs. Applying the same restrictions to both can prevent good institutions from growing.
Mominul Islam, Chairman, Dhaka Stock Exchange
This exchange took place at an event called “Challenges and Prospects of NBFIs,” organized by The Daily Star. In Bangladesh, there are 35 NBFIs, which collectively hold about Tk 52,356 crore in deposits and Tk 78,114 crore in loans. The sector is currently experiencing a crisis, given that several finance companies have encountered failures. The central bank is in the process of liquidating four, with 16 others facing distress.
Some NBFIs are still performing well because of their strong corporate governance. IPDC, IDLC, DBH, and United Finance have strong sponsors and shareholders behind them.
Rizwan Dawood Shams, MD, IPDC Finance
Banks and finance companies are supposed to complement each other, but a competitive environment has been created. Some things have changed, but broader issues remain.
Kanti Kumar Saha, CEO, Alliance Finance
This situation has obviously hurt public trust in non-banking institutions. People are witnessing how troubled banks receive support, whereas those who invested in failing NBFIs are still left waiting for their repayments.
The regulatory relaxation during Covid delayed recognition of bad loans. When it was withdrawn, defaults surfaced, and the relaxation eventually came back as a boomerang.
Asif Saad Bin Shams, AMD and chief risk officer, IDLC Finance
According to him, the current regulations have largely been created around institutions that have failed, rather than allowing space for the stronger ones to expand.
Mominul believes that stronger enforcement of existing regulations, rather than simply adding more rules, is essential for addressing the sector’s issues. He pointed out that the excessive regulation has hindered well-performing firms from operating effectively.
The participants in the discussion noted that current rules regarding deposits and lending placed finance companies in competition with banks, despite the expectation that they should work together. This mismatch is particularly noticeable in retail and long-term loans, as banks have raised their lending thresholds while NBFIs remain limited.
Mominul identified a significant drawback: the limited access NBFIs have to long-term funding. This reliance on banks has stifled the growth of not just NBFIs but also housing finance and capital markets.
In contrast, he cited India as an example, where finance companies have bonds as a major funding source, with regulatory conditions clearly delineating capital, credit ratings, and borrowing limits. The process for bond issuance there takes roughly two months, while in Bangladesh, it can stretch to two years due to various approval requirements. Consequently, bonds contribute to less than 1 percent of NBFIs’ funding in Bangladesh.
Mominul argued that regulators ought to focus on establishing and enforcing clear rules, rather than getting involved in everyday operational matters. He questioned the logic of having regulators dive into every aspect of operations, saying it undermines accountability for compliance.
Greater accountability from auditors and credit-rating agencies is also necessary; repeated failures among institutions evaluated by the same agencies shouldn’t just be seen as isolated occurrences, he insisted. “The emphasis should be on enforcement, not additional regulation,” he urged.
During his remarks, Kanti Kumar Saha, CEO of Alliance Finance PLC, expressed the need for a fair playing field that allows non-banks to complement banks effectively.
“NBFIs are constrained to the fewer services they can provide compared to banks,” said Rizwan Dawood Shams, managing director of IPDC Finance. He noted that deposits are essentially the raw material for business. While banks have the option to manage current and savings accounts (CASA), NBFIs do not, which puts them at a disadvantage with higher-cost term deposits.
Additionally, he pointed out that NBFIs have restrictions preventing depositors from withdrawing funds before three months without prior approval from the Bangladesh Bank, which inherently raises their cost of funds. “We could lower our funding costs if permitted to manage deposits from government entities and mutual funds,” he noted. This funding disadvantage complicates NBFIs’ ability to compete with banks in areas like home and auto loans, especially since banks are now also offering longer terms for home loans.
Rizwan clarified that this isn’t about seeking favoritism. “We aren’t asking for anything out of the ordinary. We just want policies aligned with banks,” he added.
Asif Saad Bin Shams, AMD and chief risk officer at IDLC Finance, shared that non-performing loans at NBFIs have surged to roughly 37 percent, indicating broader economic weaknesses exacerbated by the authorities’ responses to the pandemic. He pointed out that regulatory relaxations initially allowed borrowers to maintain a ‘regular’ status despite missed payments, but when these relaxations were lifted, many accounts were reclassified as non-performing from 2023 onward. “This regulatory relaxation eventually backfired,” he said.
Weak economic conditions have contributed to challenges affecting corporate, SME, and retail borrowers alike. The participants noted that while depositors generally perceive bank deposits as safer due to the support provided to struggling banks, those who invested in failing NBFIs have not received comparable protection.
This discrepancy goes beyond regulation; it also involves the public’s perception of the two institutions. Moreover, the difference is particularly stark when borrowers from troubled institutions seek to restructure their loans.
Kanti highlighted that, according to a recent guideline, banks can now reschedule or restructure loans for as long as 15 years, while NBFIs face an eight-year cap. Considering that finance companies were initially designed to offer long-term financing due to banks’ maturity mismatches, the situation has changed dramatically as banks encroached into these adjacent services.
Ultimately, said Kanti, finance companies find themselves with an entirely different funding framework yet still vying for the same clientele. The liquidity challenges faced by this sector have been compounded by a lackluster bond market and banks’ hesitance to extend long-term funding to NBFIs.