American households have been dealing with affordability pressures since at least 2022. Things improved considerably through much of last year and into February, but conflicts abroad have set back some of that progress. If the wars in Iran and Ukraine come to an end, the argument goes, costs should begin easing again.
The squeeze began during the Biden administration, when prices climbed much faster than wages and paychecks lost purchasing power. The average weekly paycheck rose about 17% over Joe Biden’s presidency, but could buy roughly 4% less by the end of it.
For some families, that meant giving up vacations or putting off a car purchase. Others relied on credit cards to cover essentials such as rent, medicine and groceries. And even after inflation cooled, prices remained high. Inflation measures how quickly prices rise, not whether they return to where they were before.
Inflation reached a 40-year high, prompting the sharpest increase in interest rates in decades. Families faced a double hit: goods cost more, and borrowing became more expensive. In housing, higher home prices and mortgage rates together doubled the monthly payment on a median-priced home in just four years.
Affordability began to improve after January 2025. From then through February of this year, inflation-adjusted weekly pay rose by about 2% on average. That was hardly a windfall, but it reversed around half of the losses accumulated during the Biden years as wages grew faster than prices.
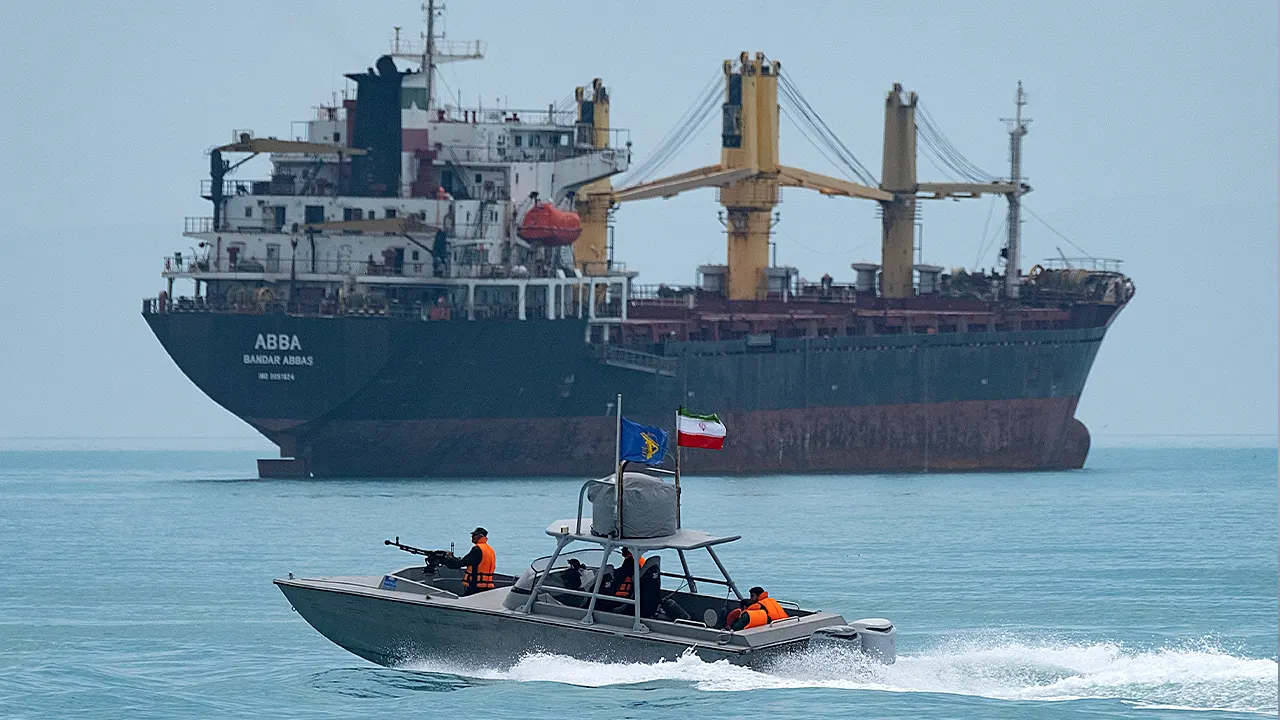
Tax and regulatory changes, along with energy policies, were helping spur activity and wage growth while keeping inflation in check. Then the war with Iran began, disrupting energy markets and supply chains and pushing costs sharply higher.
Oil prices jumped from around $60 or $70 a barrel, depending on the market, to roughly $100 or $120. Gasoline costs soon rose too, and the effects have spread to other parts of the economy.
Energy is built into the cost of almost everything people buy. Food is grown using diesel-powered equipment and fertilizer made with natural gas, then carried to stores by trucks—and sometimes trains—that also run on fuel. Air travel, plastics and manufactured goods have all felt the pressure.
Housing affordability has also slipped. It reached a three-year high in February, a notable improvement from the record lows seen during the Biden years, though it was still difficult for many buyers. Since then, it has fallen every month, reaching its weakest point since July 2024 as interest rates climbed.
Those higher mortgage rates are partly tied to the energy shock. As fuel supplies tightened and prices rose, expectations for inflation increased. Lenders then sought higher returns to account for the possibility that inflation would persist, pushing interest rates up.
The disruption is coming from Eastern Europe as well as the Middle East. Ukrainian attacks on Russian energy infrastructure have added to shortages of oil and petroleum products, particularly diesel. That has meant higher prices and weaker inflation-adjusted earnings.
This is different from the rapid inflation that peaked above 9% in 2022. The current price increases, the article argues, are being driven by an energy shock rather than by government spending, borrowing and money creation that eroded the value of the currency.
That distinction matters because the causes—and potential remedies—are different. Affordability had been improving before overseas energy disruptions intervened. The view presented here is that the underlying U.S. economy remains in sound shape.
Investment is growing, manufacturing is expanding at its fastest pace in at least four years, and private employers are adding jobs. Productivity is also getting a boost from artificial intelligence, while earnings continue to rise. If conflicts abroad are resolved, energy markets could stabilize and costs may begin to fall.
Lower energy prices would ease pressure on household staples and other consumer goods. Inflation expectations could decline too, bringing interest rates down and making homeownership more attainable. For families, that combination of rising earnings and slower cost increases could provide some welcome room in the budget.
The effects would not be immediate. Supply chains take time to recover, and prices do not adjust all at once. Still, the argument is that a return to peace would help affordability improve, with many of the other conditions already in place.