There’s No Struggle Between Fed and Treasury Right Now
If you pay attention to financial analysts—like hedge fund managers, Wall Street economists, and, well, those who write about finance—there’s this idea circulating that there’s a sort of war happening for the soul of the bond market.
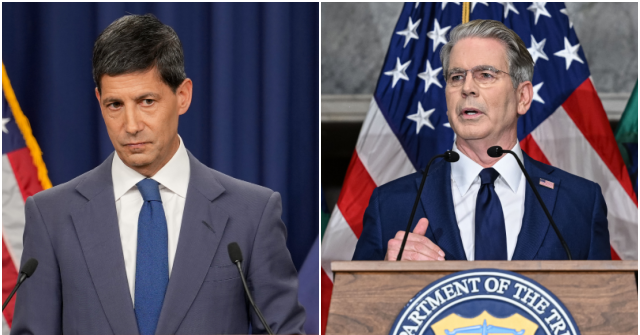
On one side, you have Treasury Secretary Scott Bessent, who is buying back long-term government bonds. On the other side is Federal Reserve Chairman Kevin Warsh, tasked with the difficult decision of whether to lower yields or leave Bessent “in even deeper trouble,” as a recent newsletter from the Wall Street Journal captured it.
But there’s a fundamental issue with this narrative: Warsh and Bessent aren’t actually at odds. They don’t view themselves as adversaries.
Bessent sees the repurchase of Treasury debt as part of normal debt management, which falls under the Treasury Department’s jurisdiction. Meanwhile, Warsh views interest rate policy and the control of the Fed’s balance sheet as monetary policy, which is distinctly the central bank’s role. He can support Bessent’s buybacks while still maintaining a hawkish stance on inflation. It turns out he’s perfectly comfortable with Bessent handling fiscal operations while he focuses on monetary policy.
How QE Ate Fiscal Debt Management
Interestingly, the confusion around Bessent’s buybacks actually confirms one of the longstanding criticisms of quantitative easing.
When the Fed started purchasing mortgage-backed securities and long-term Treasury debt after the financial crisis, critics argued that it was crossing the line into fiscal policy. Philadelphia Fed President Charles Plosser contended that decisions regarding credit allocation should be made by fiscal authorities. Richmond Fed President Jeffrey Lacker referred to credit policy as “a form of fiscal policy.” Monetary historian Michael Bordo noted that the Fed had become involved in “debt management through quantitative easing.”
The objection became even louder when the Fed initiated Operation Twist, which involved selling shorter-term securities and buying longer-term bonds. The Treasury could achieve the same maturity transformation simply by altering the mix of bills, notes, and bonds it issued. So, it appeared as though the Fed was utilizing its balance sheet for something that resembled Treasury debt management.
After nearly twenty years, it seems the Fed has kind of claimed this territory—at least in the eyes of many financial journalists and economists.
Because the central bank spent so long buying government bonds, many pundits now view any purchase of government bonds as inherently monetary. For example, when the Treasury buys back its own securities, Bloomberg refers to it as a form of “quantitative easing,” while the Journal labels it an unusual intervention in the bond market. The Treasury is now accused of intruding into an area that once exclusively belonged to it, before the Fed stepped in.
The mechanics behind all this have only added to the confusion. If the Treasury uses funds from its Fed account to repurchase a bond, that transaction increases reserves in the banking system while removing a longer-term security from private ownership. When viewed through the consolidated government balance sheet, this can appear similar to QE.
Debt Management Is Not QE
Yet, Treasury spending, tax collections, debt issuance, and cash management inherently influence bank reserves and bond balances. That doesn’t mean every tax payment or Treasury auction constitutes an act of monetary policy. The Fed can adjust for reserve movements if they conflict with its desired stance. Furthermore, when the Treasury purchases a security, it funds that purchase using revenue generated from taxes or bond sales. In contrast, when the Fed does this, it simply creates new bank reserves via keyboard entries.
Additionally, Treasury debt management inevitably impacts yields. Actions like issuing more short-term bills, reopening older bonds, changing auction sizes, or buying back less liquid securities will shift prices in the market. Each time the Treasury decides how much debt to issue at an auction and which maturities to sell, it essentially “manipulates” the term structure of government debt, exerting influence on the yield curve. If affecting yields equates debt management with monetary policy, then the Treasury lacks meaningful authority over its debt.
However, following such an extended period of quantitative easing—what the Fed once referred to as “extraordinary” measures—Treasury oversight of its own liabilities is now viewed as an improper meddling. Meanwhile, the Fed’s role in helping contain the government’s borrowing costs is considered a normal part of central banking.
This reflects the institutional landscape that critics of QE warned about, a concern Warsh also shared back when he served as a Fed governor around two decades ago. The Fed engaged in fiscal-like functions for such a long time that financial commentators lost sight of where those responsibilities originally resided. The confusion regarding Bessent’s buybacks might just be one of the lasting legacies of QE.