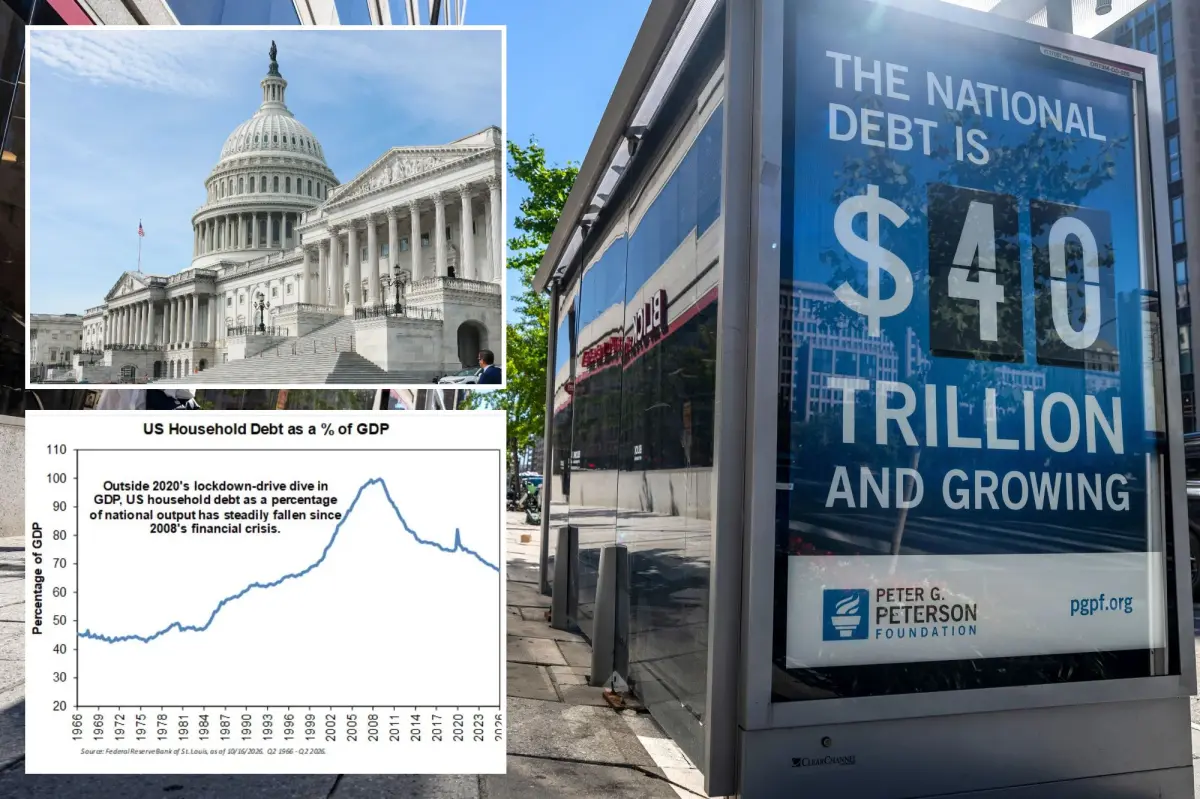
Yes, the national debt crossed the $40 trillion mark in August – that’s trillion with a “T” – but let’s be cautious about the alarmist talk of “doom loops” and “death spirals.”
It’s understandable to feel anxious. After all, it’s not pleasant to think about annual interest payments that exceeded $1 trillion last year, which is, well, more than the U.S. defense budget came close to hitting.
Still, let’s try to step back and consider a few facts that are often overlooked when discussing our national debt.
Fact: When measured correctly, the debt has actually decreased over the last decade. You read that right – decreased, not increased!
People often focus on the type of debt that’s making headlines – whether that’s credit card debt, government bonds, mortgages, or auto loans. Large, round figures, like $40 trillion, can easily provoke outrage.
However, these seemingly overwhelming numbers can be misleading without proper context. It’s important to look at the bigger picture over time.
Fact: Total global debt, across all types, has declined compared to the overall size of the global economy – and significantly at that. Government, corporate, and household debts worldwide total 246% of global GDP, down from a peak of 285% in 2020. We’re back to levels last seen in 2016, and we’re nearing figures from 15 years ago.
So how did we get here? Partly due to the massive inflation created by central banks during the COVID era. That’s the bad news. But it also made paying off existing debt cheaper, as noted previously. Since 2020, the ratio of global public debt to GDP has gone down from 111.5% to 95.6%.
Fact: Corporate debt relative to GDP has also decreased, from 106.6% to 93.3%. Household debt around the globe dropped from 69.8% to 59.8%. Surprisingly, we could still take on another $42 trillion in debt globally before hitting 2020’s debt-to-GDP peak, and that level didn’t derail economic growth.
In America, when you discount intergovernmental debt, the federal debt-to-GDP ratio is about 100%. That’s a rise from around 60% in 2010—a point that fuels the fears about debt.
But, that view misses other important details. U.S. corporate debt hasn’t changed much in relation to GDP. Meanwhile, domestic household debt has dramatically decreased from nearly 100% of GDP in 2010 to 67% now, which largely offsets the rise in government debt. Who would have thought?
What presents a greater risk to the economy? Too much individual debt or too much government debt? We generally feel it’s the former. Governments have the ability to tax and inflate their way out of debt crises; individuals, on the other hand, can only default.
Recent trends show that individual and corporate debts are decreasing relative to GDP while the federal debt is increasing. Altogether, both American and global debt situations appear to be improving.
Even in terms of government debt, the landscape is looking better. Which is riskier, excess municipal and state debt or excessive federal debt? Typically, it’s the former. Back in 2010, state and municipal debt was 21% of GDP; now it’s just 11%.
The main takeaway in America and globally is that after the recessions of 2008-2009 and 2020, many sectors—consumers, businesses, municipalities, and states—learned valuable lessons. Uncle Sam, however, seems slower to adapt. Would you rather see the reverse?
What about federal interest payments? Are they really spiking alongside yields? To a degree, but still, taxes cover interest payments generously. Historically, the share of interest payment compared to tax revenue was similar during the late 1980s and early 1990s, before the economy boomed. As that boom expanded tax revenues, debt payments also improved.
This shouldn’t be considered a tipping point; rather, it feels more like a return to normalcy. Many countries have endured far worse sovereign debt challenges than what America faces now. Interest rates have reverted to levels that were typical before the Fed’s unusual quantitative easing policies flattened them.
Just to clarify, I’m not promoting more federal debt. I’m also not attempting to endorse the wisdom of politicians (which, let’s be honest, is often questionable). But really, there’s no need to spend time, energy, or money on doomsday debt scenarios.