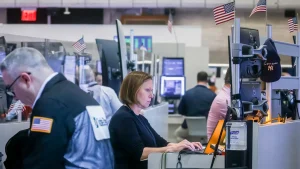
A sharp sell-off on Thursday sent major U.S. stock indexes lower and raised concerns about the effect on retirement savings. Financial advisers urged investors not to make rushed decisions in response to the market’s swings.
The Dow Jones Industrial Average fell 1,833 points, or 3.44%. The Nasdaq Composite dropped 5.52%, putting it in correction territory, while the S&P 500 lost 4.36%. Technology and semiconductor shares were hit hard as investors weighed the possibility of new artificial intelligence regulations after Democrats’ midterm election gains.
The declines may reduce 401(k) balances, especially for people whose savings are heavily invested in stocks. How much they’re affected will depend on their portfolios and how soon they expect to retire.
Market losses raise concerns for retirement savers
Mark J. White, a wealth adviser, said investors should be cautious about making sudden changes to their retirement plans. Market declines can be unnerving, he said, but reacting emotionally may pose a greater risk than the drop itself.
For younger workers, continuing regular 401(k) contributions during a downturn may mean buying investments at lower prices, White said.
Jay Duffy, co-founder and managing partner at Frame Wealth, said he is more concerned about people nearing retirement whose portfolios may not be suited to a major decline. Someone in their early 60s, for example, may have less time to recover from losses than a younger investor.
Retirees who need to sell investments to pay living expenses during a downturn face what financial planners call sequence-of-returns risk. Selling after prices have fallen can speed up the depletion of savings.
White advised people approaching retirement to keep enough cash and more conservative investments to cover expenses in the near term. That can reduce the chance they’ll need to sell stocks while the market is down.
He said a retirement date shouldn’t prompt panic, but it should shape how a portfolio is prepared. A plan, he added, should account for market declines rather than require a major overhaul whenever one occurs.
Duffy said investors may want to rebalance if their portfolios no longer fit their risk tolerance or retirement timeline. Automatically selling—or simply doing nothing—may not be the right response for everyone.
His advice: avoid making lasting financial decisions based on temporary market emotions.