Forward Guidance Gets a Nobel at Dusk
The Royal Swedish Academy of Sciences, following the advice of its Economic Sciences Prize Committee, has awarded the prestigious prize to the pioneer of forward guidance, just as central banks appear to be moving away from this influential policy.
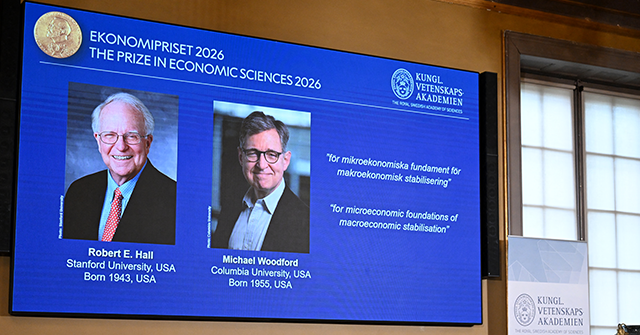
This past Monday, Michael Woodford, an economist from Columbia University, shared the economics prize with Robert Hall from Stanford University for their pivotal work on the foundations of economic stabilization. Undoubtedly, both have significantly contributed to the field and merit this recognition. Woodford, in particular, helped shape the New Keynesian framework, which has become the standard language in academic macroeconomics and central banking.
Given that this announcement comes five months after Kevin Warsh assumed leadership at the Federal Reserve and started phasing out forward guidance, it’s difficult not to interpret the decision as a subtle criticism of the new chairman. The committee has chosen to honor the individual whose work laid the groundwork for the very policy Warsh is now moving away from, highlighting a stark contrast.
The End of the Age of Forward Guidance
However, this award might also signify the conclusion of an era. To reflect philosophically, Hegel noted that the owl of Minerva flies at dusk, suggesting that true understanding often comes when a practice is waning. The economics community might be heralding forward guidance just as its relevance begins to dwindle.
In his 2005 paper titled “Central Bank Communication and Policy Effectiveness,” presented at the Jackson Hole symposium organized by the Kansas City Fed, Woodford detailed how central banks could steer economic activity by altering expectations regarding future policy.
The rationale for forward guidance becomes particularly convincing when interest rates hit zero and the economy remains sluggish. In such scenarios, central banks face dilemmas since they can’t effectively stimulate further by reducing rates. Woodford’s insights indicated that a credible commitment to maintaining low rates could spur immediate investment and spending, allowing additional stimulus even after conventional rate cuts were fully utilized.
Initially, this was merely a theoretical concern for the U.S. and Europe. However, during the global financial crisis, central banks drastically lowered their policy rates and struggled to prevent economic collapse. The Fed adopted forward guidance officially, and in the nearly two decades following the crisis, it became a staple of monetary policy, prompting markets to closely analyze statements for hints about future decisions.
Warsh has recognized the value of forward guidance during that crisis. Nevertheless, he argues that the practice has outlived the conditions that warranted it. Promises about future rates can hinder necessary adjustments when new information emerges. Warsh cited how forward guidance might have delayed the Fed’s reaction to inflation in 2021. He’s also concerned that a market overly influenced by Fed indications may provide less reliable insights for policymakers.
Such concerns raise significant questions about turning what was meant as an emergency tool into a regular feature of central banking.
Warsh Has Company
The European Central Bank has reached similar conclusions. At its Sintra conference in June, President Christine Lagarde stated that forward guidance was something the ECB had moved away from, deciding instead to make decisions based on the latest available data.
“In times of uncertainty, forward guidance loses its value,” she remarked.
The ECB continues to clarify its policy framework and has distanced itself from commitments about future interest rate paths. Its September policy statement reiterated that it would not be committing to any specific rate trajectory.
Similarly, Pierre-Olivier Gourinchas, the then-outgoing chief economist of the International Monetary Fund, expressed that it was “entirely appropriate” to step back from strong forms of forward guidance.
Warsh’s view reflects a broader reassessment of monetary policy following the inflation surge. In stable periods, when central banks can adjust rates, the necessity for additional stimulus through promises significantly lessens, and uncertainty makes such commitments more challenging and potentially detrimental.
While Woodford merits commendation for illustrating why future policy holds significance, Warsh raises pertinent questions about the Fed’s ongoing promises regarding that future.
The Nobel might serve as the concluding chapter for forward guidance, marking the beginning of the Warsh era.