Rising Car Insurance Costs: What You Need to Know
Car insurance rates have been on the rise in the first half of this year, reversing the declining trend seen in 2025. A recent report suggests that more than 30 states will experience increases this year.
An analysis by Insurify reveals that car insurance premiums actually dropped by 6% last year, affecting drivers in 39 states. However, in the early months of 2026, average full-coverage premiums increased by 1% to $2,237, with 27 states reporting higher costs so far and a total of 32 expected to follow suit before the year ends.
“Unfortunately, we’re seeing most states trending upwards this year,” said Insurify CEO Snejina Zacharia in a conversation with FOX Business. She pointed out that severe weather and accident-related issues have remained significant factors.
“Additionally, we have witnessed a 45% spike in repair costs, which greatly influences insurance claims. This will prompt insurers to make adjustments on a state-by-state basis,” she added.
Impacts from Auto Industry Tariffs
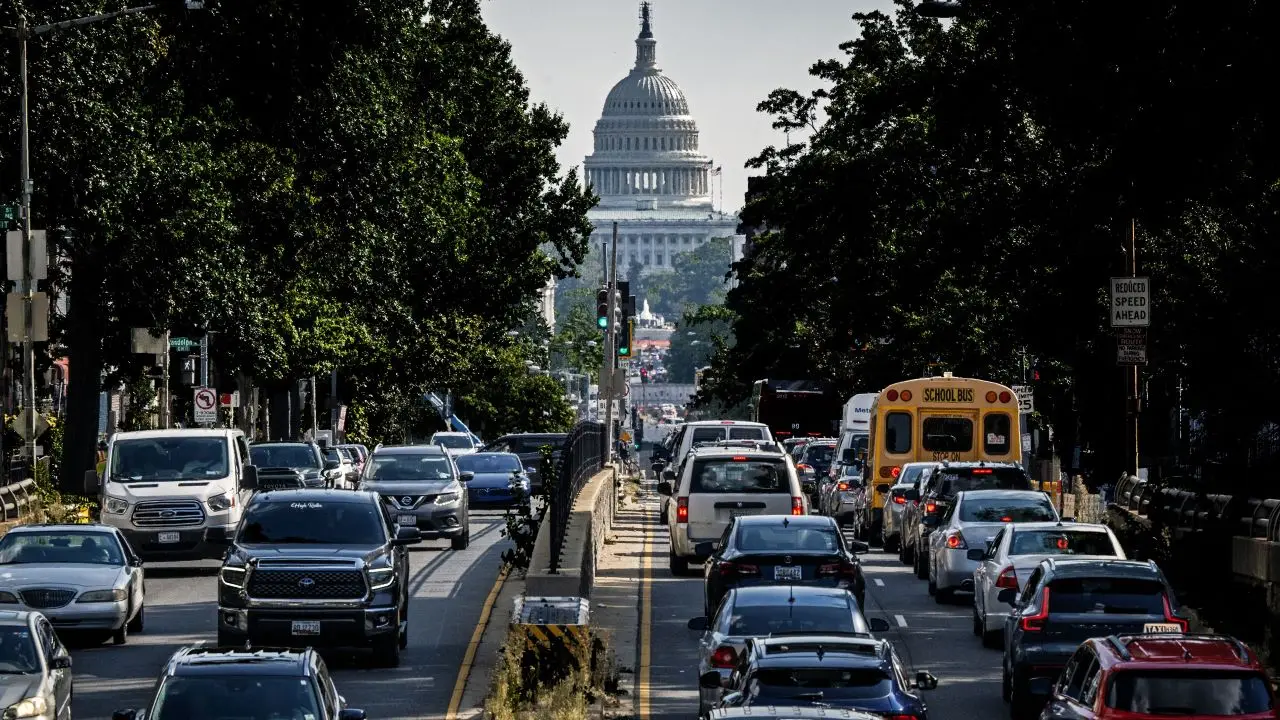
Interestingly, Washington, D.C. reported the most significant drop in car insurance premiums; however, it still holds the title for the highest rates in the nation.
Zacharia noted that the trend of rising repair costs began a few years back due to the COVID pandemic and ongoing chip shortages, compounded by inflation and tariffs affecting auto parts.
Some of the largest hikes have occurred in states where insurance has historically been affordable. For instance, West Virginia saw a 5% rise in rates in the first half of the year, while Kentucky’s rates jumped from $58 below to $65 above the national average.
Both of these states are expected to witness an 8% annual increase by the end of 2026.
Steep Increases in Car Insurance Rates
A notable rise is anticipated in Connecticut, where premiums could soar by 15% this year. Over the past five years, rates in Connecticut have jumped by 67%, reflecting a general trend of increases across the country.
Conversely, some areas have seen a reduction in rates for the first half of the year. Washington, D.C., for example, experienced a 7% decrease, expected to finish down 5% from the previous year, despite having the highest average full-coverage premiums at $3,955. This decline is, in part, attributed to fewer auto thefts and fatal accidents.
New Mexico also enjoyed a 6% drop in premiums this year, likely finishing down 8% at around $1,587. Meanwhile, New York and New Jersey each noted a 5% decrease in the same period and are projected to end 2026 down by 4%, with total costs nearing $2,900 each.
Consumer Strategies for Lower Premiums
Zacharia suggested that consumers looking to lower their insurance costs might consider increasing their deductibles or modifying coverage options.
“If your car is quite old, you might be paying more for insurance than the car’s worth. In such cases, comprehensive or collision coverage might not be necessary,” she advised.
She also emphasized that each insurance provider offers different discounts, highlighting the importance of shopping around. Just because you’ve been with the same provider for years doesn’t automatically mean you’re getting the best rates.
“Insurance rates can be unpredictable, and it’s essential to compare offerings from various providers to determine what your best options truly are,” she concluded.
Zacharia mentioned that Insurify’s platform gathers discounts from 120 auto insurance carriers, enabling it to offer tailored rates for individual customers.