Credit Card Installment Plans Gain Traction Over BNPL
Credit card installment plans are positioning themselves as a significant player in the buy now, pay later (BNPL) landscape, offering the card industry new advantages.
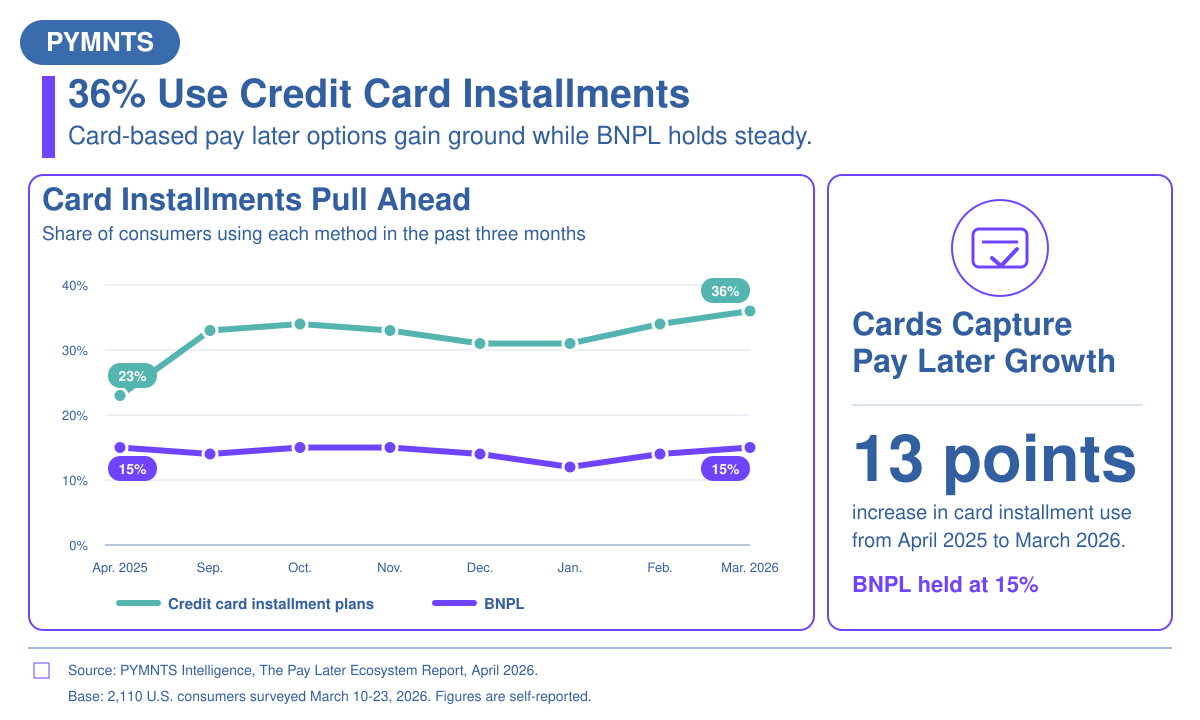
A recent PYMNTS Intelligence report titled “The Pay Later Data Shift: Credit Card Installments Take the Lead” reveals that, as of March 2026, consumers utilized card installment plans at more than double the rate of BNPL. Specifically, the use of card installments surged to 36% from 23% in April 2025, while BNPL remained stagnant at 15% throughout the same period. This indicates that the pay-later market is evolving to leverage existing distribution channels and customer relationships rather than relying on a single dominant product.
Key Findings:
- Card installments experienced a notable increase of 13 percentage points. Their usage expanded across eight surveys, hitting 33% in September 2025 and reaching a peak of 36% in March 2026. In contrast, BNPL usage fluctuated only between 12% and 15%. This enables card issuers to provide installment financing through accounts customers already have, making adoption smoother without requiring new account sign-ups. It feels a bit like having a dedicated fast lane in a familiar store.
- Younger consumers showed a preference for card-based options. The utilization of credit card installments among Gen Z jumped to 47% in March 2026 from 31% the previous year. Meanwhile, their use of BNPL has grown slightly to 23%. Millennials echoed this trend, using card installments at rates about 1.8 to 2.5 times higher than BNPL. This suggests that younger consumers are keen on splitting payments but may not particularly favor standalone BNPL providers.
- Higher income individuals drove BNPL usage. Consumers with yearly earnings of at least $150,000 engaged with BNPL at roughly double the rate of those earning under $50,000, with respective shares of 20% and 10% in March. This trend positions BNPL as a budgeting tool that resonates across various income levels but is particularly popular among those with greater financial flexibility.
The report suggests that the pay-later model is evolving into a feature within larger financial relationships. While BNPL providers still play a vital role in the market, card issuers leverage their existing customer networks, historical account data, and established merchant relationships. This combination offers banks, financial networks, and fintech firms opportunities to enhance visibility, improve controls, and increase consumer choices.
The insights are based on PYMNTS Intelligence surveys conducted monthly from September 2025 to March 2026, covering approximately 2,500 U.S. adults since the survey series began in April 2025.