Student loan borrowers now have until December 2026 to set up auto pay and benefit from a 1% reduction in their interest rates.
The initial deadline was September 30, but the U.S. Department of Education decided to extend this to allow borrowers more time for enrollment. This rate reduction will remain in effect until June 2028.
For those currently using auto pay, there’s already a discount of 0.25%, meaning this new reduction adds on an additional 0.75%.
The intention behind this temporary benefit is to assist borrowers, especially as many are transitioning back to repayment and navigating the new Repayment Assistance Plan, which requires timely payments.
According to Lesley J. Turner, an associate professor of public policy at the University of Chicago, borrowers with significant loan balances on fixed payments stand to gain the most. “For a limited time,” she noted, “those who enroll in auto pay can enjoy a full percentage point off their interest rate. This effectively quadruples the previous benefit, which is substantial for borrowers carrying large balances.”
Since the announcement of the interest reduction over the summer, almost 2 million borrowers have signed up for automatic payments.
As of June, around 9 million Americans were in default on their federal student loans, with many more at risk of falling behind this year.
If you’re considering enrolling your student loans in auto pay, here’s what you should keep in mind:
If you’re new to auto pay, enroll by the end of the year
To qualify for the 1% interest reduction, you need to enroll in auto pay by December 31.
Start by logging into your student loan servicer account and selecting the auto pay option. You will need to provide your bank details to allow automatic withdrawals for your monthly payments.
Even without the interest reduction, setting up auto pay is a smart strategy to manage your student loans, according to Turner. “Life can get hectic, and if you have to log in each month to make your payments manually, there’s always a chance you might forget,” she remarked, noting the risk of loans becoming delinquent.
If you’re already enrolled, you already have the reduction
If you signed up for auto pay before the July announcement, your interest rate has been automatically lowered by 1%, as stated by the Education Department.
If you’re currently in default, consolidate your loans
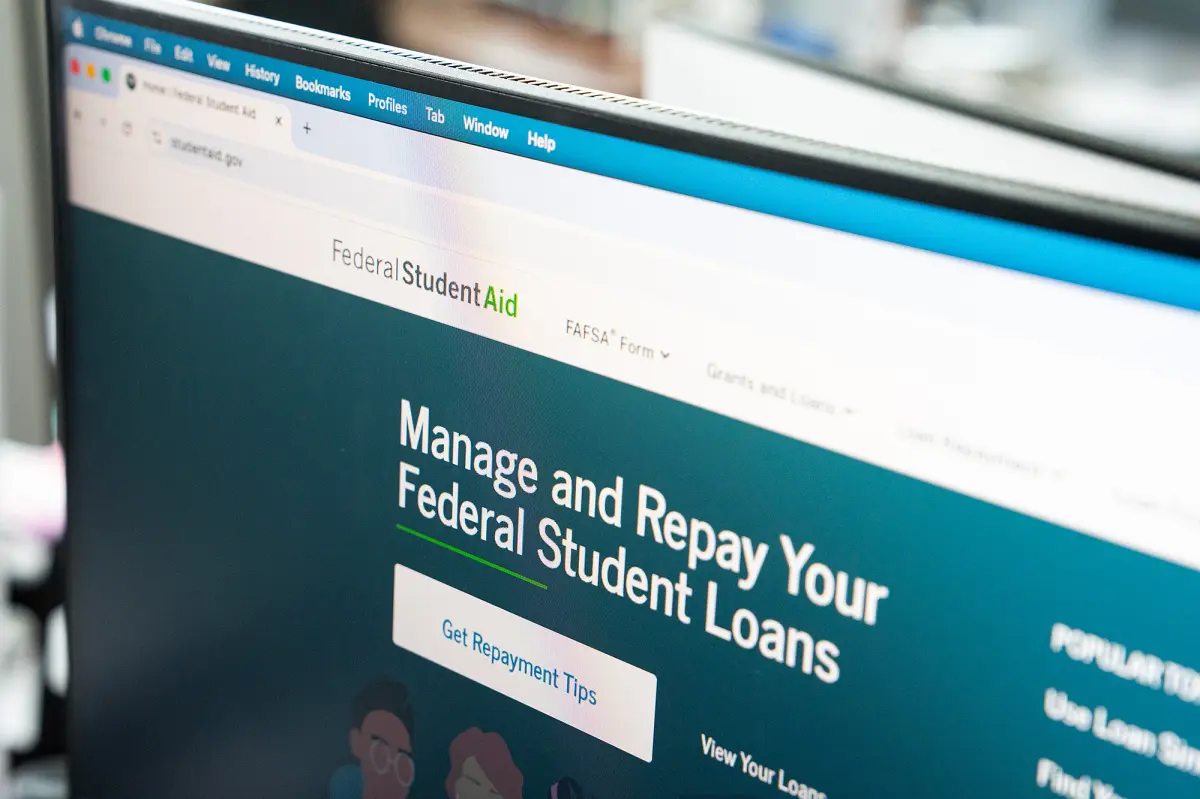
For those with defaulted loans, you’ll need to log in to studentaid.gov to consolidate your eligible loans to enroll in auto pay.
Involuntary collections for federal student loans are still on hold. The preceding administration had announced plans to delay withholding pay from borrowers in default. A borrower is deemed in default after being 270 days late on payments.
For loan consolidation, you can apply online at studentaid.gov/loan-consolidation. If you have various federal loans, consolidating them can simplify your payments into one with a fixed interest rate. Typically, this process takes about 60 days, and you can only consolidate once.
If you’re in default, you can also reach out to your loan holder about a loan rehabilitation program. This involves enrolling in a reduced payment plan, and after making five successful payments, wage garnishments will cease.
More details on loan rehabilitation can be found online.