Buy now, pay later (BNPL) was initially thought to siphon customers away from credit cards. However, it seems that credit cards are now incorporating aspects of BNPL.
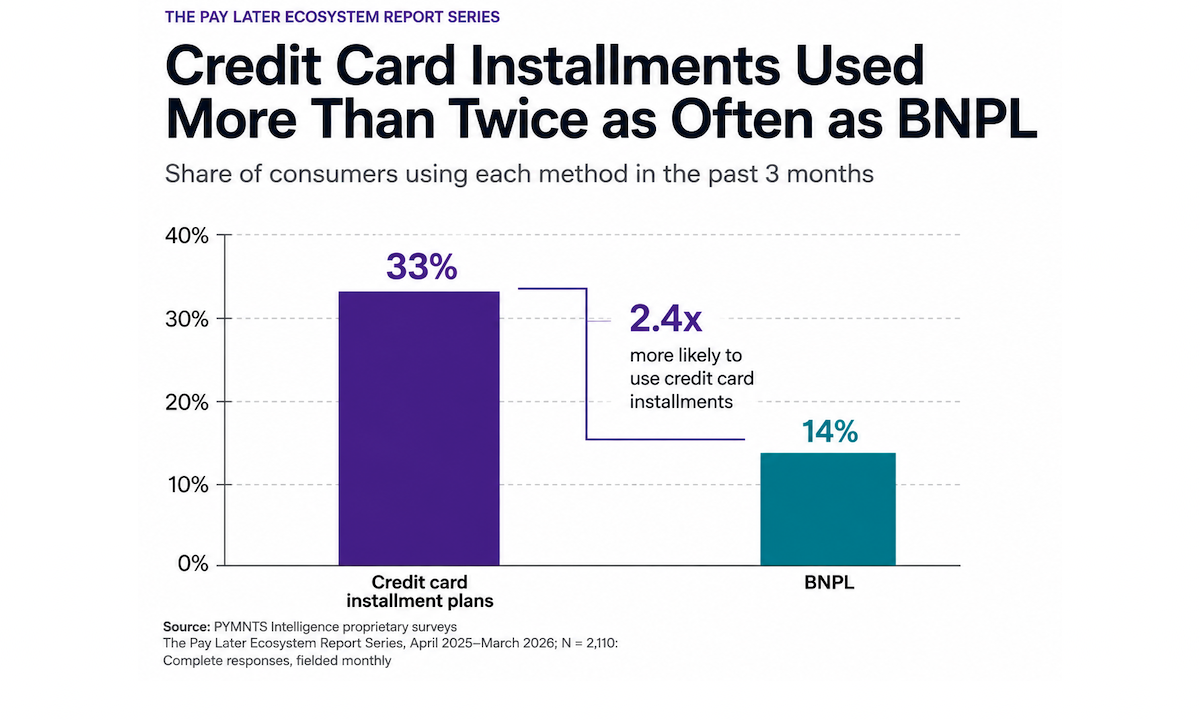
A recent study featured in the Pay Later Ecosystem Report by PYMNTS Intelligence indicates that more consumers are opting for installment plans attached to their credit cards. This gives credit card issuers an advantage in a market that BNPL has popularized. The research suggests consumers are more than twice as likely to use credit card installment options compared to standalone BNPL services.
This shift doesn’t really indicate a total abandonment of Pay Later options but rather a preference for payment methods. Card issuers can easily implement installment features within existing accounts, allowing customers to manage payments without resorting to a separate BNPL provider.
The data highlights increasing benefits:
- By March 2026, it’s projected that 33% of consumers will utilize credit card installment plans, a rise from 23% in April 2025, whereas BNPL usage has dipped slightly from 15% to 14%.
- In March, 47% of Gen Z consumers turned to credit card installments, significantly outpacing the 23% who chose BNPL.
- Among consumers earning $150,000 or more, 20% used BNPL in March, compared to 10% for those earning less than $50,000.
The trend among different age groups is particularly interesting. While BNPL is often linked to younger shoppers, they aren’t exclusively gravitating towards those standalone services. For instance, the usage of credit card installments by Generation Z rose from 31% in April 2025 to 47% by March 2026, while their usage of BNPL stayed steady at 23%. Millennials and Bridge Millennials exhibited similar trends.
Income levels add another layer to this discussion. BNPL has persistently attracted more consumers with incomes of $150,000 or above compared to those earning less than $50,000. In November, 22% of high earners used BNPL versus 7% of low earners, and in March, those figures changed to 20% and 10%, respectively.
This suggests that Pay Later isn’t merely a safety net, but rather a method for consumers to manage their purchases and cash flow more effectively.
For banks, card networks, and fintech companies, the data indicates that Pay Later is evolving beyond just a simple payment option; it’s now a part of a larger financial framework. BNPL has created a demand for manageable payment structures, and credit card issuers seem to be capitalizing on that within the accounts customers already maintain.
These findings stem from a survey conducted by PYMNTS Intelligence involving around 2,500 adults in the U.S.