Oil Prices Rise Amid Renewed U.S.-Iran Tensions
Oil prices are climbing again as renewed hostilities between the U.S. and Iran have halted tanker traffic in the Strait of Hormuz. This rise has pushed the West Texas Intermediate price index close to $85 per barrel, marking a more than 25% increase since the collapse of a ceasefire agreement earlier in July. So, while there was some hope for affordability in June, U.S. drivers are now facing pressure on their wallets as gas prices exceed the $4 per gallon mark once again.
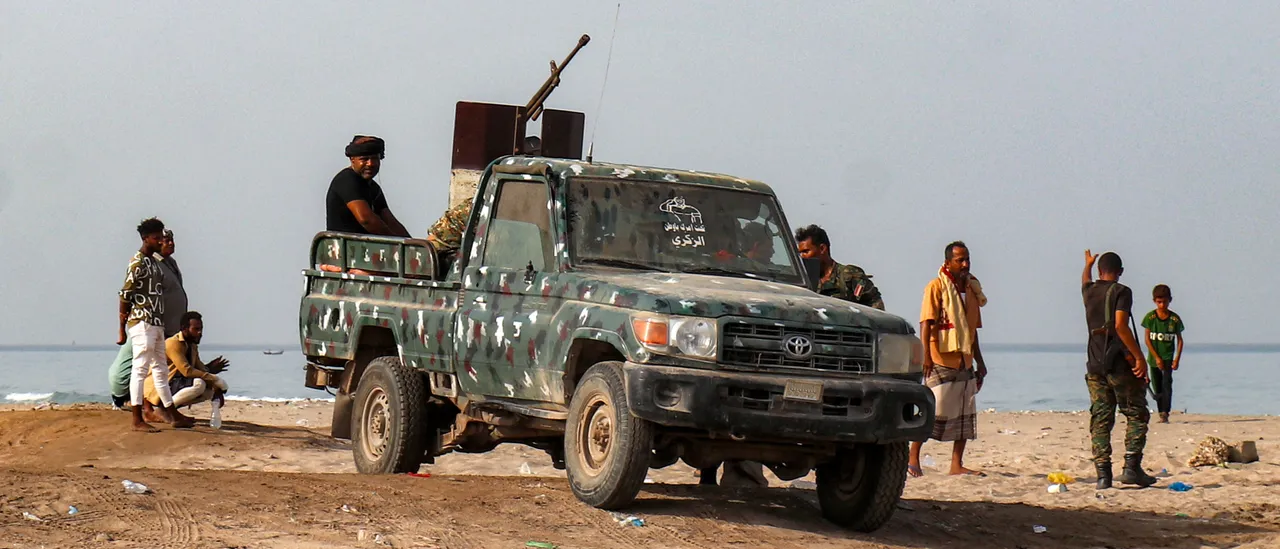
The situation has become more precarious this week, with the Houthi rebels in Yemen threatening to resume attacks on ships leaving the Red Sea through the Bab el Mandeb strait. A closure of this crucial shipping lane would significantly complicate Saudi Arabia’s ability to export its 7 million barrels of oil per day, as the Suez Canal cannot accommodate the largest oil tankers. Reports indicate that two major Saudi tankers had to turn back to port in light of these threats.
Additionally, the supply buffers that previously kept price surges in check have begun to vanish. If a quick resolution isn’t achieved, the current market environment suggests that energy prices are poised to rise further.
Initial Supply Buffers
When the Iran conflict ignited on March 1, there were a few supply buffers in place:
- A considerable inventory of crude oil already en route on tanker ships.
- Healthy reserves in various national strategic petroleum reserves, including the U.S. reserve.
- Normal or above-normal storage levels in significant onshore sites, such as Cushing, Oklahoma.
The swift action taken by China to utilize its strategic reserves, replacing lost imports from Persian Gulf nations, had also provided some stability, preventing a price shock akin to the one in 2008, when crude prices peaked at $147 per barrel. Now, however, some analysts express worry that a similar scenario could unfold, and traders who were previously optimistic appear to be shifting their outlook as tensions in the Middle East rise again.
Globally, commercial crude oil inventories, excluding strategic reserves, have been dwindling fast. Recent EIA data shows that U.S. crude stocks fell by an additional 564,000 barrels for the week ending July 10. This decrease marks three consecutive months of significant declines, with over 60 million barrels drawn down in the last twelve weeks. Gasoline inventories are also dropping, currently sitting 6% below the five-year seasonal average, indicating a market that feels tighter than usual.
The strategic petroleum reserve itself offers even less of a buffer than it has in times past. Current figures indicate the reserve stands at just 316.5 million barrels, the lowest level since 1983, and more than 415 million barrels shy of full capacity. Continued releases at the current pace could dangerously approach operational minimums, raising concerns about the structural integrity of the underground facilities where the oil is stored.
The deployment of the strategic reserve during this crisis aligns with its intended purpose, but Energy Secretary Chris Wright and the Department of Energy are dealing with an already depleted supply, largely a result of political decisions made prior to the 2022 midterms.
On the demand side, the pressures are building further. Chinese refineries have ramped up crude purchases, exerting additional strain on an already tight market. Simultaneously, bipartisan legislation progressing in Congress, including expanded sanctions on Russia’s energy sector, may further limit Moscow’s oil exports, tightening supply even more.
All these elements create a troubling mix poised for price increases. If President Trump manages to secure the Strait of Hormuz and mitigate Iranian influence on the Houthis, the immediate threat of dramatic price hikes could be averted. Otherwise, American consumers may see significant increases at the gas pump in the months to come.