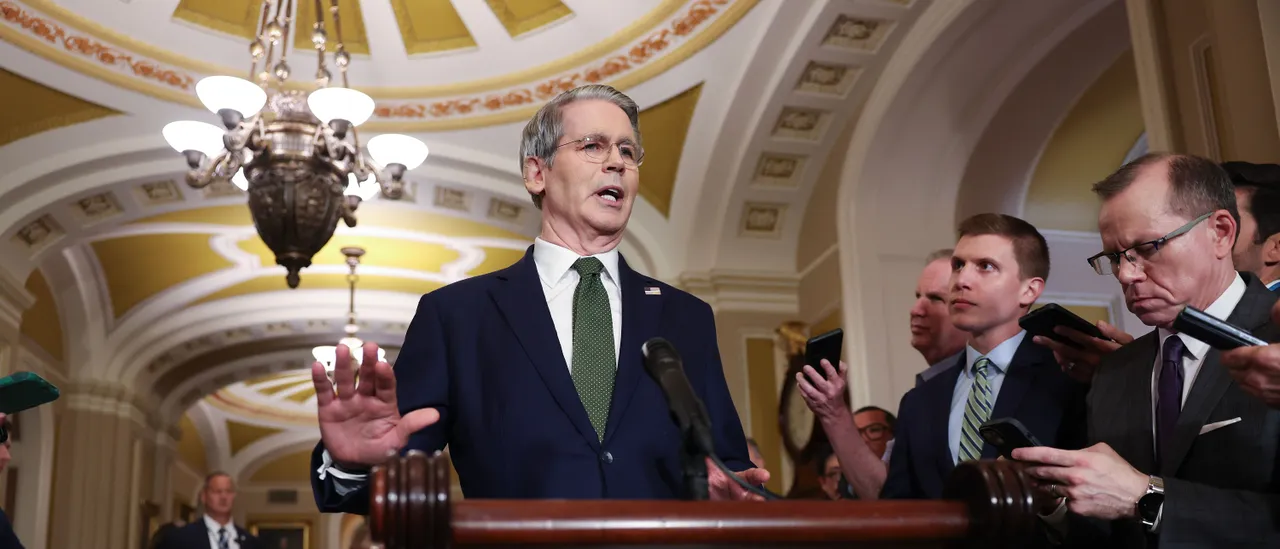
Treasury Secretary Scott Bessent shared limited details on Monday during his highly anticipated announcement regarding new sanctions against Iran.
The newly expanded “secondary” sanctions, which Bessent referred to as an “economic D-Day,” aim to escalate pressure on Iran amidst a “no war, no deal” situation. For years, Iran has faced international sanctions, yet its behavior in the region or its nuclear ambitions have remained largely unchanged, raising doubts about the effectiveness of a more comprehensive economic pressure strategy.
Bessent emphasized, “Let there be no ambiguity as to the position of the United States,” during a news conference. “Engaging economically with this murderous regime will subject those responsible to the full extent of American power.”
Bessent did not offer a specific deadline for compliance but warned that the U.S. wouldn’t wait forever. “I’m not going to set a timeline, but we do not have infinite patience here,” he stated.
The Treasury Secretary also indicated that major trading partners of Iran, including China, would face scrutiny under these measures. “No one is above this,” he asserted when asked about targeting China. “This is about economically suffocating this regime… and no one should test our resolve.”
The U.S. already has significant secondary sanctions in place against nations engaging with Iran, especially in its oil industry, but enforcement has often been inconsistent. For this new pressure initiative to work, Washington will likely have to rally its allies and tackle countries such as China, Russia, India, Pakistan, Qatar, and Turkey, which still conduct business with Tehran.
“Today, at President Trump’s direction, the United States Treasury has initiated Operation Economic Outcast, an unprecedented offensive against the Islamic Republic of Iran and its supporters,” Bessent explained. “In World War II, D-Day marked the launch of a coordinated effort with our allies to uproot the enemy from its strongholds. In that same spirit, we are now executing an economic assault on Iran’s global financial networks.”
This initiative broadens the scope of secondary sanctions for entities and nations conducting transactions with Iran, introducing restrictions across various sectors, including digital assets, gold, aviation, technology, and shipping, as reported by CBS News.
Bessent cautioned nations and entities against laundering money for Iran, stating that anyone involved in such activity “will be removed from the U.S. dollar system.”
He noted that while these sanctions wouldn’t take effect immediately, they provide an opportunity for rectifying prior misbehaviors. “Why would I want to disrupt the global financial system? It’s important to allow for a grace period, but they should understand that this will progress quickly and we are serious about it,” Bessent remarked.
He anticipated that a significant financial institution would soon face sanctions but did not provide further details, as reported by CBS News.
Dr. Steve Hanke, a professor at Johns Hopkins University, argued that the new sanctions were unlikely to yield success based on previous failures against Iran. “Sanctions have a near-perfect record of failing,” Hanke stated. “Examine the numerous sanctions enforced on Iran since the Islamic Revolution of 1979; none have achieved their intended goals. The D-Day sanctions will likely follow suit.”
Prices for essential goods remain high following the energy disruption caused by ongoing conflicts, while wage growth has stagnated at 3.2% over the past year, according to the BLS. With inflation outpacing wage increases, workers are losing purchasing power, even as the general inflation rate begins to ease.
According to the Federal Reserve Bank’s consumer finance tracking, this situation has forced working families to dip into their savings and increasingly rely on high-interest credit cards to cover basic expenses.
Since the start of military actions against Iran, energy prices have surged—exemplified by a 10.9% increase in March alone—resulting in a 14.7% rise in annual energy costs per BLS reports.
The ongoing high prices for crude and fuel, which are critical inputs in agriculture, manufacturing, logistics, and utilities, have rapidly affected the supply chain. This has resulted in higher costs for food, transportation, and home heating.