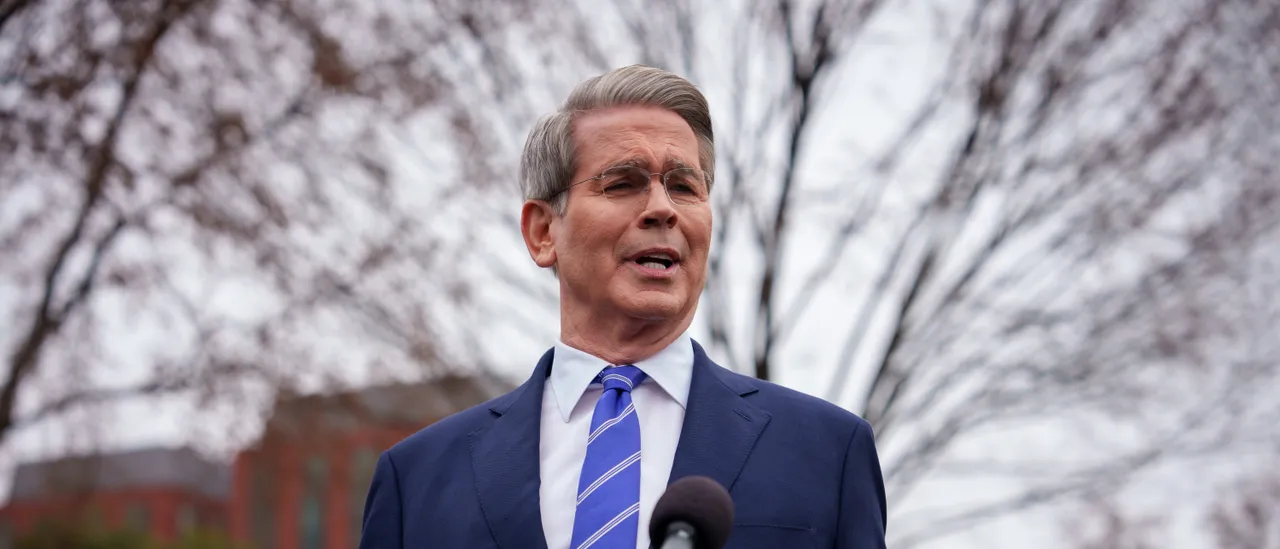
Treasury Secretary Scott Bessent might consider utilizing nearly $1 trillion from a cash reserve to facilitate Treasury bond buybacks. This move could empower the Trump administration in its efforts to lower long-term borrowing costs, especially as concerns about the U.S. fiscal sustainability grow among investors, as reported recently by CNBC.
The Treasury could tap into its General Account (TGA), which functions like the federal government’s checking account at the Federal Reserve, to fund its expanded bond-buyback initiative. Two senior Treasury officials noted to CNBC that the account has accumulated around $950 billion under Bessent’s management. This substantial cash pool could significantly bolster the Treasury’s initiatives to reduce long-term borrowing expenses.
The Daily Caller News Foundation reached out for comments from the Treasury Department but didn’t get an immediate response.
Bessent’s strategies have increased the account balance to about $950 billion, far surpassing the Biden administration’s aim of maintaining it at around $550 billion to $600 billion. Utilizing a portion of this reserve could give the Treasury an alternative funding source for supporting the long-term Treasury market without having to rely completely on more short-term borrowing.
Recently, the Treasury announced a plan to enhance its bond-buyback operations, increasing from $2 billion to maybe at least $4 billion per transaction starting September 9. Bessent also indicated that the purchases might go beyond this set amount.
This announcement led to an initial drop in Treasury yields, but the effect didn’t seem to hold as investors remained skeptical about the Treasury’s ability to significantly sway a bond market that supports more than $40 trillion in federal debt. However, leveraging the TGA might shift that perspective.
CNBC reported that Treasury officials did not specify how much of the approximately $950 billion in the TGA might be utilized or when an announcement regarding this would be made.
Amid increasing concerns about U.S. debt and borrowing costs, investors are looking for alternatives to the dollar. In August, the dollar index dipped by 2.43%, while gold and Bitcoin saw gains in light of the Treasury’s buyback announcement. Some market observers referred to this as the “debasement trade.”
On Friday, the 10-year Treasury yield moved closer to 4.7%, and the 30-year yield remained above 5%. This highlights the difficulties Bessent faces as the Treasury tries to lower long-term borrowing costs without weakening faith in U.S. government debt.
While accessing the TGA could provide additional resources, it may also deplete the government’s cash reserves needed to meet its obligations or manage a potential future debt-ceiling crisis.
The declining strength of the dollar could have broader implications beyond just the financial markets. If the dollar were to lose its reserve-currency status, it might diminish Americans’ purchasing power and elevate borrowing costs.
A study by the National Bureau of Economic Research suggested that the loss of this status could lead to around an 8.8% real depreciation in the dollar and raise U.S. real interest rates by about 90 basis points.
Economist Kenneth Rogoff has similarly cautioned that a weaker dollar might result in increased rates for home mortgages and car loans. He estimates that currently, Americans benefit from lower borrowing costs—about 0.5 to 1 percentage point less—thanks to the dollar’s unique standing.