Elder fraud expert shares tips to protect parents from scams
Matt Sanner, the founder of ScamSkeptic, emphasizes the increasing need to safeguard vulnerable seniors from scams, particularly those driven by AI technology. During an appearance on ‘America’s Newsroom,’ he provided advice on how to identify high-pressure phone tactics and assist parents in avoiding these fraudulent schemes.
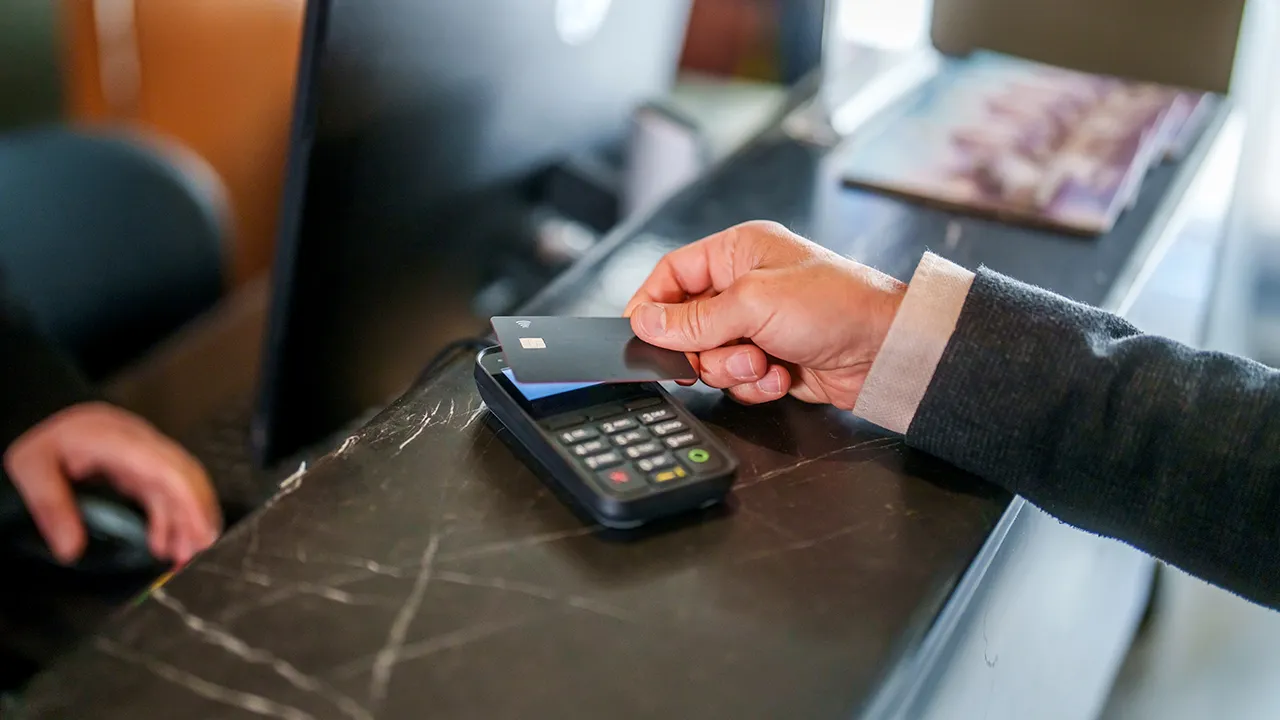
Tap-to-pay functionality has become one of my most appreciated modern conveniences. I use it quite often—so much so that there are times I don’t even need to reach for my physical wallet since contactless payments are available at so many locations.
There’s also a security benefit. Mobile wallets can use methods like tokenization or virtual card numbers, which means your actual card number doesn’t need to be directly transmitted to the merchant during a transaction.
This convenience makes it particularly irritating to see tap-to-pay being exploited through charity scams. Scammers are managing to take a technology meant to streamline payments and use it during a moment of distraction, turning what should be a small donation into a much larger charge.
You might think you’re donating $5 or $20 to a great cause, only to later find out that hundreds, or even thousands, of dollars have vanished from your account. Here’s a closer look at how this scam operates and what steps you can take to protect your finances.
How the tap-to-pay charity scam works
The scenario can seem completely normal. You’re walking out of a store or traversing a public event when someone approaches you, claiming to raise funds for a youth organization, school fund, or another cause. They ask for a modest donation. You might say yes to $5 or even $20, and then they inform you that they can accept tap-to-pay donations. This is when your awareness needs to be heightened.
The scammer enters a different amount
In one variation of the scheme, the solicitor inputs a significantly larger amount into their device before you make your tap. You think you’re approving $20 when the screen might actually display $2,000. If you don’t check that amount carefully, you could inadvertently authorize that larger payment. Police in Brentwood issued a warning about a similar situation where solicitors approached shoppers asking for small donations only for victims to be charged much more than anticipated.
Some victims lost thousands of dollars
The potential losses can escalate quickly. The Washington state attorney general recently issued a warning after receiving multiple reports of solicitors near the waterfront in Seattle. In one incident, a person agreed to donate $15 but was later hit with a $4,800 charge. Another individual who pledged $20 found their account charged nearly $5,000. These examples highlight the importance of not considering the final tap as a mere formality.
Never hand a stranger your unlocked phone
Another crucial point to remember is that if a stranger claims the transaction failed and asks to borrow your phone, you should cancel the transaction immediately. A scammer doesn’t need to physically handle your phone for their inflated payment scheme to be effective. Handing over an unlocked phone can lead to bigger security risks as it may allow access to emails, messages, payment apps, and financial data. I personally wouldn’t give my unlocked phone to anyone during a financial transaction.
Why tap-to-pay security may not stop this scam
Tapping to pay is generally a secure method for legitimate transactions. The flaw lies in what you agree to approve. If a scammer shows $2,000 on the screen and you validate that purchase, the payment system registers it as authorized.
Essentially, the scam relies on you skipping a vital step: checking the displayed amount before tapping. Since contactless payments have become so habitual, the process often feels almost automatic—take out the phone, authenticate, tap, and walk away. This is the gap a scammer exploits.
How to protect yourself from a tap-to-pay charity scam
There’s no need to stop using the tap-to-pay feature altogether. I certainly won’t be doing that. Instead, consider altering how you approach unexpected payment requests.
Keep your phone in your hands
Don’t let a stranger use your unlocked phone to complete or troubleshoot a payment. If something goes awry with a transaction, just cancel it and move on. When it comes to your financial information, you should maintain control of your device from start to finish.
Read the amount before you tap
This habit might be the most crucial one to adopt. Take a moment to carefully check the amount displayed on the merchant’s device before your phone or card goes anywhere near the reader. If you agreed to donate $10, ensure the screen reflects that amount. The FTC recommends reviewing financial statements after donations to confirm you were only charged the intended amount.
Avoid high-pressure donations
A genuine cause will still be there a few minutes later. If anyone insists you donate immediately, I would suggest walking away. Scammers often count on pressure tactics to keep you from thinking critically about the request. The FTC advises against allowing fundraisers to rush you into making donations.
Research the charity yourself
Ask for the organization’s name, then independently look it up. Don’t trust any website, QR code, or social media account handed to you by the solicitor. Search for the charity on your own, check if it’s registered, look for independent reviews, and confirm how they ask for donations. The FTC emphasizes researching unfamiliar charities before giving money.
Use the charity’s official donation channel
If the cause seems worthwhile, you still have the option to donate. Make sure to visit the organization’s official website after verifying its authenticity. This gives you a chance to confirm where your money is going without someone pressing you from behind to tap.
Turn on bank and card alerts
I find account alerts especially useful because they can notify you as soon as something happens with your funds. Activate notifications for card purchases and withdrawals, as well as alerts for transfers or other significant account changes. If you meant to donate $20 but see an alert for $2,000 instead, you can quickly reach out to your bank.
Lock down your payment and banking apps
Review the security settings on apps like Venmo, Cash App, PayPal, and your banking app. Enable Face ID, fingerprint authentication, or a unique PIN when such features are available. This acts as an additional safeguard if someone gains access to your unlocked device.
What to do if you already fell for the scam
If you notice an inflated charge or realize you approved a higher amount than intended, act swiftly. The sooner you respond, the sooner your bank can provide guidance on the options available.
1) Contact your bank or card issuer immediately
Reach out to the bank or card issuer linked to the transaction. Explain what occurred, specifying the amount you agreed to pay versus what was actually charged. Inquire if the transaction can be halted, disputed, or reversed. If you can, lock the affected card using your banking app while you investigate. Brentwood police recommend contacting your bank or card issuer right away if you suspect you’ve been a victim of this scam.
2) Save evidence of what happened
Take screenshots of the transaction along with any payment confirmations. Jot down where the encounter took place and approximate timing. Make note of the merchant’s name associated with the charge. This information can assist your bank or law enforcement in their investigations.
3) Check every financial account on your phone
If the scammer had access to your unlocked phone, review all financial apps on it. Look for unfamiliar transfers or purchases. Check if anyone altered your email address, phone number, or other account details. Keep monitoring those accounts over the following days as suspicious activity may appear later.
4) Change passwords if your phone left your hands
If a stranger had access to your unlocked device, prioritize changing passwords for sensitive accounts that might have been compromised. Start with your primary email address, as criminals can use that to reset passwords for other services. Then secure your banking and payment accounts. A password manager can help you generate and store strong, unique passwords for each account and enable multifactor authentication where it’s available.
5) Strengthen your phone security
Ensure your phone requires Face ID, fingerprint authentication, or a robust passcode. Protect sensitive apps when your device provides that option. The aim is to prevent someone from turning mere seconds with your unlocked phone into access to your financial details.
6) Use strong antivirus software
While antivirus software cannot reverse an inflated tap-to-pay charge, it becomes pertinent if the scammer managed to get you to click on a link or visit a malicious site. Good antivirus protection can identify harmful software and warn you about risky links used in subsequent scams. I suggest utilizing trusted security software across your devices and keeping it updated.
7) Reduce the personal information scammers can find
Fraudsters often attempt to come back for a second scam. If they obtain your name, phone number, or any personal details, they can enhance their next attempt using that information. Data brokers and people-search sites can reveal much about you. You can eliminate some of this information on your own, but it will take time, and information might resurface. A data removal service can simplify many of those requests and continuously monitor for your information. While it can’t remove details criminals already possess, it can help shrink your online footprint and give scammers less material to exploit.
8) Consider identity theft protection
If someone accessed sensitive information on your phone, it might be wise to have additional monitoring for signs of fraud. Identity theft protection services can keep an eye out for unusual activity and alert you when certain personal information appears inappropriately. Some services also offer recovery assistance if your identity is misused, which can be critical if you think the incident exposed more than just a payment card.
9) Consider freezing your credit
A fraudulent tap-to-pay charge on its own doesn’t mean someone can open credit under your name. However, if a scammer also gains access to sensitive personal information, then you might want to consider placing a credit freeze with the major bureaus. A freeze will hinder criminals from opening new credit accounts in your name.
10) Report the scam
If you lost money, make sure to report the incident. Contact local law enforcement when necessary, especially if the amount is significant or if the same solicitors seem to be targeting others. You can also inform the Federal Trade Commission about the fraud.
The safest way to donate with your phone
I still appreciate mobile wallets and intend to continue using tap-to-pay options, as they offer us both convenience and valuable protection. However, I’ve decided to change how I respond to someone asking for a spontaneous donation. I want to verify precisely who will receive my money before I authorize anything.
If I believe the cause is worthy, I can always look up the organization later and contribute directly through its verified website. This method allows me to take my time and ensure my donation reaches the intended beneficiaries.
Kurt’s key takeaways
Tap-to-pay is one of my preferred ways to pay. I enjoy its speed, and I appreciate the added security that mobile wallets provide. Nevertheless, we cannot rely solely on technology to protect every transaction we personally confirm. This is precisely what renders this scam so effective. Many of us have grown overly accustomed to tapping without actively considering the final transaction screen. It’s time for that habit to change. Always check the amount before you tap. If a stranger requests a donation, take the time to verify the organization first. And if anyone asks to borrow your unlocked phone during the process, my answer would be a firm no. Your generosity should support the cause you choose, not a scammer exploiting your distraction.
Would you still tap your phone to make a donation to someone approaching you in public after learning how easily a small gesture could turn into a significant charge? Feel free to share your thoughts.