A Booming Economy Still Too Dependent on Imported Technology
The American economy is currently seeing a remarkable surge in business investments. Recent GDP figures underline just how significant this trend has become.
Yet, there’s a nagging issue overshadowing this growth: the ongoing dependence on imports stemming from years of U.S. oversight amidst the success of economically nationalist policies from some of our trading partners.
On Thursday, the Commerce Department revealed that the economy expanded at a 3.4 percent annualized rate in the third quarter, up from 2.2 percent in the previous quarter, and surpassing expectations from economists.
This growth can largely be credited to business investment. Nonresidential fixed investment increased at an annualized rate of 12.7 percent, adding 1.78 percentage points to the GDP. Notably, investment in equipment soared at a rate of 20.9 percent, contributing 1.16 points alone.
What stands out the most are the figures related to information-processing equipment. Investments in computers and peripherals alone added 0.72 percentage point to GDP growth, with other information-processing equipment adding another 0.14 point. So, almost nine-tenths of a percentage point of growth can be traced back to business investment in information technology.
It’s clear what’s driving this demand, right? The Super Intelligence boom is fueling a substantial need for data centers, servers, advanced semiconductors, and the software that powers these systems.
However, the unfortunate reality is that much of the gear essential for building this infrastructure is not manufactured in the U.S.
The Great Import Leakage
The third-quarter GDP report disclosed another extraordinary statistic. Net exports, calculated as exports minus imports, detracted 3.32 percentage points from economic growth.
As noted by Harvard economist Jason Furman, this marks the third-largest negative impact from net exports since the inception of the Commerce Department’s quarterly GDP records dating to 1947. The only larger negative contributions occurred in the first quarter of 2015 during a surge of imports before tariffs imposed by President Trump and back in the fourth quarter of 1947.
The reason imports detract from GDP is that they are considered foreign production included in American spending and investment metrics. This subtraction ensures that only U.S.-made goods are counted in national output, avoiding a scenario where foreign products inflate the GDP figures.
But this is what makes these statistics telling. While American companies are laying the groundwork for future infrastructure, foreign manufacturers are supplying much of the necessary equipment. We fail to produce our own foundational resources.
Imports surged at a 19.7 percent annualized rate in the third quarter, with goods imports alone climbing at a 26.4 percent pace. What are we bringing in? Well, it’s largely high-tech items essential for the AI boom.
The Census Bureau indicated that imports of capital goods increased by $14.4 billion in July, with computers making up $6.9 billion of this rise, and accessories and semiconductors adding $6.6 billion and $1.2 billion, respectively. Another $6.2 billion spike in capital-goods imports in August brought the total to a record $146.4 billion. And preliminary figures for September indicated a further increase of $10.9 billion, hitting a remarkable $157.4 billion—a remarkable 77.2 percent increase from the previous September.
Importantly, many advanced semiconductors utilized in artificial intelligence arrive in the U.S. already incorporated in servers and other devices. This means they’re counted among computer imports rather than as semiconductors. So, one must sift through various data lines to fully grasp the extent of our reliance on imports.
A study released by the Federal Reserve in July estimated that about 90 percent of the equipment required in high-tech sectors is sourced from abroad, with production primarily concentrated in East Asia. The researchers expected that the AI boom would lead to a significant uptick in imports, which is indeed what we are witnessing.
How America Lost an Industry It Invented
So, why are we so heavily reliant on imported goods? After all, the semiconductor industry was innovated in the United States. Our engineers were the ones who created the transistor and pioneered integrated circuits. The innovations that enabled modern computing and currently underpin the Super Intelligence boom predominantly stem from American ingenuity.
But what exactly went wrong? Back in 1990, the U.S. held 37 percent of global semiconductor manufacturing capacity. By 2000, that share dropped to about 19 percent. And shockingly, by 2022, it had plummeted to only 10 percent.
How did we fall short in meeting our own semiconductor needs, let alone producing enough for global demand?
The decline narrative traces back to the shift of consumer electronics manufacturing to Asia throughout the 1970s and 1980s. American firms had been at the forefront of many technologies used in radios, televisions, and computers, but production increasingly shifted overseas. Consequently, the demand for semiconductor production also migrated as electronics manufacturing moved abroad.
This wasn’t solely about Japanese companies edging out their American competitors. Japanese workers didn’t possess any innate advantages over their American counterparts when it came to semiconductor production. It wasn’t a simple case of some favorable “comparative advantage” outlined in academic economics.
No, it revolved around economic policy.
Japan has historically implemented nationalist economic policies that have actively fostered the growth of its semiconductor industry. In 1976, its Ministry of International Trade and Industry initiated a collaborative research program involving major electronics manufacturers to expedite the development of advanced integrated circuits.
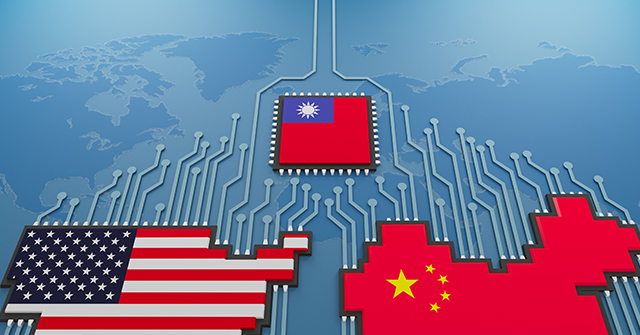
Similarly, Taiwan adopted its own nationalist industrial strategy, yielding even more pronounced effects. In 1987, Morris Chang, previously of Texas Instruments and at the helm of Taiwan’s government-supported Industrial Technology Research Institute, established the Taiwan Semiconductor Manufacturing Company (TSMC) with a groundbreaking business model. Rather than designing its own chips, TSMC focused on manufacturing chips created by other companies.
From its inception, TSMC was established with the involvement of the Taiwanese government and ITRI, receiving funding from the government, Philips, and private firms. The ITRI contributed technology, manufacturing facilities, and trained personnel. The Taiwanese government purposefully built an industry that would eventually become a global powerhouse and promoted a business model aimed at attracting manufacturing from the U.S.
Why didn’t we respond? Because Taiwan wasn’t opposing American economic policies; instead, it was collaborating with them.
Dating back to the 1960s, U.S. tariff regulations permitted companies to ship American-made components for assembly abroad and only incur duties on the added value overseas. In the 1970s, Pan Wen-yuan, a researcher at RCA, was advising Taiwan’s government on establishing an electronics industry, persuading officials to acquire proven technology rather than develop it independently. In 1974, the ITRI launched an electronics unit to pursue this goal, and in 1976, RCA licensed its chipmaking technology to ERSO and trained Taiwanese engineers in semiconductor production. The cost? A mere few million dollars—chicken feed for RCA. Those engineers later formed the backbone of Taiwan’s chip industry, leading to the emergence of TSMC in 1987.
In essence, RCA, a company initially formed through a collaboration between the U.S. Navy and General Electric to secure American radio dominance, inadvertently sowed the seeds for TSMC a mere decade later.
Fast forward twenty years, and Washington endorsed a global agreement to eliminate tariffs on a broad spectrum of information technology products, encompassing computers and semiconductors. American tax policy also encouraged foreign profit accumulation and offshore investments. Even the 2017 tax reform allowed a 10 percent return on foreign factories and equipment to escape the minimum tax on overseas profits, a provision finally removed by Congress in President Trump’s sweeping tax bill of 2025.
Why did American policies shift in this direction? Because it was incredibly lucrative for American businesses. U.S.-based firms accounted for 53.4 percent of global semiconductor sales last year, their highest percentage since 1984, despite much of their production occurring overseas. As public-choice theory suggests, government policies tend to favor those who reap direct benefits, even when such costs are distributed across a broader population.
And there was a Cold War to contend with, partly by promoting prosperity among our allies. It hardly mattered how Americans voted. Leadership from both political parties supported the status quo, even after the reasoning from the Cold War waned. All our post-Cold War presidents, regardless of their party affiliation—Bush, Clinton, Dole, Gore, McCain, Obama, Romney—were proponents of offshoring until Donald J. Trump came along.
In summary, jobs and factories didn’t vanish because Americans refused to work or lacked the ability to compete. Our regulatory environment pushed them away, while our trade partners’ rules drew them in.
The Price of the Great Offshoring
Interestingly, the offshoring of chip manufacturing was celebrated as a sign of economic advancement. For years, the consensus held that the U.S. could excel at technology design and software development while outsourcing actual manufacturing to other nations.
The critical flaw in this approach? Manufacturing itself generates knowledge. Companies enhance products by tackling the actual process of making them. Factories drive demand for specialized suppliers, skilled labor, and the next generation of manufacturing tools.
A 2025 essay by Kenneth Flamm and William Bonvillian highlighted how modern semiconductor fabrication benefits from significant economies of scale. TSMC can distribute the billions needed to establish advanced factories across chips developed by numerous clients. Their factories also leverage the accumulated know-how gained from large-scale production, leading to better efficiency and cost reductions over time.
There’s a well-recognized economic principle regarding this. Economists refer to it as agglomeration—industries tend to enhance productivity as they cluster geographically. Paul Krugman’s foundational work in economic geography demonstrated how manufacturing concentration can become mutually reinforcing. Factories attract specialized suppliers and workers, thus making it cheaper and more efficient for new factories to establish themselves nearby, drawing in even more specialized labor. Rinse and repeat.
Put simply, the advantages we see today arose from decades of industrial policies that were put in place in the past. Taiwan’s lower production costs are the result of years of accumulated expertise, investment, and industrial clustering. Treating those benefits as inherent characteristics of the economic landscape is akin to treating past governmental interventions as evidence against future action.
The outcome has been a vicious cycle for American production and a virtuous one for Taiwan. What began as a shift in industry became an established competitive edge.
And this takes us back to the massive imports of servers and computers revealed in the recent trade statistics. Even as the U.S. starts to rebuild its semiconductor manufacturing, much of the equipment that includes those chips is still produced overseas.
Rebuilding chip factories is crucial. However, fully reaping the benefits of the AI investment boom will also mean reconstructing more of the surrounding manufacturing ecosystem.
The Good News: America Is Beginning to Rebuild
So, are we doomed? Perhaps not. Under President Trump, the U.S. is finally harnessing its economic power to reverse the long-term decline of American tech manufacturing. TSMC is expanding its operations in Arizona, Samsung is investing in fabrication in Taylor, Texas, Micron is boosting domestic memory chip production, and Texas Instruments is increasing their fabrication capacity in the U.S.
According to projections from the Semiconductor Industry Association and the Boston Consulting Group, American semiconductor manufacturing capacity is expected to nearly triple by 2032. The share of U.S. facilities in global fabrication is predicted to rise from about 10 percent to 14 percent, marking the first sustained increase in decades. Additionally, the U.S. share of global production for advanced logic chips is anticipated to climb from virtually zero in 2022 to 28 percent by 2032.
However, building factories is merely a part of the challenge. The notion that “if you build it, they will come” is a nice sentiment from a film, but it doesn’t hold in economic terms. Years of offshoring have also diminished the pool of specialized labor needed to construct and run these facilities. TSMC’s Arizona project has faced labor shortages for experienced workers skilled in advanced fabrication installation, necessitating the recruitment of personnel from Taiwan. Interestingly, those workers have expressed concerns about the state of U.S. public schooling for their children.
Still, there’s hope that this recovery could, over time, become self-reinforcing. New factories might lead to the development of suppliers, skilled workers, and technical expertise that make additional plants competitive. The economics of agglomeration and geographical concentration might shift back in our favor.
For now, the third-quarter GDP report serves as a reminder of how much work lies ahead.
The U.S. is experiencing one of the most significant technological investment surges in its history. Yet, a large portion of the equipment supporting our Super Intelligence boom still comes from countries that have spent recent decades building up manufacturing sectors we allowed—and, at times, encouraged—to fade away.