It’s Getting Harder for the Media to Hide America’s Manufacturing Boom
The revival of the American manufacturing sector was evident again in the Census Bureau’s release of durable goods data this week.
New orders have surged by 8.0 percent year-to-date through September. Core capital goods orders, excluding defense-related items and aircraft, are up 10.9 percent. Orders for primary metals increased by 16 percent, fabricated metal products by 8.8 percent, and machinery orders by 13.4 percent. Electronic equipment and appliance orders rose by 6.5 percent, and computer-related equipment orders saw a notable increase of 20.3 percent.
When looking at a broader time frame, durable goods orders have risen by 15.9 percent compared to the same period in 2024, which was President Biden’s last year in office. Core capital goods orders are up 13.9 percent as well. Even when these numbers are adjusted for inflation via the producer price index, there’s still a tangible increase of 6.4 percent since Biden’s final year.
This report indicates a substantial demand for American-made durable goods, and factories are actively responding. Shipments of durable goods increased by 8.5 percent, with core capital goods shipments up 8.8 percent and computer shipments experiencing an 18.8 percent rise.
Media Credibility in a Free Fall
However, you wouldn’t get this impression from media sources based in Washington. Politico characterized the factory resurgence as merely an “output bump,” while warning that manufacturing construction is in a “free fall.” In contrast, Axios described the manufacturing revival as “lopsided,” suggesting that traditional sectors are being left behind.
Both claims seem misguided.
Consider Politico’s take on construction:
“Economists claim that the idea tariffs are fueling a U.S. manufacturing boom is a surreal fantasy… U.S. manufacturing is seeing an output boost… However, an uptick in manufacturing activity only reveals part of the picture. Productivity is also increasing, allowing firms to enhance output while using the same resources, which does not necessarily indicate a surge in manufacturing investments.”
According to the St. Louis Fed, spending on manufacturing construction projects has been declining since late 2024, dropping from an annual rate of around $250 billion in November 2024 to $170 billion in August—the lowest level since the end of 2022.
That paints a grim picture, but it’s not quite accurate. Even after this decline, manufacturers were still investing $168 billion annually in construction as of August, which is more than double the $81 billion pace recorded in August 2019. After adjusting for inflation, this still represents a significant increase of 37.5 percent since August 2019. That hardly signifies a true collapse in construction.
Moreover, Politico overlooks that substantial government investments in technology and Green New Deal manufacturing projects under the Biden administration have played a crucial role in this surge. The CHIPS Act, Inflation Reduction Act, and infrastructure legislation have spurred an unprecedented boom in constructing semiconductor and battery factories. These subsidies have shifted spending forward from future years.
Data from the Census Bureau shows that this pull-forward effect primarily accounts for most of the decline in construction spending. The data reveals that investments in building computer, electronics, and electrical equipment factories have plummeted by approximately $72.5 billion since September 2024, representing nearly 90 percent of the total decline. In other words, the alleged construction collapse is largely concentrated in sectors that had initially benefited from the subsidy-driven boom.
It’s reasonable to expect that the intense pace of construction couldn’t be maintained forever. The recent numbers are notable, particularly because much of the spending was brought forward into the 2022-24 timeframe. Additionally, spending on facilities for fabricated metals, food and beverages, and transportation equipment remains above 2019 levels. Interestingly, construction of chemical plants is actually up 5.6 percent in the past year.
Data Centers, Investment, and Productivity
An important aspect of America’s industrial boom is taking place outside traditional manufacturing categories. Construction spending on data centers falls under “office construction” instead of “manufacturing,” even though data centers resemble factories more than conventional office spaces. In August, spending on data center construction hit an annualized $85 billion, sharply rising from under $9 billion in August 2019. When combined with factory investments, total construction spending jumps to about $253 billion annually—almost triple the pre-pandemic combined amount in nominal dollars.
However, construction is just a segment of industrial investment. Businesses are also allocating funds toward machinery and equipment. The Bureau of Economic Analysis reports that real investment in industrial equipment increased at an impressive annualized rate of 27 percent in the second quarter, following a 5.2 percent rise in the first quarter. This kind of acceleration is unexpected for an economy purportedly faltering in terms of manufacturing investment.
One curious aspect of the Politico article is its skeptical view toward productivity. It notes the uptick in manufacturing productivity but uses this to downplay output increases. Apparently, producing more goods with the same resources has turned into something suspicious.
This is, in fact, the essence of productivity growth and how economies elevate living standards. Factories that generate more with fewer workers can provide higher wages, lower prices, and expand production without continuously increasing their workforce. A manufacturing renaissance alongside rising productivity should be celebrated, especially when considering a slowly growing or shrinking labor force.
Traditional Manufacturing Is Booming Too
The Axios article is similarly flawed. It argues that the manufacturing renaissance, particularly in terms of employment, has skewed towards “advanced manufacturing” while traditional industries are supposedly lagging. Alan Tonelson notes that this is an odd assessment as economists have long argued that labor-intensive sectors like apparel belong in low-wage countries. Now, their failure to lead the manufacturing revival in the U.S. is viewed as a failure.
Axios referenced a study by Gad Levanon from the Burning Glass Institute, which showed that while American manufacturers added 40,000 jobs over the year ending in September, the increases were concentrated in advanced manufacturing areas such as chemicals, machinery, computers, and electronics. Those branches, which make up only 38 percent of manufacturing employment, created 56,000 jobs, while the remainder of the manufacturing sector lost 16,000 jobs. An ISM survey also indicated that although five of the six largest manufacturing industries noted rising orders in September, only two reported increased employment.
However, splitting advanced and traditional manufacturing obscures an important detail: numerous traditional manufacturing sectors are indeed adding jobs. In the past year, fabricated metals have gained 24,400 jobs, electrical equipment added 17,300, and primary metals saw an increase of 5,700.
That’s 47,400 jobs across just three traditional manufacturing sectors—exceeding the net 40,000 jobs added across the entire manufacturing landscape. It seems these traditional manufacturing sectors labeled as lagging did not get the memo.
The reality is, various nondurable manufacturers have downsized their workforces. Think of sectors like paper products, apparel, printing, and food manufacturing. It’s likely that some of these reductions are not voluntary but stem from deportations or competition from growing industries that are attracting workers away.
In terms of output, traditional manufacturing is also on the rise. Using data from the Federal Reserve’s industrial production figures, overall output in traditional manufacturing saw a 0.5 percent increase over the past year. In particular, there was a 2.4 percent growth in traditional durable manufacturing—what most people refer to when discussing the resurgence of American manufacturing. This was balanced against a 1 percent drop in nondurables, which likely accounts for some of the job reductions. Advanced manufacturing output increased by 2.6 percent—barely a higher rate than traditional durables.
Moreover, gains in traditional durables come from multiple industries. Fabricated metals production rose by 3.4 percent, primary metals by 1.3 percent, and electrical equipment by 5.4 percent. Machinery production surged even further, up by 6.9 percent.
It’s not a shortcoming of Trump’s economic policies—like tariffs, tax cuts, deregulation, and energy production—that apparel and food processing haven’t emerged as major growth engines. Their failure to add jobs shouldn’t overshadow the vibrant resurgence in sectors producing metals, machinery, and electrical equipment.
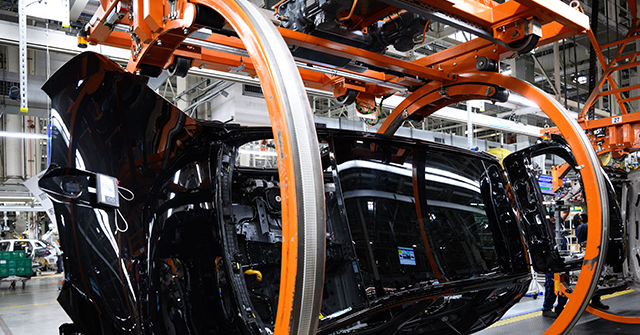
American manufacturers are constructing factories at historically high rates, investing more in industrial equipment, swiftly processing orders, ramping up production, and hiring in industries that many thought were past their prime.
The real distortion lies in the skewed portrayal of this thriving boom by media outlets like Politico and Axios.