Gold Prices Experience Volatility Amid Economic Data
Gold prices displayed significant volatility throughout the past week. A notable rebound early on, fueled by softer yields, a weakening U.S. dollar, and comments from the Federal Reserve (Fed) that seemed less aggressive, was mostly reversed on Friday. This occurred in response to stronger-than-expected U.S. payroll data, which rekindled expectations for a rate hike in September.
The week began with spot gold priced at $4,439.15 per ounce on Sunday evening. Initially, the metal faced selling pressure as traders were still processing last week’s sharp drop, high Treasury yields, and persistent inflation worries, especially those linked to oil prices and the situation between the U.S. and Iran. The decline accelerated on Tuesday, reaching a low of $4,282.61 per ounce before buyers stepped in.
Gold prices bounced back on Wednesday and surged on Thursday, aided by softer labor data from the private sector, easing Treasury yields, and comments from Fed Governor Christopher Waller that indicated a less hawkish stance. This led spot prices to recover above $4,500, achieving a weekly high of $4,511.08 per ounce on Thursday.
However, this upward momentum faltered on Friday morning as the August nonfarm payroll report revealed the U.S. added 162,000 jobs—much higher than anticipated—and maintained an unemployment rate of 4.1%. This upbeat labor report boosted the U.S. dollar and short-term Treasury yields, leading to renewed expectations of a rate hike. Consequently, gold prices plummeted, reaching as low as $4,365.57 per ounce shortly after the news was released.
Although spot gold recovered some losses after the payroll report, it couldn’t regain the $4,500 mark, trading at $4,432.33 per ounce by Friday afternoon, which left it slightly down for the week.
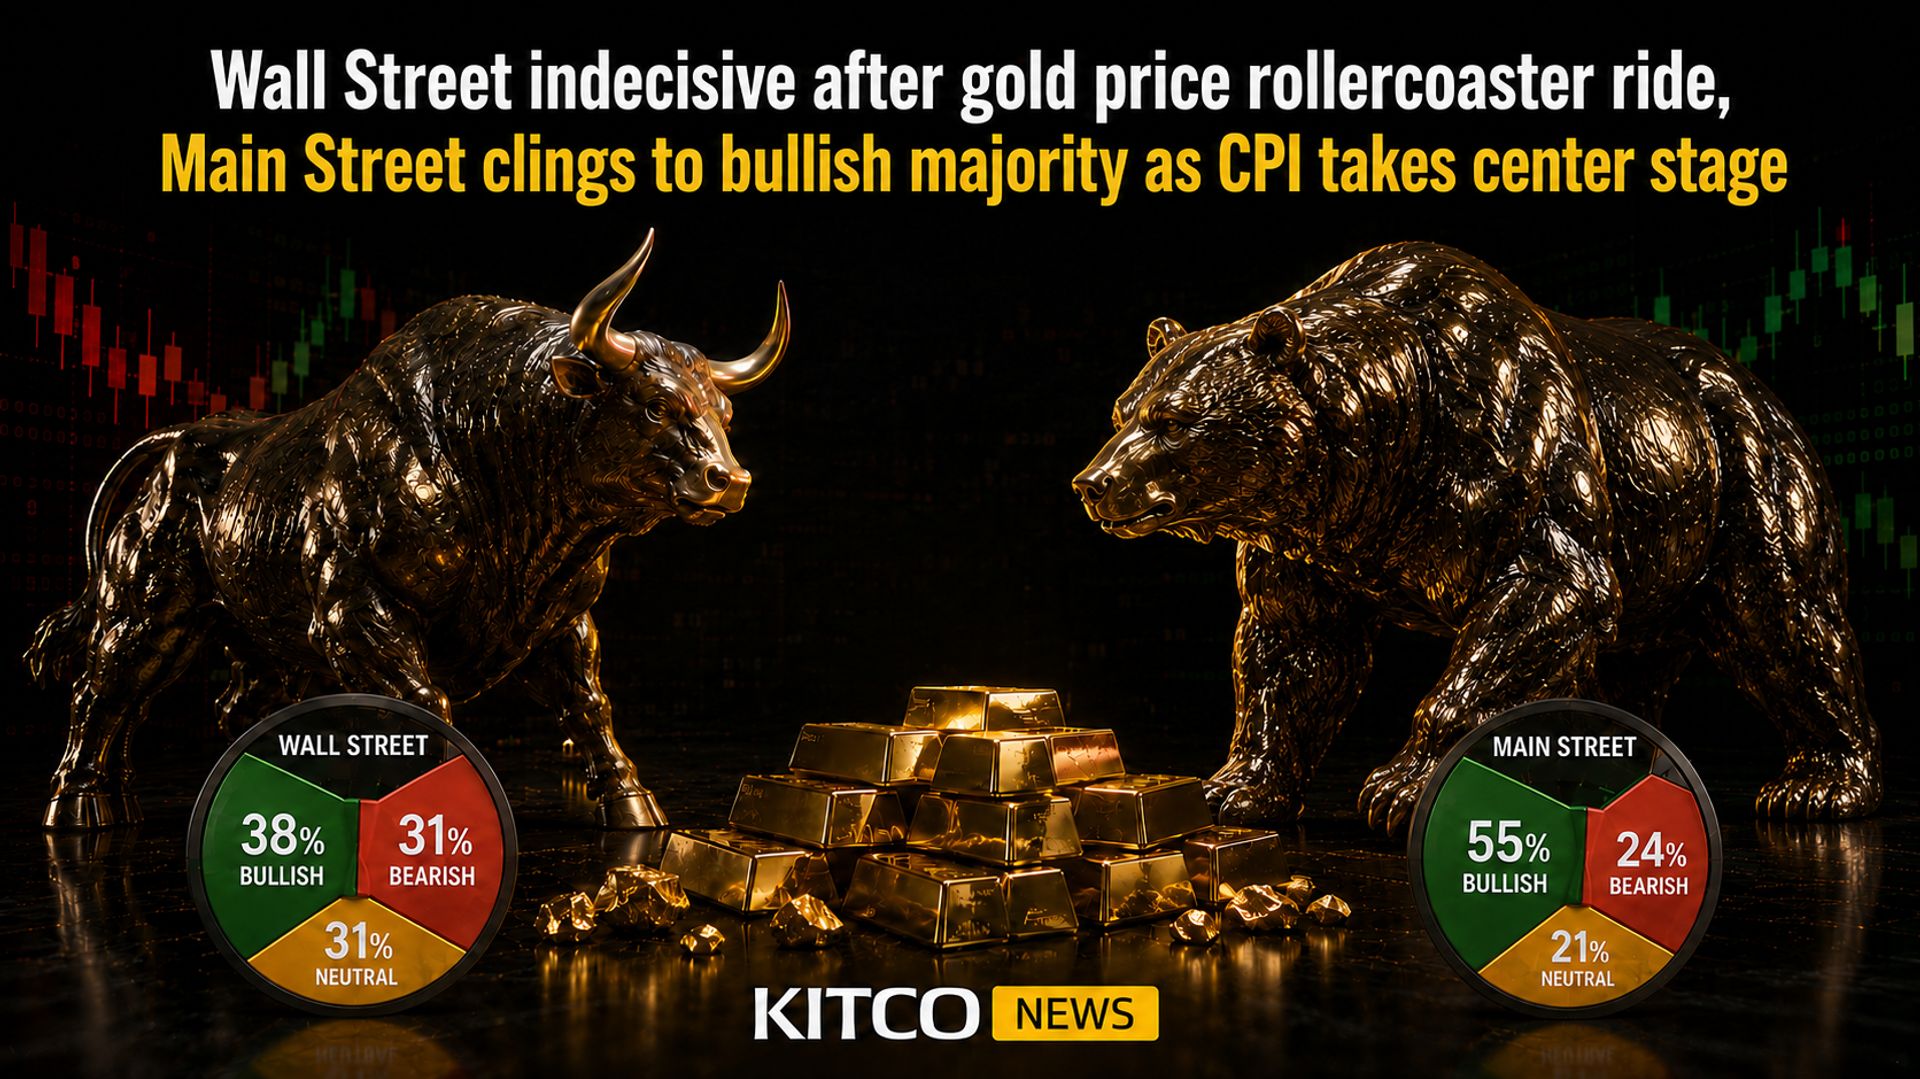
The latest Kitco News Weekly Gold Survey indicated a divided sentiment on Wall Street. Analysts were split among bulls, bears, and those unsure about gold’s direction. Main Street also showed a reduced bullish outlook after the recent pullback.
“Gold looked quite poor at the end of last week and experienced sharp downturns until midweek,” commented Marc Chandler, managing director at Bannockburn Global Forex. “The low was around $4,283. It briefly surged above $4,500 before facing selling pressure again. The technical outlook appears weak, and if it breaks below the $4,280 mark, it could signal further declines toward $4,200.”
“I see it going down,” noted Darin Newsom, senior market analyst at Barchart.com. “How much further will depend on Friday’s sell-off post-jobs report. The August job figure of 162,000 exceeded pre-report expectations, which presents a more optimistic view of the U.S. economy, but I anticipate that this figure will be revised downward in the coming months, so its long-term implications are questionable.”
Meanwhile, Adrian Day, president of Adrian Day Asset Management, expressed a more neutral stance. He believes gold will likely remain range-bound until the Federal Reserve’s interest rate decision in less than two weeks. Though a strong jobs report could bolster the case for a rate hike, he pointed out that the Fed tends to avoid significant policy changes close to elections.
Rich Checkan, president and COO of Asset Strategies International, offered a contrary view, arguing that despite the temporary challenges gold faced after the jobs data, the overall long-term outlook remains positive. “Concerns about interest rate hikes are present, but the debt situation is growing as well. Gold’s trajectory is upward,” he stated.
Kevin Grady, president of Phoenix Futures and Options, emphasized the overwhelming focus on interest rates at present. “Market sentiment is completely tied to interest rate discussions. The nonfarm payrolls report was impressive, which might indicate a shift toward higher rates moving forward,” he explained.
Looking ahead, analysts varied in their expectations. The upcoming economic news calendar is expected to be thin due to the holiday week, but critical inflation data will remain in the spotlight along with manufacturing and services sector surveys, plus two central bank rate announcements.
The European Central Bank will announce its monetary policy on Thursday, anticipated to include a rate hike due to rising energy prices impacting consumer inflation in the Eurozone. That same morning will also see the release of U.S. Producer Price Index (PPI) and existing home sales data for August. The following day will bring the anticipated August Consumer Price Index (CPI) report and preliminary University of Michigan Consumer Sentiment findings for September.
David Morrison, senior market analyst at Trade Nation, commented he is bearish in the near term, predicting a test of support around $4,200. However, he noted that gold had previously struggled to surpass the $3,500 mark just a year ago, pointing out the inherent volatility in market sentiment tied to interest rates.
With Friday’s robust payroll data, the focus on upcoming economic reports becomes even more crucial. Adam Button, head of currency strategy at investingLive, remarked that the market’s attention is singularly focused on September’s Federal Open Market Committee meeting, with investors uncertain about how the Federal Reserve might respond to evolving economic conditions.
As observed, gold prices have displayed considerable volatility, and observers expect this trend to continue in the short term as market participants grapple with shifting expectations regarding U.S. interest rates.