What to Do After Identity Theft: How Restoration Works
Recovering from identity theft usually takes more than a single phone call. You may need to secure accounts, document fraudulent activity and work with several organizations to correct inaccurate records.
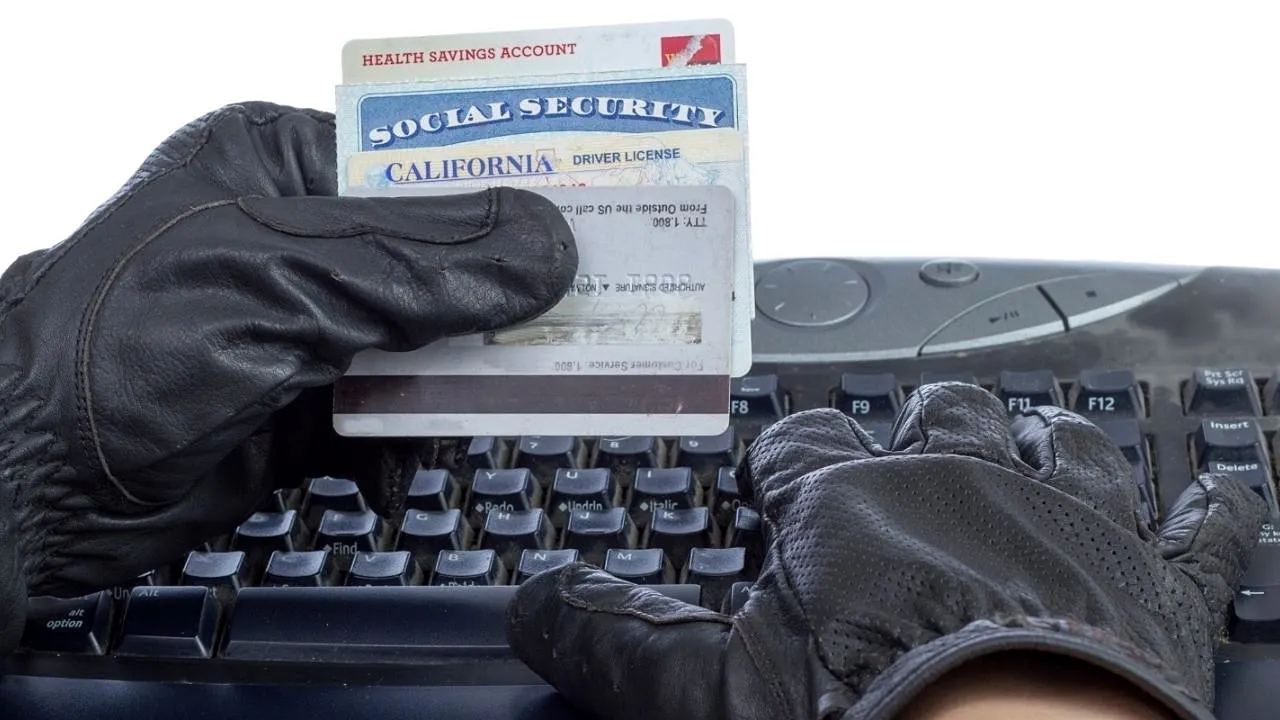
“Identity restoration” can sound like a lot of jargon until someone opens a credit card in your name, takes over your bank account or uses your personal information to get medical care. Then come the unfamiliar charges, forms and phone calls—and each company may have its own process.
Understanding the steps involved can make the experience easier to manage. The exact process depends on the type of fraud, but it generally starts with figuring out what happened and limiting any further damage.
Secure your accounts and document what happened
A restoration specialist may begin by asking when you noticed suspicious activity, which accounts were affected and whether money or personal information was lost. Those details help distinguish one kind of identity theft from another. A new credit card opened in your name, for instance, calls for a different response than a stolen phone number or altered medical records.
Before you work through the paperwork, try to prevent further harm. Contact your bank, lock a compromised card, change passwords or secure your mobile account, depending on what happened. If your email account was accessed, make securing it a priority; criminals may use it to reset passwords elsewhere. You can also consider placing a fraud alert or credit freeze. Neither will undo fraud that has already occurred, but both may help prevent someone from opening new credit accounts in your name.
It can be exhausting to explain the same situation every time you call a different company. Keep a case file with dates, statements, confirmation numbers, correspondence and the names of people you spoke with. Note what each organization said it would do and when you should expect an update. This record is especially useful when several issues overlap—for example, if a bank closes an account but a fraudulent balance remains on your credit report.
Store your records securely, and don’t send sensitive documents through an email address or link unless you’ve verified it belongs to the organization you’re contacting.
Work with the organizations involved
Depending on the circumstances, you may need to contact banks, creditors, credit bureaus, mobile carriers, healthcare providers or government agencies. Their procedures differ. A bank might ask for a fraud affidavit, while a credit bureau may require an identity theft report before it blocks fraudulent information.
A restoration specialist can help explain what each organization requires and, in some cases, coordinate communications or contact institutions on your behalf. You may still need to verify your identity, provide documents or authorize specific actions. Assistance can help you navigate the process, but the institutions involved are responsible for reviewing claims and correcting their records.
Once you’ve secured your accounts and identified who needs to be contacted, the next step is correcting the damage. If someone opened a fraudulent credit account, you may need to dispute it with both the creditor and the credit bureaus. The Federal Trade Commission recommends reporting identity theft through IdentityTheft.gov, which provides an FTC Identity Theft Report and a personalized recovery plan. The report may also help you exercise rights such as asking credit bureaus to block information caused by identity theft.
Medical identity theft may require contacting healthcare providers and insurers to correct inaccurate records. Tax identity theft generally involves working directly with the IRS. Keep copies of what you submit, and ask for written confirmation when an issue is resolved.
Follow up and keep checking for new activity
Recovery rarely happens all at once. Your bank might reverse a charge while a credit bureau is still investigating a related account. A mobile carrier may restore your number, but you’ll still want to improve account security to reduce the chance of another takeover.
Set reminders for promised responses and continue reviewing your statements, accounts and credit reports. You can get free weekly access to your credit reports through AnnualCreditReport.com. Even after one problem is resolved, new suspicious activity may appear if someone continues trying to use your stolen information.
The right steps depend on the type of fraud. New-account fraud often involves creditors and credit bureaus. A bank-account takeover calls for quick contact with your financial institution, while medical identity theft may require corrections to treatment or billing records. Tax and government-benefit fraud have their own reporting processes. If you were persuaded to authorize a payment, your options may also differ from those for an unauthorized transaction. A credit freeze can help guard against new credit accounts, for example, but it won’t fix a medical record or recover money sent to a scammer.
It may help to track progress one action at a time. Have you secured the affected account? Reported the charge? Received confirmation that a credit bureau has your dispute? It’s not a quick fix, but each completed step moves the case along. If a company misses a deadline or gives you conflicting information, your notes can help you explain what’s happened without starting from the beginning.
When professional help may be useful
Before speaking with a fraud department or restoration specialist, gather any suspicious statements, letters, alerts or emails. You may be asked for identification, an FTC Identity Theft Report or written permission for someone to assist with your case. Verify that you’re dealing with the legitimate organization before sharing personal information, and ask why a document is needed and how it will be handled.
Managing several disputes and follow-up calls can become overwhelming. Some identity protection services provide access to restoration specialists who can help organize documents, explain next steps and assist with communications. Other services may monitor certain personal information, credit reports or financial accounts and send alerts about activity that appears suspicious.
Monitoring has limits: no service can detect every kind of fraud, and restoration help can’t guarantee that every dispute will be resolved in your favor. Features also vary by provider and plan, so check what’s included before signing up.
Some services offer tools to review merchants or websites that may have your payment information saved, monitor eligible financial accounts for unusual transactions, or request removal of personal details from certain data broker sites. These tools can be useful, but they can’t confirm every instance of card theft, catch every suspicious transaction or erase information from every website. Certain plans may also offer reimbursement for eligible losses or expenses, subject to limits and exclusions. Read the terms carefully, and don’t assume a benefit will cover money sent to a scammer.
Discovering identity theft is often only the start. The work that follows—securing accounts, correcting records and getting answers from different organizations—can take time. Begin by protecting the accounts you still control, keep a clear record of what you’ve done and use the FTC’s free recovery tools. If you need more support, a service with restoration specialists may help you stay organized. It won’t make the problem disappear overnight, but having help can make a complicated process more manageable.