Retirement Budget Traps for Baby Boomers
Budgets for retirement usually don’t get off track due to a single extravagant purchase. More often, it’s inflation that complicates the calculations behind everyday decisions—like how to spend a Social Security increase, whether to keep the same Medicare plan, or if one’s utility bill will remain constant. The silver lining is that identifying these missteps becomes simpler once they’re recognized by name.
Let’s take a look at six budget traps that baby boomers frequently fall into.
1. Spending COLA First
The typical Social Security benefit jumped around $56 a month in 2026, according to the Social Security Administration. Meanwhile, the standard Medicare Part B premium saw a rise of $17.90 to reach $202.90. This means almost a third of the average cost-of-living adjustment (COLA) is absorbed before even considering groceries, utilities, or homeowners insurance.
“COLA is an adjustment for prices that have already increased in the past year,” explained Jason Gerstenberger, a retirement insurance broker. “It’s not additional money for new spending this year.”
2. Skipping the Check-Up
A study from eHealth found that nearly 46% of Americans delayed or skipped necessary medical care due to inflation. With so many expenses requiring cuts, postponing a medical check-up or follow-up appointment can seem like the easiest option.
“One mistake for boomers is to view healthcare expenses as just another household cost that can be minimized,” noted Whitney Stidom, eHealth’s VP. “While it might save money in the short term, putting off preventative care can lead to much larger health expenses down the line.”
3. Letting Perks Decide
Some Medicare Advantage plans offer eligible members a grocery allowance. However, problems arise when retirees prioritize this food benefit without first verifying if their prescriptions will be affordable under that same plan, as Mike Boshardy, the CEO of The Pocket Protector, pointed out.
“On the surface, the plan seems beneficial. You’re getting a monthly card worth $50 or $70, and that figure sticks in people’s minds. But if nobody assesses it against actual medication costs, that card can end up costing much more than it provides,” Boshardy cautioned.
4. Forgetting Home Insurance
Homeowners insurance is a cost that can significantly alter financial calculations, even after a mortgage is paid off.
In certain southern coastal regions, premiums shot up by 25% or more from 2019 to 2024, according to a report from the Government Accountability Office. Gerstenberger commented that home insurance rates have outstripped every other housing expense, including property taxes.
“Most homeowners insurance policies renew annually, and for many years, their pricing remained relatively stable,” he added. “Thus, many boomers don’t perceive this as a major threat to their financial stability.”
5. Charging the Basics
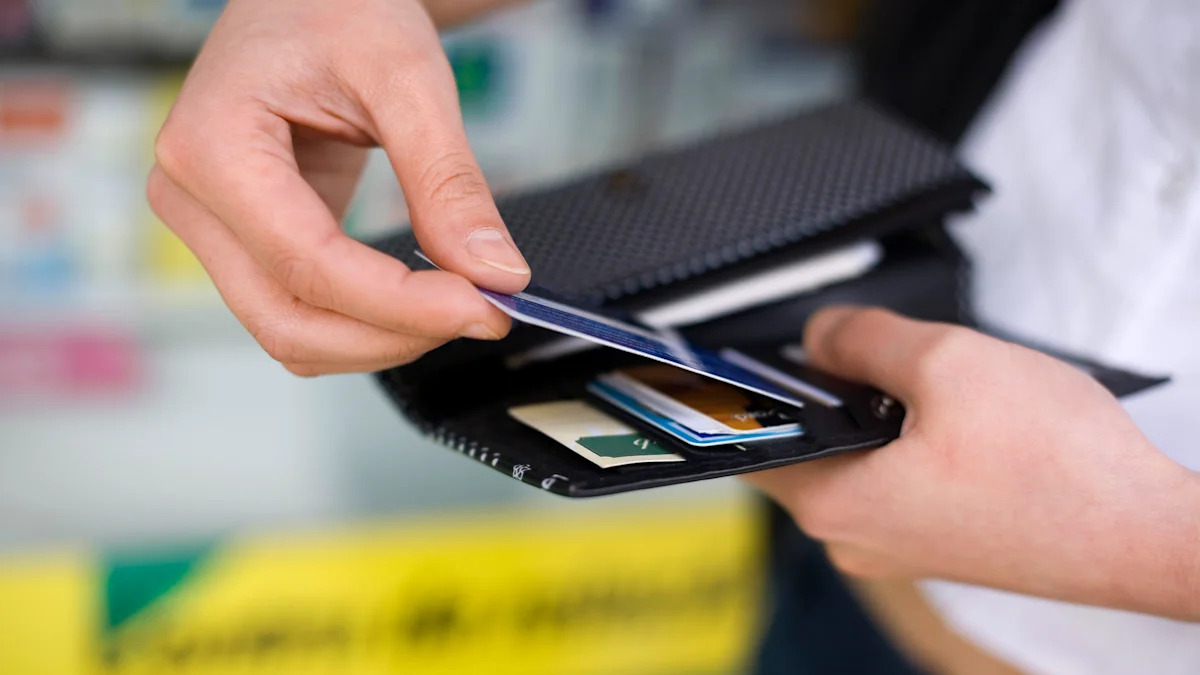
Monthly essentials such as groceries, utility bills, and housing costs don’t just vanish after a tough month. When charged to a credit card, the following month’s budget has to account for a new cycle of basic expenses, along with payments from the previous month, typically incurring interest.
AARP found that 47% of adults aged 50 and older with credit card debt rely on cards to cover essential living costs. For seniors aged 65 and over, 43% indicated that cards helped them manage everyday expenses, while 19% expressed mixed feelings about their reliance on credit.
While credit cards can help temporarily, they certainly do not change recurring expenses into isolated costs.
6. Keeping a Fixed Budget
Though a lot of baby boomers live on fixed incomes, their retirement budgets should adapt as daily costs fluctuate.
“Inflation can be tricky to monitor annually, but it becomes startlingly clear when reflecting on your car insurance, grocery, or lawn care bills,” stated Brendan Dooley, a retirement financial planner.
For instance, the past year saw energy prices increase by 14.7%, while overall consumer prices only rose by 3.4%, according to the Bureau of Labor Statistics. The Energy Information Administration also noted a 6.2% rise in residential electricity costs from May 2025 to May 2026.
“Throughout a retirement that could last decades, boomers need to ensure their portfolios are equipped to handle not only current inflation but also unexpected future spikes,” Dooley advised.