BASIC Bank’s Ongoing Struggles Following Financial Irregularities
Once a respected state-owned bank, BASIC Bank continues to grapple with significant financial challenges stemming from the period when Sheikh Abdul Hye Bacchu served as chairman. Under his leadership, the institution faced allegations of irregularities amounting to around Tk 4,500 crore.
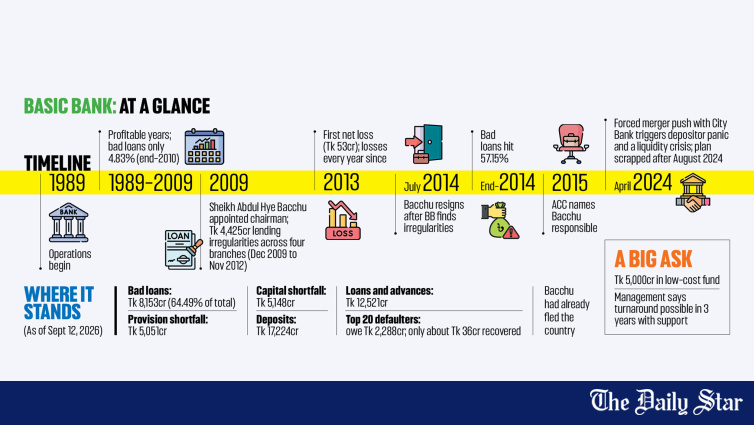
Founded in 1989, BASIC Bank maintained profitability until 2009 when Bacchu was appointed as chairman by the Awami League government. Unfortunately, this marked the beginning of a troubling era filled with financial mismanagement.
Subsequent inspections by Bangladesh Bank (BB) revealed alarming patterns of loan disbursement—specifically, Tk 4,424.93 crore allocated with serious irregularities from December 2009 to November 2012. Disturbingly, these loans remain unrecovered.
Bacchu stepped down from his position in July 2014, shortly after BB disclosed extensive irregularities and recommended the dissolution of the bank’s board. At that time, the bank’s nonperforming loans had surged to 57.15 percent from just 4.83 percent at the end of 2010.
Despite the abrupt onset of corruption during his tenure, Bacchu was not officially held accountable until 2015, by which point he had already fled the country.
Failed Merger Compounds Issues
BASIC Bank reported a net loss of Tk 53 crore in 2013, the first of many consecutive years of losses. By 2023, the losses had escalated to Tk 416 crore, ballooning to Tk 655 crore by mid-September. Bad loans increased to Tk 8,153 crore, accounting for 64.49 percent of the total loans, alongside a provision shortfall of Tk 5,051 crore and a capital deficit of Tk 5,148 crore.
In April 2024, a voluntary merger attempt with City Bank, aimed at addressing the bank’s weaknesses, initiated by then BB governor Abdur Rouf Talukder, only exacerbated the situation. The effort led to a liquidity crisis as public trust dwindled, causing panic among depositors. Following a political shift in August 2024, the merger was ultimately abandoned.
Helal Ahmed Chowdhury, the current chairman since November 2024, noted that lingering issues persist despite improvements over the past two years. He pointed to the massive scam initiated in 2009 as a continuing setback. “We’re still dealing with the fallout,” he said.
The bank is now focused on mitigating nonperforming loans, expanding its import-export activities, and enhancing its remittance channels through overseas partnerships.
Seeking Support for Recovery
Chowdhury mentioned the bank’s initiative to secure Tk 5,000 crore in low-cost deposits from the government or Bangladesh Bank to mitigate its financial troubles. “The proposal is still in process,” he added, emphasizing that this funding could replace higher-cost deposits, thus improving the liquidity situation.
The bank also aims to engage in Special Notice Deposit (SND) accounts with government agencies, an avenue that could provide financial relief and bolster depositor faith.
As of September, deposits totaled Tk 17,224 crore, while loans stood at Tk 12,521 crore. The bank is collaborating with Sonali Bank and others to navigate bilateral arrangements and boost remittance flows.
In a bid to enhance its lending and recovery processes, BASIC Bank has implemented a procedure where each branch must present two loan proposals and two recovery strategies each month. With 72 branches and 35 sub-branches, the bank recovered Tk 79 crore in cash and Tk 229 crore in non-cash through efforts to collect classified loans.
Signs of Improvement?
Chowdhury remains cautiously optimistic, suggesting an upward trajectory despite the bank’s history of legacy losses. He stated that assistance from BB through regulatory measures is essential for a successful turnaround. “We believe we can recover within three years with the right support,” he asserted, adding that a solid plan is underway that focuses on funding, governance, and capital input.
Defaulters and Recovery Efforts
As of June, the top 20 defaulters owed BASIC Bank a staggering Tk 2,288.25 crore in classified loans. The largest defaulter, Amader Bari Ltd, alone owes Tk 204.66 crore. Other notable defaulters include firms like Crystal Steels & Ship Breaking Ltd and Western Housing Ltd, all marked as “Bad/Loss” category under BB classifications.
Recovery efforts against these debts have been less than satisfactory. So far, collections add up to merely Tk 36.4 crore—just about 2 percent of what is owed. The chairman indicated that legal actions are underway against these defaulters, with further recovery strategies in the works.
Need for Strong Governance
Toufic Ahmad Choudhury, former director of the Bangladesh Institute of Bank Management, offered a strong critique of current recovery approaches. He pointed out that there’s no precedent in Bangladesh for a weak bank resurrecting solely through government liquidity or capital support. He emphasized that robust governance and an unwavering commitment to reducing nonperforming loans are fundamental to any chance of recovery.
“Support should come only with a commitment to good governance,” he suggested, underscoring the government’s role in the failures of state-owned banks. In his view, real reform hinges on political will, which appears insufficient at present.