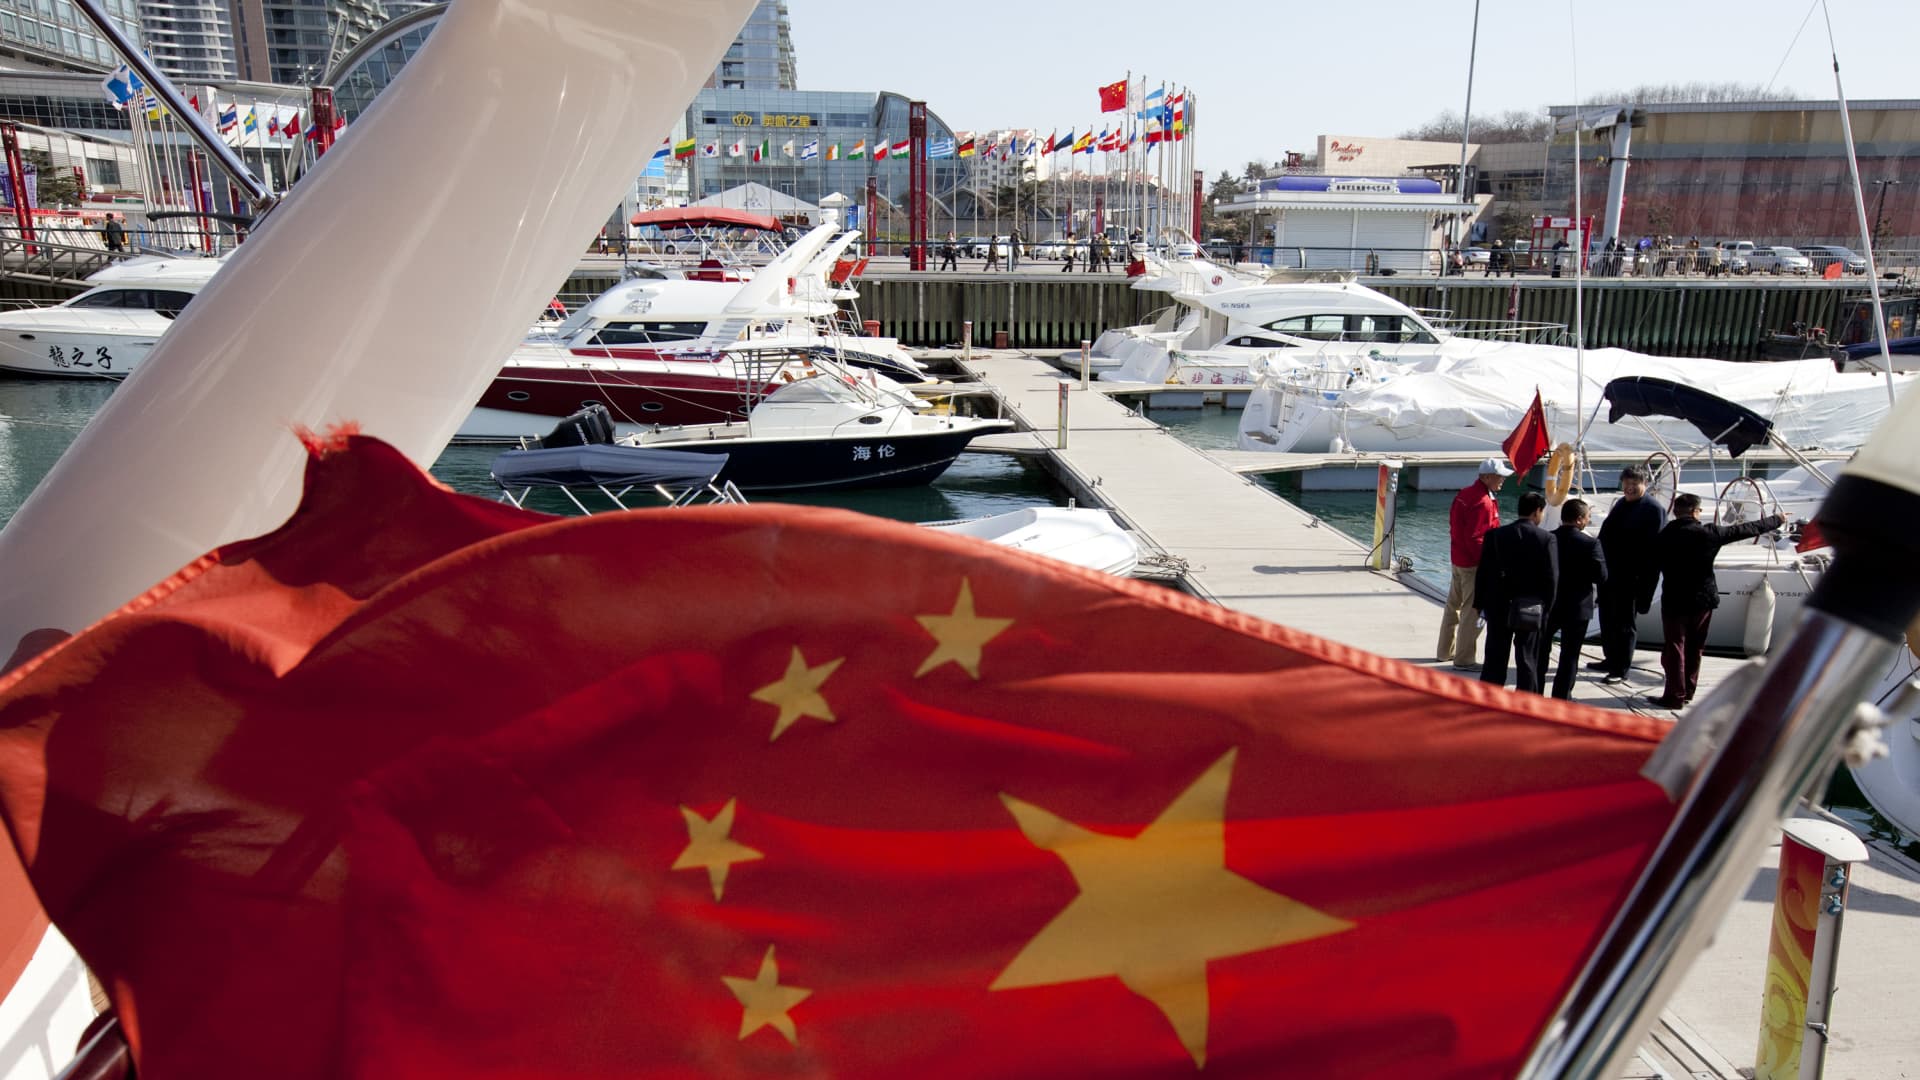
An increasing interest in family leisure activities and a surge in wealth are driving up demand for boats, ranging from small dinghies to large yachts.
The Chinese government is working to clarify new tax regulations concerning offshore trusts, which have created uncertainty for affluent Chinese citizens and their financial advisors. The State Tax Administration in China has been training local tax officials to standardize the application of these new rules, which affect offshore trusts created long ago, as discussed by various tax lawyers.
Additionally, the National Tax Agency has circulated draft guidelines to local law and accounting firms and plans to hold a meeting with legal professionals soon. Some lawyers are hopeful that more guidance will be provided, potentially including a public release of the documents.
Winson Lee, co-head of Asia tax at DLA Piper, noted that the STA is offering training at several administrative levels to ensure consistent interpretation among local tax offices.
Requests for comments from the Chinese embassy in Singapore and tax authorities in Beijing, Shanghai, and Guangdong province went unanswered.
In a recent move, Beijing imposed a 20% tax on offshore trusts, a method commonly used by wealthy individuals in China to secure significant offshore assets. This announcement resulted in panic among tax and legal professionals and led to rushed efforts to gather funds for compliance. The tax will be enacted at various stages of the trust’s lifespan, including its creation, profit distribution, and eventual closure. Individuals are also mandated to declare any outstanding taxes related to assets already moved into these trusts within 90 days of the regulation’s announcement, with penalties for late submissions.
confusion
While the new rule eliminated years of regulatory uncertainty, it also generated confusion regarding its enforcement. Trusts formed after 2023 will incur a 20% fee at inception, but there are lingering questions about how many years back existing trust owners need to report annual taxes, according to Yuan Cao, a partner at Yingke law firm in Beijing.
Advisors have also pointed out potential conflicts with trust assets, especially in light of foreign investment reporting regulations released in July, which may attract scrutiny from authorities regarding the original departure of funds from China.
It’s unclear, too, whether the typical three- to five-year statute of limitations for declaring offshore trusts from before 2023 applies here, or how much documentation will be necessary for applications. Lee from DLA Piper also raised questions about whether the October deadline is for tax return submissions or full payment. Local authorities are anticipated to align with STA’s explanations in the near future.
It’s not unusual for China’s central government to adjust significant policy decisions through supplementary announcements. However, this clarification period may reduce the 90-day timeframe given to taxpayers for compliance.
One lawyer based in Hong Kong, who preferred to remain anonymous due to the sensitive nature of this issue, indicated that before these new regulations were introduced, there were varied approaches among local governments. The lawyer acknowledged that the STA is aware of the prevailing uncertainties.
Some affluent individuals had previously resolved tax debts through lump-sum settlements with provincial offices, but it’s currently unclear if such agreements will continue to hold under the new tax framework.
BEIJING, CHINA – AUGUST 11: The entrance to the State Taxation Bureau of the People’s Republic of China, as seen on August 11 in Beijing, China.
A gathering storm
This move to raise taxes comes as the Chinese government is on the lookout for new revenue sources. Local government finances have been hit hard due to a slump in land sales, which were once a major income stream.
Dan Wang from Eurasia Group stated that personal income tax is likely to become an essential fiscal revenue source as the government seeks to broaden its tax base and improve enforcement, particularly targeting wealthy individuals and their offshore holdings.
Chinese taxpayers are now required to report income from global sources, including returns on overseas insurance products, as officials noted earlier this month.
In the first half of this year, personal income tax revenues reached around 900 billion yuan, reflecting a 13% year-on-year growth, which marks the largest increase among major tax categories in China, according to Wang.
The government is also tightening controls on capital outflows. Earlier this year, authorities banned three online trading platforms from servicing mainland users, and cities like Beijing and Hangzhou have begun taxing overseas insurance payments made to Chinese citizens.
“These actions might suggest an impending crisis,” remarked Neo Wang, chief China strategist at Evercore ISI, though he cautioned that this sentiment might be exaggerated.
In late July, a meeting of China’s State Council introduced new immigration rules effective from September, expanding the circumstances under which citizens may be prohibited from leaving the country, particularly for violations tied to national security.
Some advisors believe this regulatory framework may provide local governments with a stronger legal basis to prevent individuals liable for tax debts from departing the country.
“Restricting individuals with tax liabilities from leaving is not something new; some have been impeded even before these new regulations were established,” explained Max Li from EIK Business in the UK. “The recent rules just enhance existing practices, which aren’t surprising.”