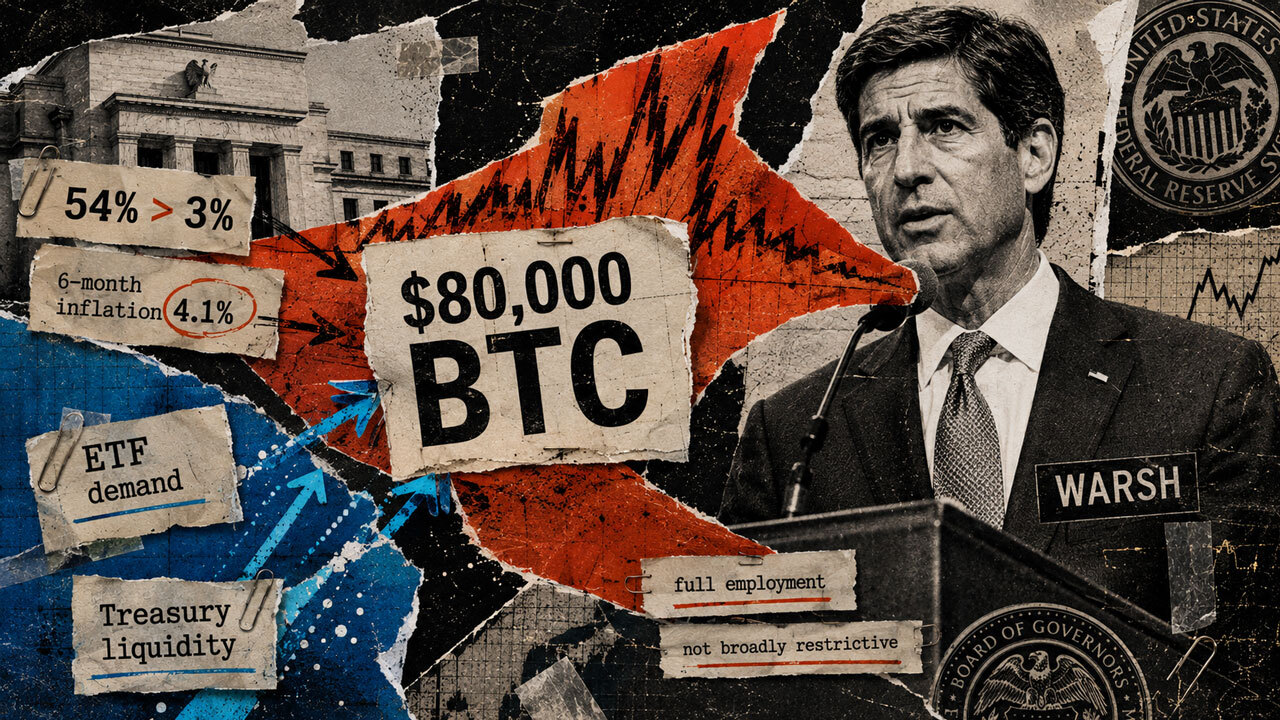
Bitcoin now faces a new benchmark at 54%, referring to the portion of the personal consumption expenditures basket that Federal Reserve Chair Kevin Warsh mentioned, which has seen a rise of over 3% in the past year.
In his speech at Jackson Hole, he turned a theoretical discussion about persistent inflation into a measurable criterion, now highlighting Bitcoin’s struggle to regain the $80,000 mark.
During Asian trading, Bitcoin dipped below $80,000 after having reached $81,280 overnight. Following the speech, multiple Bitcoin market updates indicated that BTC remained under that threshold, fluctuating around $79,000.
Warsh’s comments provided traders with a clearer framework to assess the risks associated with the recovery.
Spot Bitcoin ETFs listed in the U.S. saw an influx of over $1.1 billion in four sessions ending August 27. Additionally, the Treasury is planning larger liquidity-support buybacks, set to start on September 9, but these are primarily focused on debt management.
The challenge surrounding the $80,000 mark is whether strong ETF demand, coupled with better Treasury market conditions, can handle volatility, all while Warsh’s criteria for policy tightness remains active.
The 54% reading changes the policy test
Warsh pointed out that 54% of the 199 PCE components rose faster than 3% over a year, while 49% exceeded that during a six-month period.
The breadth measure for the 12-month duration has decreased from a post-pandemic apex of nearly 77%, yet it’s still significantly higher than the 32% average from the two decades preceding the pandemic.
Since the 77% peak and 32% average are derived from 12-month comparisons, Warsh introduced the separate six-month rate of 49% as a more current indicator.
He also noted that the six-month annualized headline inflation stands at 4.1%. The Bureau of Economic Analysis reported a 0.2% rise in the headline PCE price index for July, with a year-over-year increase of 3.7%.
These statistics make it harder to justify a swift shift towards easier policies. Warsh emphasized that the Fed’s target of 2% PCE inflation remains unchanged, indicating that labor markets are consistent with full employment and very few signs of restraint appear in credit and loan markets.
He remarked that broad financial conditions cannot be easily characterized as restrictive.
Warsh committed to maintaining a disciplined policy approach. For Bitcoin, the need to present data showing that inflation is narrowing within the entire basket has intensified.
As Bitcoin doesn’t generate yield, the prospect of ongoing higher policy rates makes cash and short-term government debt more appealing, while increasing the discount rate applied to risk assets.
There is potential for crypto-specific demand to offset this pressure, but it must keep coming in. The record from ETFs highlights just how concentrated this demand has become.
ETF demand meets a live rates test
The strongest case for Bitcoin’s uptick is illustrated in the Farside Investors flow table. On August 24, U.S.-traded spot Bitcoin ETFs gained a net $337.6 million, followed by $314.3 million on August 25, $232.2 million on August 26, and $242.3 million on August 27.
The makeup of this substantial influx undermines the assertion that demand is already widespread and sustainable. A significant portion of this came from BlackRock’s iShares Bitcoin Trust (IBIT), which accounted for approximately $971.7 million, or 86% of the total.
A concentrated inflow trend can still bolster prices, but it makes the outcome vulnerable to any shifts in allocation across a single product.
Now, there are three visible tests for durability: whether these inflows persist post-speech, if they extend beyond IBIT, and whether Bitcoin can recapture the $80,000 mark. Successfully passing all three would give the ETF channel the semblance of sustained absorption, whereas failure would suggest the four-day surge appears more like a fleeting positioning cushion.
The curve kept near-term pressure alive
The Associated Press reported that the two-year yield increased to 4.29% from 4.22% just before the speech.
The ten-year yield slightly rose to 4.69% from 4.67%, while the 30-year yield dipped to 5.17% from 5.19%. It’s important to note that these comparisons were based on late August 27, so they shouldn’t be viewed as a synchronized reaction.
For Bitcoin, the rise in the two-year yield serves as a more direct warning as it reflects the segment of the yield curve most sensitive to the expected policy changes. The mixed long-end signals didn’t indicate a widespread panic in the bond market; instead, investors appeared to be distinguishing between immediate Fed risks and long-term considerations concerning growth, debt supply, and inflation.
A single day’s yield movement can change, and the data from 54% and 49% create a repeatable policy test. The ETF flows reflect whether the demand specific to crypto is robust enough to weather any volatility that arises from changes in that test.
Treasury support is debt management, not Fed easing
The Treasury announced that liquidity-support buybacks in the 10-to-20-year and 20-to-30-year sectors would increase from $2 billion to at least $4 billion per operation starting September 9 through November 4.
These larger operations could facilitate trading in older, less-liquid securities and reduce friction in the long-end market. Since the Treasury market underpins financing and collateral conditions across the financial landscape, improved trading can indirectly boost risk appetites.
This does make the program pertinent to Bitcoin, but the linkage remains conditional and indirect.
The Treasury has described these buybacks as standard debt-management actions funded through its wider issuance framework. Their statement on the program clearly differentiates liquidity support from emergency measures.
Essentially, these operations retire less liquid Treasury debt whilst the Treasury continues to finance itself through new issuances.
If treated like quantitative easing, it would blur the line between fiscal debt management and monetary policy, overstating the support available for Bitcoin.
The upcoming increase doesn’t take effect until September 9 and cannot account for Bitcoin movements prior to Warsh’s August 28 speech, nor can it mitigate the near-term rate risk associated with current inflation levels.
The conditions for a durable $80,000 recovery
Bitcoin’s case for support appears valid but contingent. The ETF channel has accounted for over $1.1 billion in four completed sessions, and the planned Treasury operations may ease trading conditions on the long side.
These factors can help cushion volatility, while Warsh’s framework poses opposing challenges.
Since inflation exceeds targets and pressure is broad throughout the basket, the argument for immediate policy relief isn’t well-founded.
A consistent recovery above $80,000 would require more than just a fleeting influx of support. The definitive evidence would lie in sustained ETF demand that goes beyond IBIT, a reliable reclaiming of the price level, and inflation data that significantly reduces Warsh’s breadth readings.
Until that happens, while ETF demand and Treasury market backing may cushion the effects of tighter financial conditions, the 54% benchmark clarifies the terms under which Bitcoin can endure.