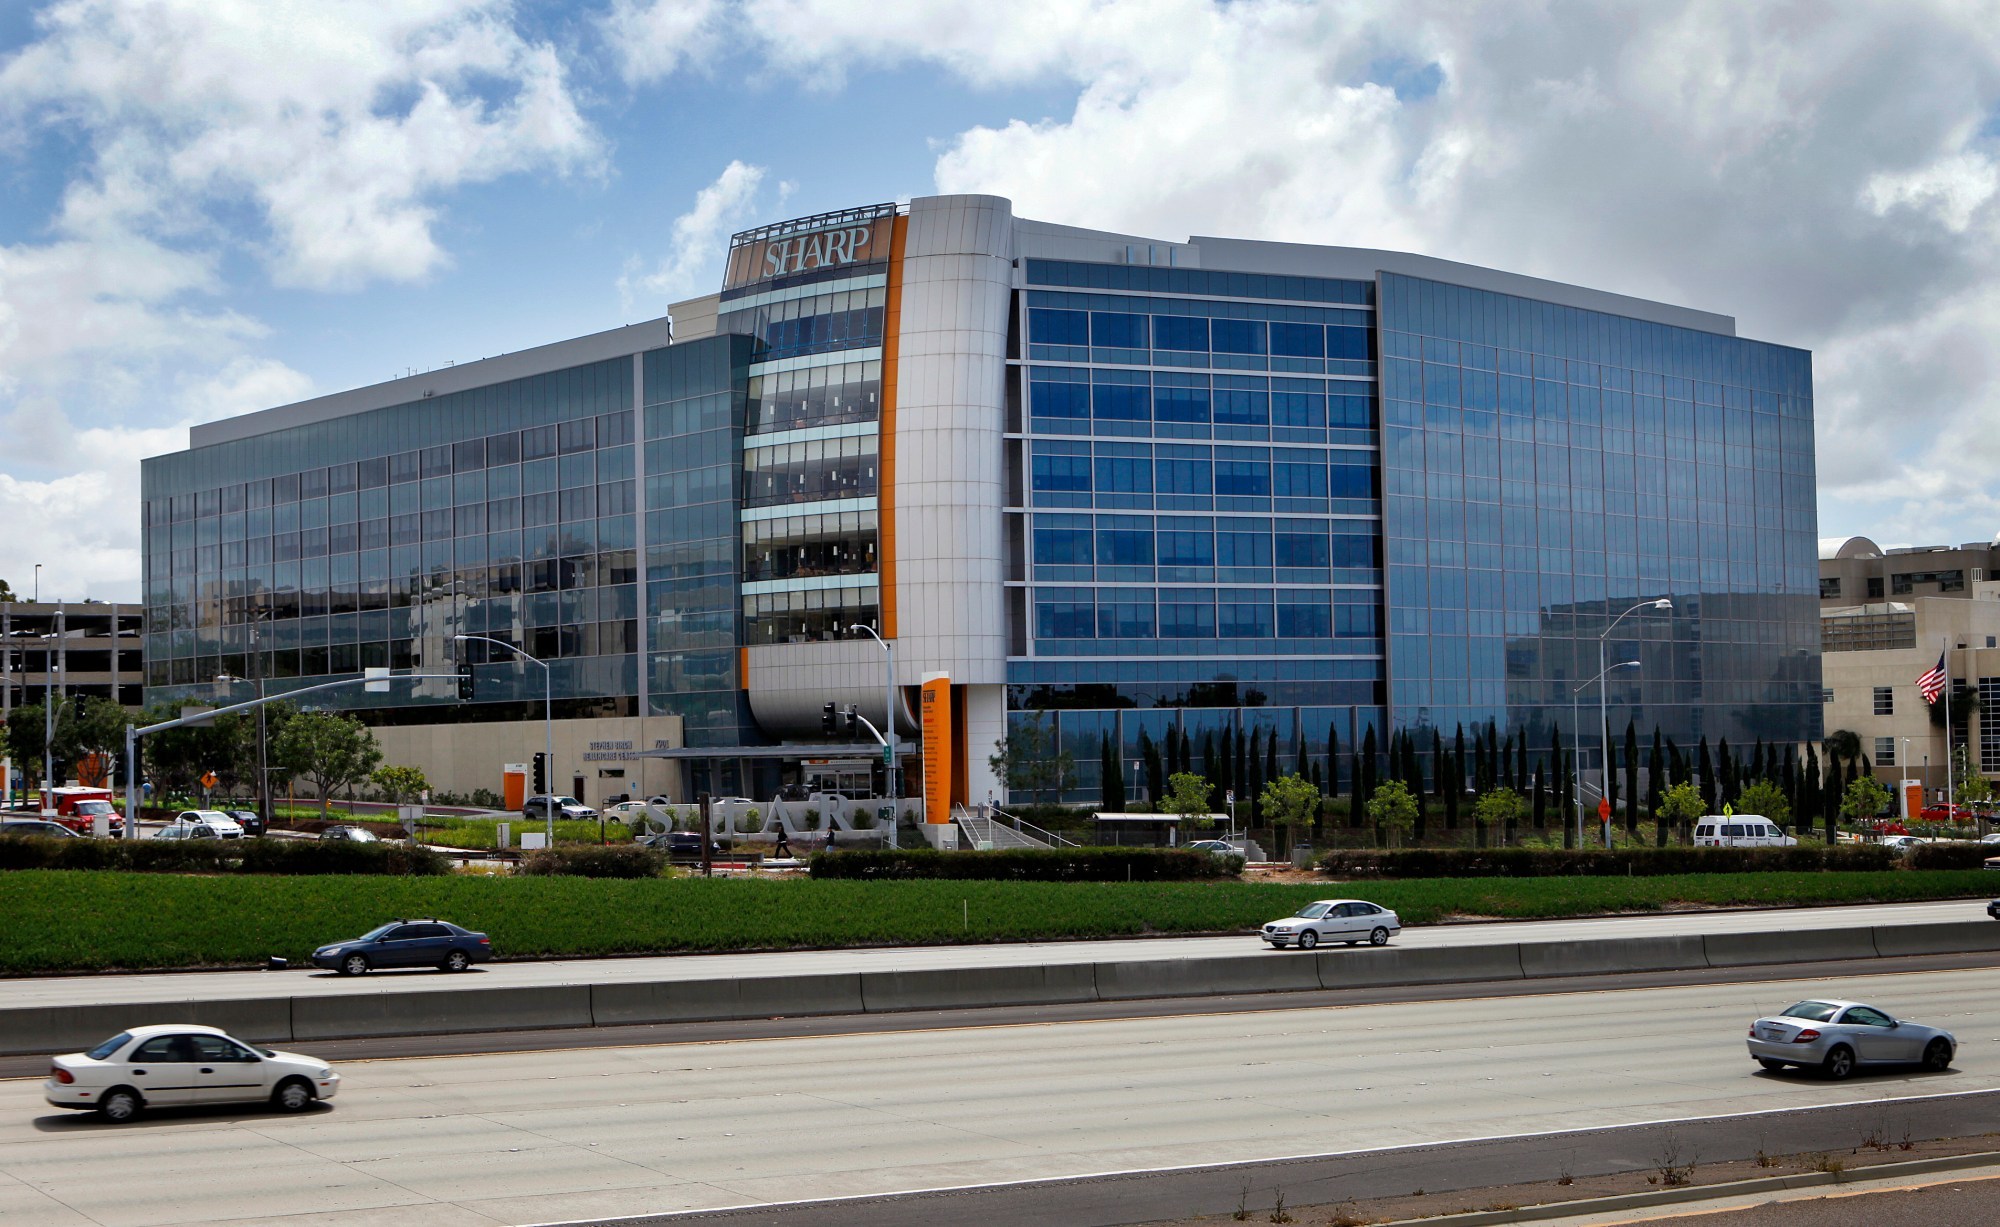
Sharp Health Plan to Cease Medicare Advantage Coverage in 2027
Sharp Health Plan has started informing its patients that it will discontinue its Medicare Advantage coverage in 2027. This shift will force many, potentially thousands, to find new coverage options, which might come at a higher cost.
Officials from the region’s largest healthcare provider confirmed this development on Monday, following reports circulating in trade publications and among health insurance brokers the previous week. Similar to many healthcare systems nationwide, Sharp is aiming to lessen its involvement in the federal program, which has recently prompted numerous providers to voice concerns about reimbursements failing to cover care costs.
In 2023, Scripps Health withdrew from Medicare Advantage, affecting around 32,000 members who needed to find new doctors. Earlier this year, UC San Diego Health also limited access to its primary care network. However, Sharp will maintain access through United Healthcare, which has long provided its own plans centered around Sharp.
Medicare Advantage is a nationwide initiative allowing individuals over 65 to have private health insurance companies manage their benefits. Alternatively, there is the option of sticking with original Medicare, which allows visits to any participating doctor but necessitates supplemental “medigap” and “Part D” prescription drug plans. These options come with additional monthly costs that many may find unmanageable.
Sharp Health Plan’s decision to stop its individual Medicare Advantage plans will impact roughly 17,000 beneficiaries, though it will continue to offer group plans for local businesses. More crucially for individuals, Sharp will keep accepting Medicare Advantage plans from United Healthcare tailored for its services.
Chris Howard, CEO of Sharp, mentioned that the goal is to ensure that Medicare Advantage patients are part of a structure suitable for the program’s “capitation” model. This model pays providers a set amount per beneficiary to cover all medical needs. Any remaining funds may benefit providers, but they are also responsible for costs exceeding the per-patient payments.
According to Howard, this model is more advantageous for plans with a larger number of enrollees. United Healthcare’s Medicare Advantage offerings that include Sharp have significantly outnumbered those from Sharp Health Plan. Data from the U.S. Centers for Medicare & Medicaid Services revealed that three United Healthcare-Sharp plans offered for 2027 collectively had about 38,000 enrollees in 2026, which is more than double the enrolment in Sharp’s Medicare Advantage offerings.
Howard emphasized that scale is essential for the capitation model to function effectively. It’s important to have a sufficient patient pool to balance out high-cost cases with those who incur fewer medical expenses.
“We must ensure that our numbers align for a long-term sustainable program, similar to our commercial health insurance products,” Howard explained. “Medicare Advantage can be successful—Kaiser Permanente certainly proves that—but it requires proper scale and managed care infrastructure.”
It seems that continuing access to United Healthcare Medicare Advantage plans may ease the transition for beneficiaries.
Sophie Exdell, manager of San Diego’s Health Insurance Counseling & Advocacy Program (HICAP), remarked that the United Healthcare plans focusing on Sharp are fairly comparable regarding premiums and medical copays to those previously offered by Sharp Health Plan.
After analyzing the annual pricing breakdowns that HICAP prepares, Exdell noted that the differences for the upcoming open enrollment period starting on October 15 aren’t drastic.
“Both Sharp and United Healthcare have had plans with $0 copays for doctor visits over the last few years, and it looks like United Healthcare may offer that again for 2027,” Exdell added.
However, since different services may have varying copays, a thorough comparison is recommended for all Sharp Health Plan members considering a switch to a United Healthcare plan. Additionally, Exdell cautioned that it’s essential to evaluate prescription drug costs, as these can differ significantly between plans.
Sharp Health Plan’s withdrawal from Medicare Advantage marks the most notable change for the upcoming year, yet local health insurance broker Pat Salas also pointed out other shifts. Cuts from Aetna, Central Health, and others will collectively affect about 8,000 Medicare Advantage enrollees, who must seek new coverage this fall.
For those whose Medicare Advantage plans have been discontinued, Sharp beneficiaries can opt for original Medicare. HICAP counselors are available to assist in determining supplemental insurance costs and can provide detailed comparison charts of available options.
For more information, HICAP offers resources, and Medicare beneficiaries can arrange consultations on its website.