Recent inflation figures that came in unexpectedly high may leave many US central bankers feeling let down. They had been hoping for a natural easing of price pressures, but this could lead to an interest-rate hike at the upcoming Federal Reserve meeting, with more increases likely to follow.
According to the Bureau of Labor Statistics, core consumer price inflation—excluding energy and food—rose by 0.3% last month compared to the previous month. This was above the anticipated 0.2%. Over the past year, core CPI increased by 2.4%, while overall consumer inflation saw a 3.4% rise.
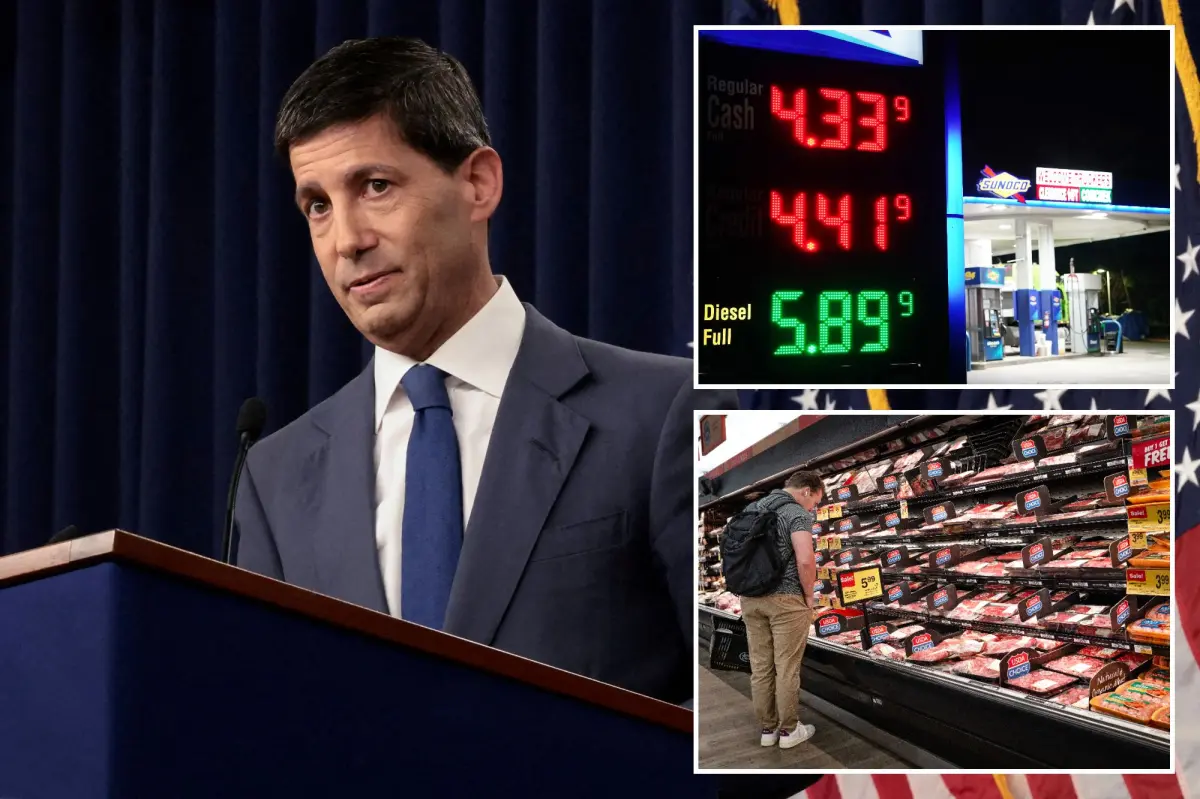
When you also consider a stronger-than-expected producer price index from August, released recently, and the surge in oil prices, now above $100 a barrel amid escalating tensions in the Middle East, it looks like inflation is again moving upward, counter to the Fed’s 2% target that has not been met for over five years.
Seema Shah, chief global strategist at Principal Asset Management, remarked that the solid 0.3% core CPI figure, combined with soaring energy costs and ongoing conflict with Iran, pretty much guarantees a Fed rate hike next week. She further suggested that, after years of above-target inflation, it’s likely that policymakers will determine more than one increase is necessary to achieve price stability.
So far this year, the Fed has kept its policy rate within the 3.50%-3.75% bracket, including a 9-3 vote in July that indicated a growing sentiment among Fed members that higher rates were needed.
At the Kansas City Fed’s annual meeting in Jackson Hole, Wyoming, Chairman Kevin Warsh expressed that if there’s no clear and sufficient movement toward the 2% target, action is likely necessary. However, some economists are now questioning whether the August data fits that criterion.
Omair Sharif, founder of Inflation Insights, argued that the Fed must act accordingly. He said, “You can’t give a speech like you did at Jackson Hole and not back it up with a rate hike.” He cautioned that failure to follow through might lead to skepticism about their commitments.
On the other hand, not all economists are on the same page. The Fed’s target for 2% inflation is based on the personal consumption expenditures price index, which emphasizes certain items differently than the CPI. Interestingly, Friday’s CPI data indicated a decline in software and accessory prices, and a slowdown in core goods prices. Analysts from Oxford Economics speculate the core PCE for August likely rose only a modest 0.2%, which could allow the Fed to hold off on raising rates next week. But they caution that the decision is finely balanced.
Some economists predict a more elevated core PCE reading, which could spark concerns among Warsh’s colleagues, who had been optimistic about a downward trend in inflation during June and July. At least two Wall Street firms, previously expecting to maintain rates, now project a hike in the coming week.
According to Piper Sandler analysts, this shift reflects increased inflation data as well as market expectations, indicating that Chairman Warsh would want to steer clear of a dovish surprise.
Short-term interest-rate futures traders are now estimating about an 85% likelihood of a quarter-point increase during the Fed’s September meeting—a shift from around 70% prior to the latest report. Market forecasts now also anticipate a second hike in December.
Christopher Hodge, an economist at Natixis, noted, “Today’s print doesn’t indicate a resurgence of core inflation; rather, it seems like a minor bump along the disinflationary path.” He suggested that a slight nudge via one or two hikes could be what the Fed considers necessary, starting with a potential increase next week.