According to Nobel laureate Paul Krugman, the recent upheaval in the bond market coinciding with widespread student protests in France is not just a random occurrence. It reflects the generational trade-offs involved in government spending.
In a post on his Substack, the City University of New York economics professor noted that the issues driving up French bond yields—such as high debt and deficits—aren’t exclusive to France. The United States faces similar fiscal challenges, particularly as an aging population increases entitlement spending more rapidly than revenue can grow.
But Krugman suggests that France is distinctive for a significant reason: its ongoing refusal to confront the realities of retirement. For instance, the official retirement age in France, allowing for full benefits, is just 62 in 2023, while the actual average retirement age is even lower than in most of Western Europe, at about 60.4 years.
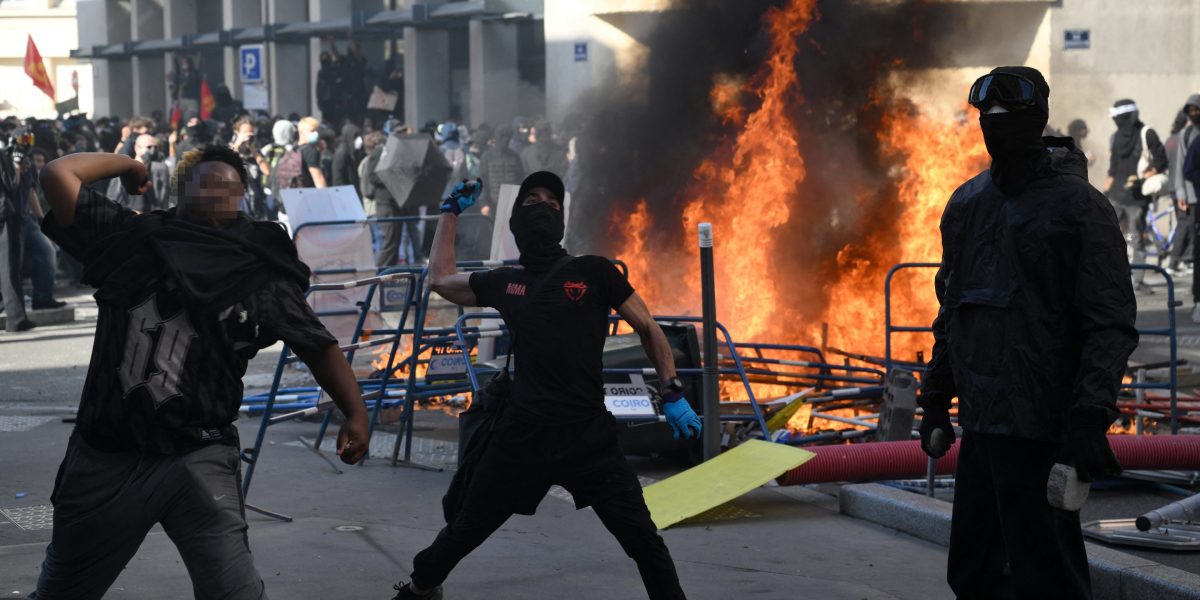
Simultaneously, French students are protesting due to issues like overcrowded classrooms, a lack of teachers, and school facilities unprepared for rising temperatures. Many protestors blame a history of underfunding in the educational sector.
Krugman connected the dots between generous retirement benefits and the rising student unrest, emphasizing a generational conflict regarding how public resources are distributed between older citizens and the youth of France.
He argued that the fiscal strain caused by France’s generous pension system has led to cutbacks in essential areas, particularly education, essentially transferring substantial benefits to older generations while neglecting younger ones. Thus, the widespread student protests shouldn’t come as a surprise.
In the U.S., the debt issue mirrors France’s, with rising expenditures for seniors as more baby boomers retire. Interestingly, even some Republicans are open to discussing tax increases to ensure the Social Security fund remains healthy.
On the French front, President Emmanuel Macron’s attempt to raise the retirement age to 64 faced significant political opposition, halting those plans. Looking ahead to the next presidential election, Marine Le Pen, a prominent far-right figure, has promised to revert the retirement age back to 62, and she has even entertained ideas of lowering it to 60.
Krugman indicated that such proposals would be incredibly costly and reflect a broader unwillingness among France’s right-leaning factions to face economic realities. He pointed out that this tendency isn’t exclusive to France—similar false promises can be seen in other contexts, such as those made by Donald Trump. For the moment, however, financial markets seem to be more concerned about France’s “fantasy economics” than anywhere else.
Markets are indeed indicating rising risks of a French debt default. Earlier this month, yields on 10-year French bonds climbed to levels not seen since 2002, and the gap between French and equivalent German yields grew the widest since the eurozone debt crisis of 2011.
While those metrics have since softened, the underlying economic conditions in France remain worrisome, with sluggish GDP growth, a budget deficit projected at around 5.4% of GDP, and increasing debt service costs as yields rise.
The debt-to-GDP ratio in France is expected to increase from 119% this year to 122% next year, and the government’s most recent strategy has struggled to reassure investors, who question its reliability.
Global strategists Thierry Wizman and Gareth Berry from Macquarie also noted the relationship between France’s debt issues and the student protests. In a recent note, they cautioned that prolonged protests could compel the government to approve increased spending, which would exacerbate the debt situation.
This, in turn, would lead to elevated yields on French bonds, making funding for such spending even more costly—essentially deepening the very problems the protestors are highlighting.
Wizman and Berry expressed concern that France is on the verge of a civil crisis, a state of polarization that has traditionally been evident only through electoral processes. They posited that there exists a direct, reinforcing connection between the rising debt yields and the recent street demonstrations.