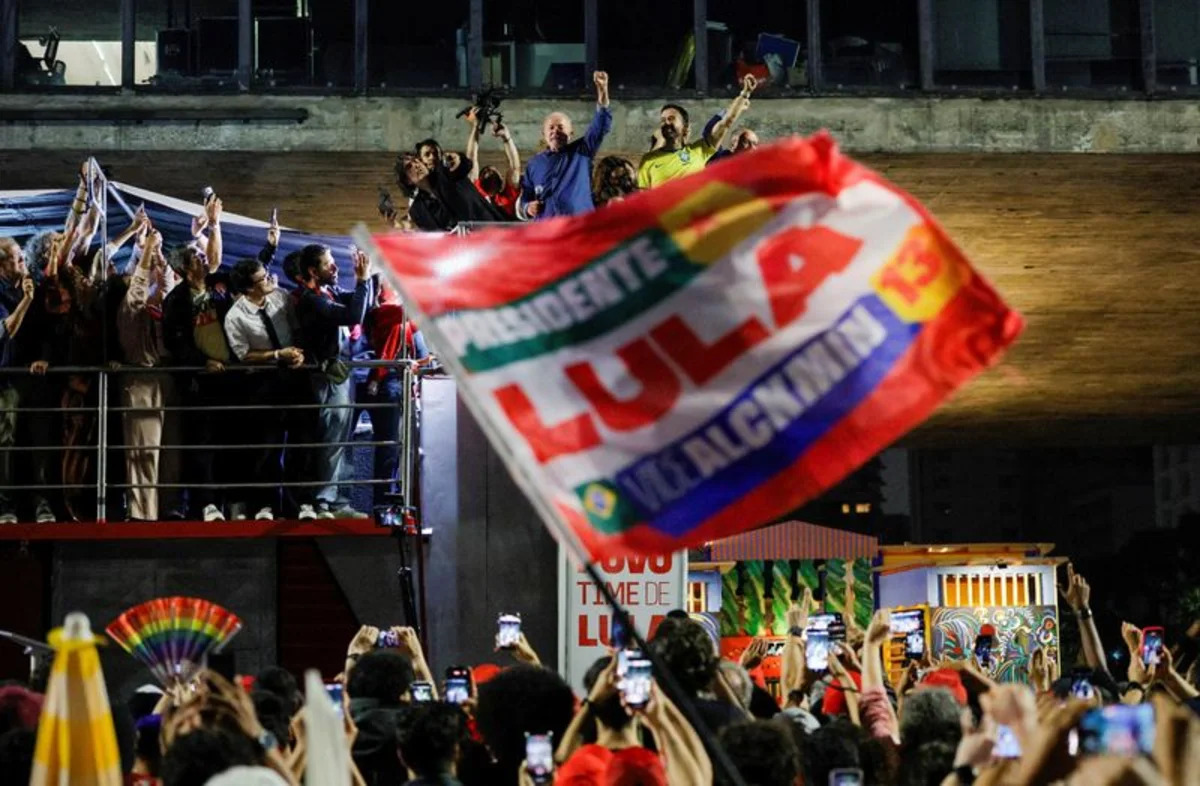
NEW YORK/BRASILIA/LONDON, Oct 26 – Trading on Brazil’s stock market was suspended on Monday, triggered by a circuit breaker, after President Luiz Inacio Lula da Silva secured reelection. This abrupt halt erased the optimistic sentiment seen earlier when right-wing rival Flavio Bolsonaro led in the first round of voting earlier this month.
The Brazilian real fell roughly 12% against the US dollar as trading commenced, while futures for the Bovespa stock index plummeted nearly 15%. Additionally, there was a notable increase in interest rate futures. Brazil’s international bonds also faced a selloff, with the longer-term debts experiencing the most significant drops, particularly the 2056 maturity which fell almost 3 cents.
The stock exchange paused trading for 30 minutes after the benchmark Ibovespa index dropped 10% from its prior close, according to a statement from B3, the exchange operator.
This action followed B3’s earlier decision to widen the daily trading limits for futures in response to the increased market volatility.
As the Brazilian financial markets took a hit, the Treasury decided to cancel its planned auctions of inflation-linked and fixed-rate government bonds slated for October 27 and 29.
This downturn marked a stark contrast to the rally earlier in the month, spurred by expectations of a shift toward a right-leaning government when Flavio Bolsonaro unexpectedly topped the initial round of Brazil’s presidential elections.
On the preceding Friday, stocks were nearly 7% higher compared to levels before that first voting round, and the real was about 5% stronger against the US dollar.
Interest rate futures had also shown optimism that a tighter fiscal policy under Bolsonaro would lead to lower borrowing costs.
Prediction markets had anticipated a Bolsonaro victory, with Kalshi suggesting a more than 75% probability of that result on Friday.
“We expect a significant market reaction on Monday, with a repricing of assets expected to lead to selloffs, and interest rate futures likely reaching their upper limits shortly after the market opens,” noted Luis Felipe Vital, who heads macro strategy at Warren Investimentos.
Bolsonaro’s refusal to concede and his insistence on pursuing an annulment added to the uncertainty among investors.
“How quickly Bolsonaro acknowledges the result—or at least allows the constitutional process to unfold—will be crucial for local financial markets,” remarked Chris Turner, a strategist at ING in London.
All eyes are now on Lula’s upcoming appointment of a finance minister and what it might signal regarding his fiscal policies.
“Markets will be watching for a commitment to fiscal discipline from the next Lula administration, starting with the naming of a new finance minister in the coming weeks,” added Graham Stock from RBC BlueBay Asset Management.
Lula now faces the daunting task of managing Brazil’s rising debt while still safeguarding social programs and investments. Investors are keen for signs that his gradual approach to fiscal policy might help lower borrowing costs.
“The Lula administration must also engage in some fiscal consolidation,” quipped Thierry Larose, a Vontobel Asset Management portfolio manager, “though many investors doubt it will suffice to restore debt sustainability.”
Should confidence falter, lenders might demand higher interest rates, exacerbating Brazil’s debt issues and increasing borrowing costs for businesses and consumers alike.
“Investors are looking for a clear commitment to fiscal discipline,” pointed out Alejo Czerwonko, chief investment officer for emerging markets at UBS Global Wealth Management. “We suspect the rally following the first round will be mostly priced out, and sentiment will likely remain weak until a coherent fiscal strategy is presented.”
Czerwonko emphasized the need to halt campaign-related spending while establishing a credible path to stabilize public debt. “It also means fostering a working relationship with an opposition-leaning Congress, since no fiscal plan can pass without it,” he added.
Lula’s team aims for a budget surplus of about 1.3% of GDP by 2030, which could help cover some interest payments and minimize the need for new borrowing. However, public debt already surpasses 82% of GDP, and legally mandated spending on pensions and other areas restricts potential savings.
“Lula’s policies mention spending cuts, but he hasn’t detailed how that will happen,” noted Divya Singaravelu, head of research at Meridian 1305 Capital.