Tax Exemption Under Section 54 for Two Flats: Insights from ITAT Ruling
Is it possible to claim tax exemption under Section 54 when the investment concerns two flats? A recent ruling by the Mumbai Income Tax Appellate Tribunal (ITAT) sheds light on this matter.
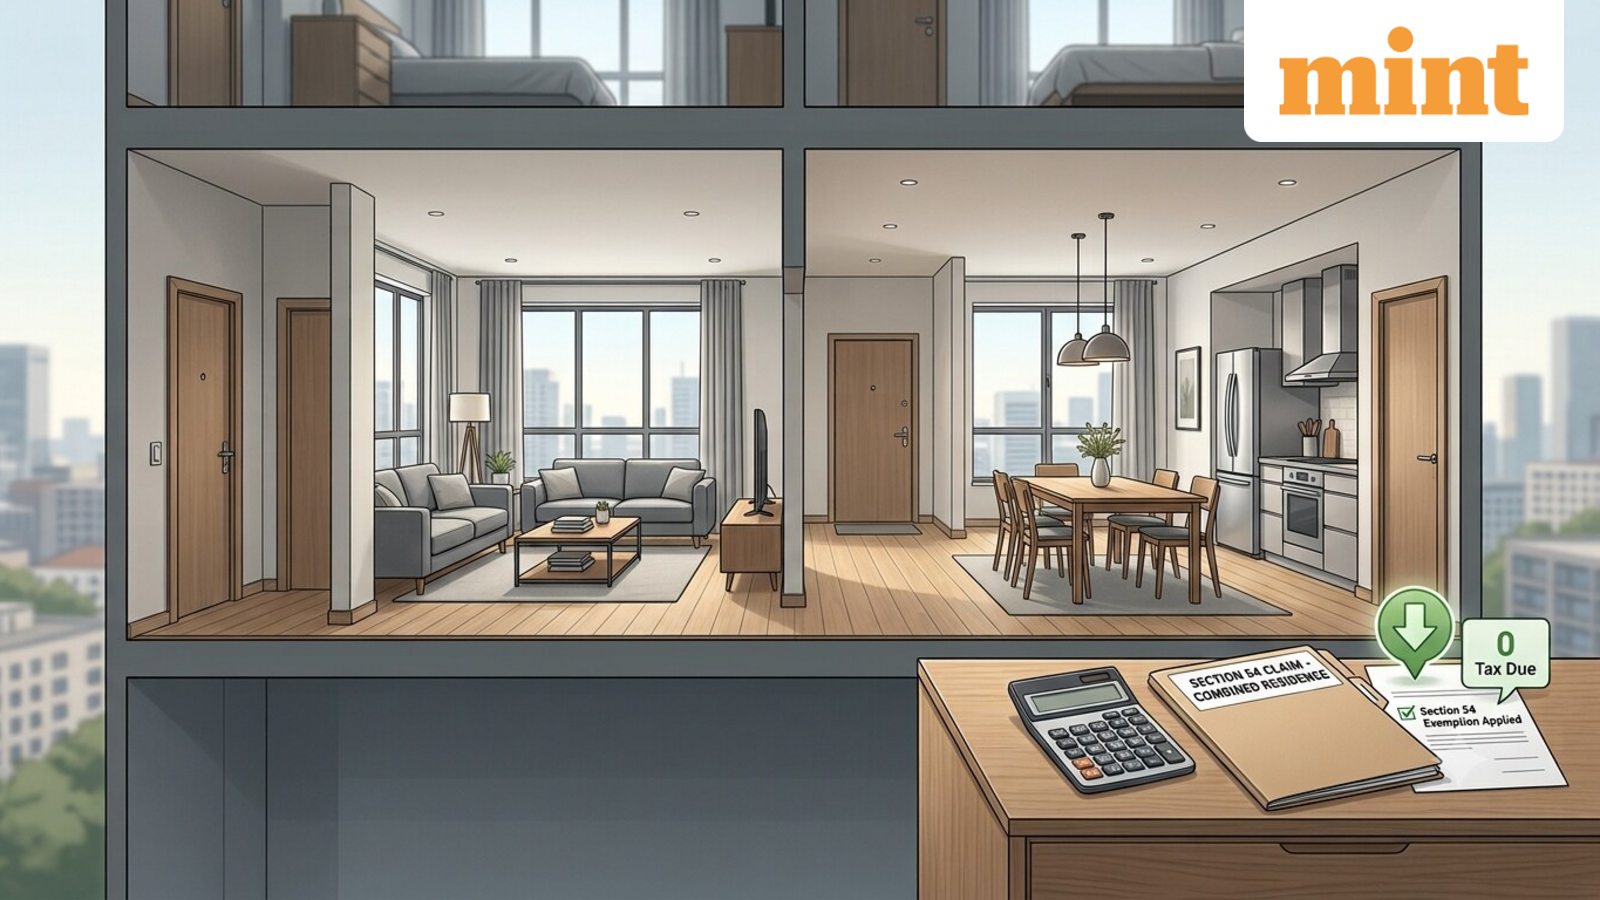
The Tribunal determined that two adjacent flats, which were legally and physically combined into a single residential unit, can be regarded as one house when it comes to claiming capital gains exemptions, as reported by TaxGuru.
Background of the Case
In this situation, the taxpayer sold a residential property in Malabar Hill, Mumbai, for ₹43 crore. After accounting for the original purchase price, he calculated the long-term capital gains to be ₹26.59 crore and sought to exempt this entire amount under Section 54 for the Assessment Year 2021-22.
The investment in question involved Flat Nos. 3101 and 3102 located in Lower Parel, Worli.
Section 54 offers relief from long-term capital gains that arise from the sale of a residential property, provided the gains are reinvested in another residential house.
Why Was Part of the Claim Rejected?
According to the TaxGuru report, the assessing officer (AO) considered the two flats as individual properties. Consequently, he approved the Section 54 exemption only for the ₹22.56 crore investment in Flat No. 3102, while taxing the remaining ₹4.03 crore of capital gains.
This matter gained significance because, starting from AY 2021-22, Section 54 stipulates the possibility of investing in two residential houses only if the capital gain does not surpass ₹2 crore.
Given that the taxpayer’s capital gain was ₹26.59 crore, the tax department contended that the exemption could not apply to two separate properties.
ITAT’s Perspective on Treating the Flats as One Unit
Later on, the taxpayer signed a registered supplementary agreement on March 25, 2022, with the developer for the amalgamation of the two adjacent flats.
Once the properties were combined, Flat No. 3101 lost its distinct identity, and the resultant property was designated as Flat No. 3102.
Why Did ITAT Uphold the Section 54 Exemption?
The Mumbai ITAT concurred with the CIT(A) that the two flats had effectively transformed into a single residential unit. Thus, the limitation concerning investments in two distinct houses was deemed irrelevant.
The Tribunal also accepted the supplementary agreement and associated bank statements.
The ITAT confirmed the ₹26.59 crore Section 54 exemption and rejected the Revenue’s appeal, making the ruling public on August 17, 2026, according to TaxGuru.
Overview of the Current Section 54 Rule
Section 54 allows individuals or Hindu Undivided Families (HUF) to claim exemptions on long-term capital gains (LTCG) from selling a residential property by reinvesting in another residential property within India.
To be eligible for the exemption, the original property must be owned for more than 24 months. If it’s sold within that time frame, it is regarded as a short-term capital asset, making the Section 54 exemption unavailable.
The new property must be purchased within one year preceding or within two years following the sale. Starting from AY 2021-22, there is a one-time option to invest in two residential houses in India, provided the LTCG doesn’t exceed ₹2 crore. This choice can only be utilized once in a taxpayer’s life.
The ruling from the Mumbai ITAT does not abolish the cap; rather, it clarifies that if two adjacent flats are legally and physically combined into a single residential unit, they can be classified as one house instead of two separate entities.
Nevertheless, beginning with AY 2024-25, the Finance Act, 2023 has set a limit on the amount eligible for Section 54 exemption at ₹10 crore. Any investment exceeding this figure will not be factored into the exemption calculation.
This content is intended solely for informational and educational purposes. It is advisable to consult a qualified expert for updates on laws and regulations.