Addressing National Fiscal Challenges
We need to face a hard truth if we’re serious about achieving fiscal stability in our nation—our resources are limited. Coming to terms with this reality feels like a pivotal moment, similar to what Vince Lombardi inspired in his Green Bay Packers when he said, “Gentlemen, this is a football.” After that, they went on to clinch the NFL Championship that year.
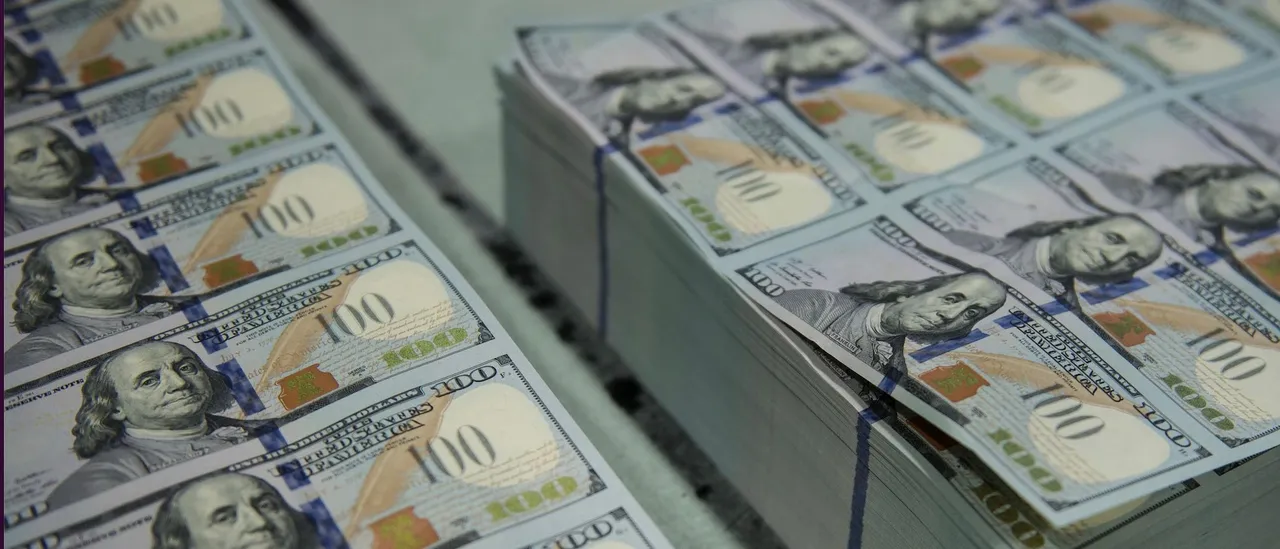
For our country, getting back to the essentials with finances involves confronting the unsustainable habit of borrowing $2 trillion yearly. This gap arises from spending $7 trillion while only generating $5 trillion in revenue. This has led to our national debt ballooning from $20 trillion in 2017 to a staggering $40 trillion today.
Even as our capital markets continue to thrive, it’s becoming harder to overlook the growing concerns surrounding our national debt. We’re spending more than $1 trillion every year just on interest—an amount comparable to what we allocate for both our military and Medicare. Moreover, U.S. Treasury bonds are now viewed as risky, which has caused interest rates to rise, and our debt has outpaced our gross domestic product.
Reaching the $40 trillion threshold is a clear signal that we need to focus on the fundamentals. This is a significant threat to our economy and national security—a situation that both Republican and Democratic leaders have contributed to for decades.
Fortunately, there is a bipartisan effort in Congress gaining traction, aimed at addressing our spending issues. The goal? To cut the deficit-to-GDP ratio from 6% to 3% over the next ten years and achieve a balanced budget in the following decade. The support for this initiative is encouraging and could serve as the launchpad for a coordinated, long-term strategy to reduce our debt-to-GDP ratio.
However, this will entail making tough choices, maintaining fiscal discipline, and having leaders willing to prioritize long-term solutions over short-term political gains. Examples of necessary actions include:
- Reforming major spending programs like Medicare, Medicaid, and Social Security, which are projected to go bankrupt in the early to mid-2030s. We need to ensure these programs remain viable for those who rely on them while also creating new pathways for younger generations.
- Establishing a robust safety net that empowers Americans to achieve lasting independence during difficult times.
- Guarding every taxpayer dollar against fraud. U.S. Treasury Secretary Scott Bessent has highlighted that up to 10% of our federal budget may be lost to fraud annually. President Trump’s Task Force to Eliminate Fraud has made significant strides in tackling this issue.
In Indiana, we understand that dramatic turnarounds are achievable, whether in college football or government finance.
Take the Indiana University Hoosiers, for instance. Despite their history of losses—the most in college football with 715—they clinched a championship last year. Coach Curt Cignetti made it clear, “There is no magic here. It is fundamentals.”
The same focused approach is what the State of Indiana had to adopt. For many years, we operated under severe financial strain. In 2002, for example, our state deferred hundreds of millions in payments to schools just to end the fiscal year with a tiny surplus—yes, just six cents.
That was Indiana’s moment to embrace fundamental change. By committing to improvements over two decades, our state transformed from a precarious position to having a healthy reserve, low debt, fully funded pensions, and even a AAA credit rating.
Turning things around requires an extraordinary amount of focus and discipline. Now, it’s our turn as citizens to rally together to avert a potential debt crisis that could have far-reaching implications for our families, finances, and freedoms.
It’s crucial we get back to the basics and unite as states to help our federal government craft a viable plan aimed at restoring our nation’s fiscal health and independence.
America has triumphed over significant challenges in the past, and getting our fiscal situation in order must be among them.