Understanding Debt and Recovery Rights
Debt plays a crucial role in our lives, whether it’s for purchasing a home, a car, or handling immediate expenses through personal loans and credit cards. Yet, situations like job loss or unexpected financial difficulties can sometimes hinder borrowers from keeping up with payments.
Defaulting on EMI loans can lead to various consequences, such as collection efforts, penalties, and recovery actions. But it’s important to note that defaulting doesn’t grant banks unlimited authority over borrowers, nor does it permit collection agencies to resort to threats or intimidation.
The specifics can change based on the type of loan, how severe the default is, and what legal steps the lender is pursuing.
Anshi Shrivastava, who leads personal finance training at 1Finance, explained that “just missing an EMI once doesn’t automatically give a bank the right to take away a borrower’s property or assets.”
When Can a Bank Seize Property Due to Loan Default?
For secured loans—like home or car loans—if a borrower defaults and their account is labeled as a non-performing asset (NPA), the lender can pursue legal measures to enforce the security provided.
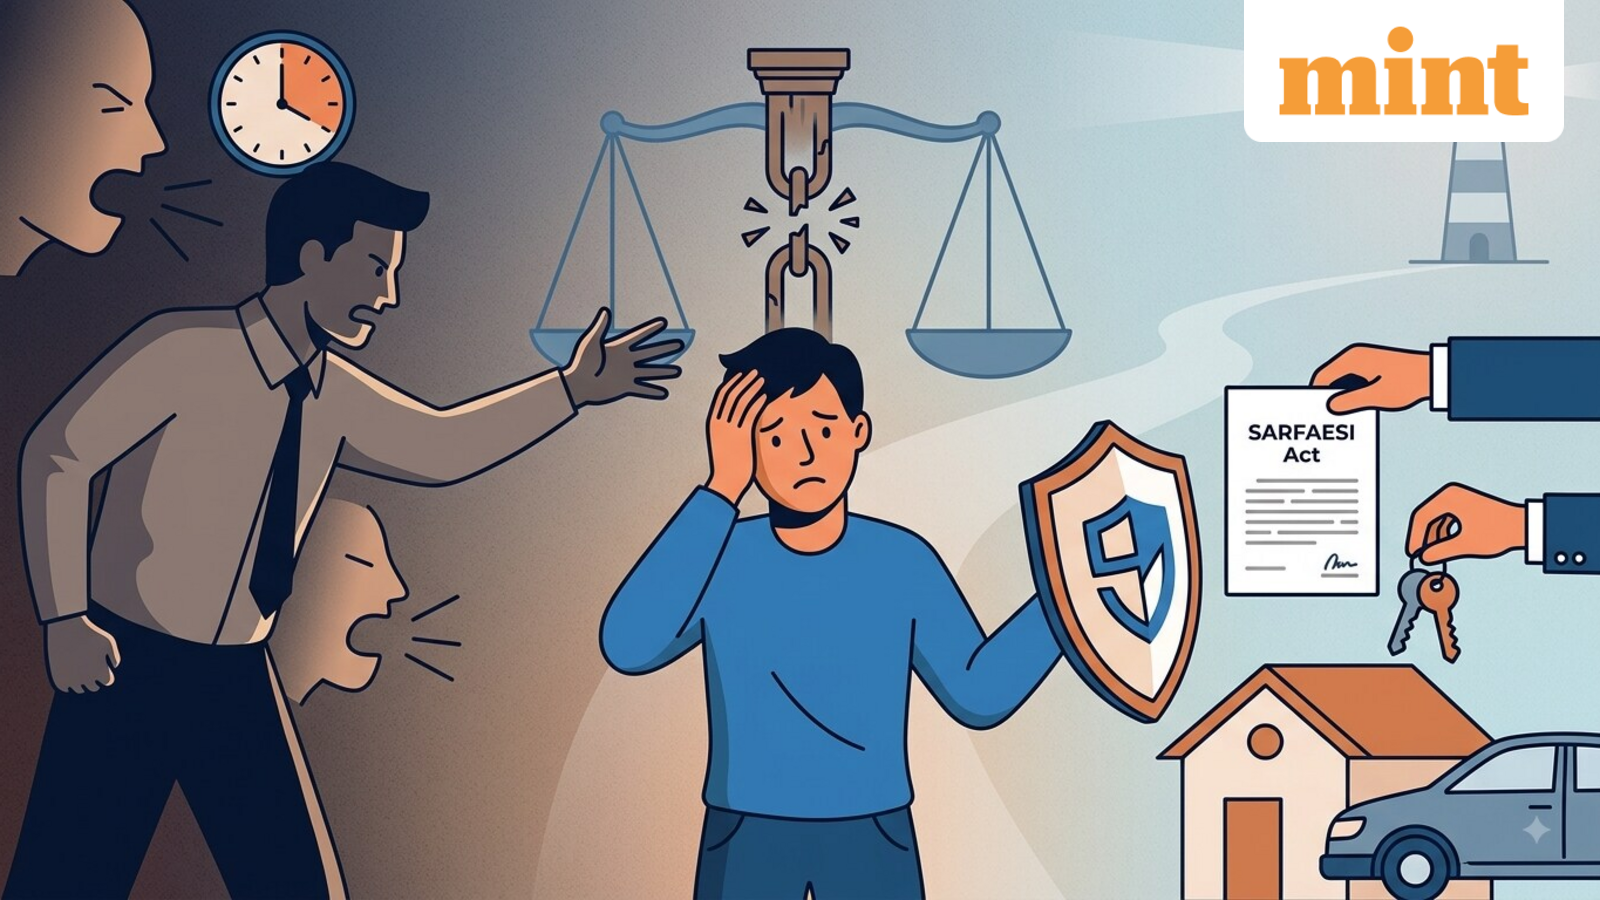
According to Section 13(2) of the Securitization and Reconstruction of Financial Assets and Enforcement of Security Interests (SARFAESI) Act, when a secured loan is marked as an NPA, the lender can send a notice asking the borrower to settle the debt within 60 days. If the borrower disagrees or raises objections, the lender must consider these and provide reasons for any rejection within 15 days.
This means that borrowers who might have just missed payments should not assume that banks will let them keep their homes or cars without consequences.
In some circumstances, banks have the right to offset the amount owed against funds in the same bank. However, this doesn’t mean lenders can access accounts the borrower holds elsewhere without restrictions.
Can a Recovery Agent Harass Family Members?
The line between legitimate recovery actions and harassment becomes crucial when recovery agents start making calls.
RBI regulations forbid both regulated entities and their collection agents from intimidating or harassing borrowers during the debt collection process. Such actions include attempts to publicly humiliate someone or invade the privacy of family members, friends, or judges. Collection agencies are also banned from making threatening or anonymous calls, sending inappropriate messages, or persistently contacting borrowers outside of reasonable hours.
“Using abusive language, intimidation, threats of arrest for overdue unsecured debts, and constantly calling to harass borrowers are all violations,” noted Shrivastava.
Borrowers should be aware that collection agencies might reach out to relatives, employers, or co-workers. However, RBI rules specifically stop attempts to publicly shame borrowers or intrude on their families’ privacy. Shrivastava pointed out that simply contacting someone to find a borrower is different from pressuring or shaming them through a third party.
It’s also essential for banks to recognize that they can’t simply distance themselves from the actions of their outsourced collection agencies. The RBI maintains that regulated firms remain accountable for the behavior of their service providers, including collection agencies.
What to Do if You Are Harassed by a Recovery Agent
If a borrower experiences harassment, Shrivastava suggests keeping records of calls, messages, voicemails, and any other evidence.
Complaints should first be directed to the lender using their grievance redress mechanism. If the response isn’t satisfactory, borrowers can escalate their concerns through the RBI’s grievance system, subject to relevant timelines and eligibility.
In cases where there are serious threats, intimidation, or physical violence, it’s advisable for borrowers to contact the police.
Key takeaways for borrowers: Defaulting doesn’t strip the lender of the right to pursue recovery, but it must be done within the legal framework. Banks can seek repayment of dues, and in cases of secured loans, they may eventually enforce collateral. However, they cannot resort to intimidation, humiliation, or illegal asset seizure.
For anyone struggling with EMI payments, the best strategy is to communicate with the lender at the earliest, explore repayment or restructuring options, and maintain a clear record of all conversations. Ignoring recovery notices is generally not the way to go.