Cheniere Energy Expands Corpus Christi LNG Facility Amid Global Demand Surge
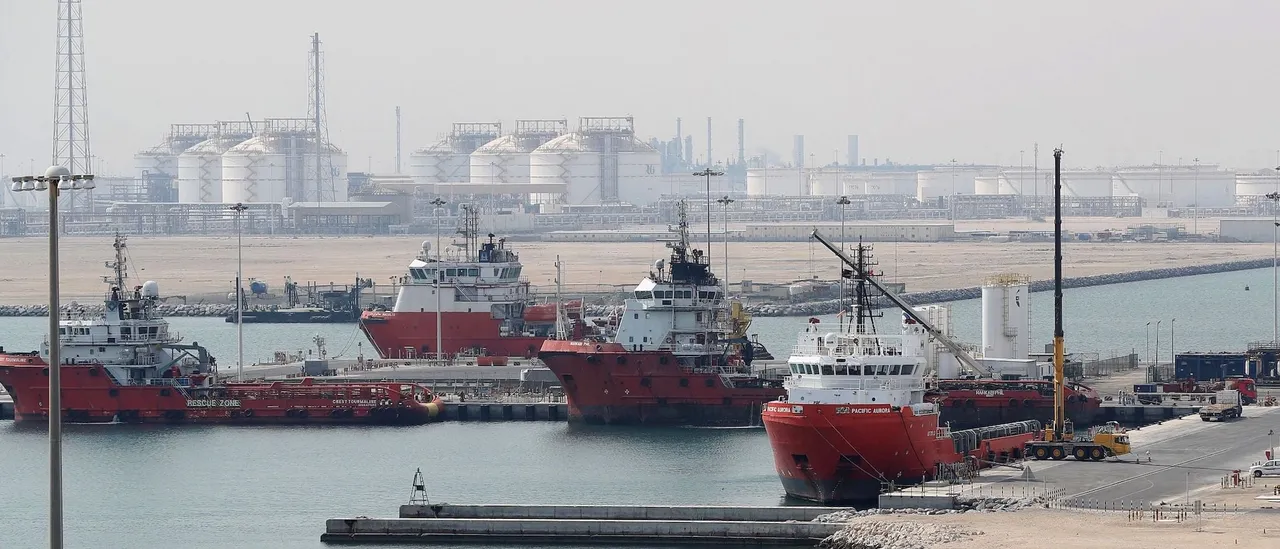
On August 28, 2026, Cheniere Energy announced the completion of Stage 3 of its large Corpus Christi LNG facility, marking a significant expansion in the U.S. liquefied natural gas (LNG) export sector. This development comes at a time when the international demand for U.S. LNG is soaring, largely due to the disruption of most of Qatar’s exports through the Strait of Hormuz after a missile attack by the Islamic Revolutionary Guard Corps (IRGC) in March.
Situated in San Patricio County, just outside Corpus Christi, Texas, the Energy Information Administration (EIA) indicates that the new addition enhances production capacity to 3.1 billion cubic feet per day (Bcf/d). This positions the Corpus Christi LNG facility as the second largest in the United States, just behind Cheniere’s Sabine Pass LNG in Louisiana, which has a capacity of 3.6 Bcf/d. According to the Federal Energy Regulatory Commission (FERC), the total U.S. LNG export capacity now stands at 15.23 Bcf/d, securing its spot as the leading exporter globally.
This achievement is impressive, but does it fully compensate for the lost exports from Qatar? Probably not, and that leaves countries in Europe and Asia racing to secure their energy needs with winter approaching.
However, relief seems to be on the horizon. FERC reports that additional LNG capacity totaling 25.33 Bcf/d is currently permitted and under construction, with firms like Cheniere, ExxonMobil, Venture Global, Woodside, NextDecade, and Sempra leading the charge. These facilities are expected to start operations within the next four years and could more than replace the supply gap attributed to Qatar. While Qatar may not remain offline indefinitely, these companies are banking on a growing LNG market in the long run.
Moreover, there’s a strong belief among these companies that enhancing capacity is crucial, especially given the instability at the Strait of Hormuz and other global chokepoints. This concern was a focal point during the recent Gastech Conference held from September 14-17 in Bangkok.
While Qatar is exploring alternative export routes for its LNG, the options available are both limited and costly. Oil from Persian Gulf nations can bypass the Strait of Hormuz by constructing new pipelines to ports on the Red Sea or Mediterranean Sea. However, getting LNG out requires more complex and expensive methods. Although theoretically, Qatar could transport natural gas to a different country and liquefy it there, this involves significant investments in new infrastructure, which can be risky in terms of securing returns while staying competitive in a market dominated by U.S. exports.
Then there’s the unlikelihood – though not impossible – that normal traffic through Hormuz may never return. Sellers and buyers in the global market can’t afford to remain on the sidelines while they wait to see what unfolds, which likely explains the current rush of new construction in the U.S.
The United States is in a unique position to satisfy the world’s appetite for LNG. With the largest natural gas supplies, the U.S. can meet the growing export demands without jeopardizing domestic availability or significantly driving up prices. While oil, gasoline, and diesel prices have surged since the onset of the Iran conflict, the Henry Hub price for domestic natural gas has remained relatively stable at around $3.00 per MMBtu, a level it has maintained for roughly the past 17 years.
U.S. gas producers have managed to keep production levels constant and even growing, despite having just over 100 active drilling rigs in operation for several years. This number of rigs can be easily increased to address any rises in demand.
Therefore, it seems that in the realm of natural gas and LNG exports, any setback for Qatar may ultimately turn into an opening for the U.S., thanks to its agile and innovative natural gas industry.