A note for new Fed President Kevin Warsh: It’s important not to get swept up in the current narrative. The pandemic isn’t truly behind us, and increasing interest rates right now could be quite unwise.
The inflation chaos that swept through 2022 has clearly left central bankers on edge. It seems like they see inflation risks everywhere. Rising oil prices are one thing they’re worried about—perhaps they’re concerned it will lead to further increases. Then there’s the pressure from AI data centers and the lasting impact of U.S. tariffs that could also push prices up. They seem to think that those who wish for higher inflation might just get what they wish for.
The irony is that many of these financial leaders have a hand in creating the very conditions they now want to fix. It’s hardly a novel thought, and, frankly, it’s a bit stinky. But that’s their mindset.
Consequently, discussions about interest rate hikes are surfacing to tackle what they term “inflationary pressures.” Warsh recently expressed a commitment to having “zero tolerance” for rising inflation. The European Central Bank has already raised its rates, a move that’s being questioned (though modest so far). With the unrest caused by President Trump’s engagement in the Iran conflict, fears of inflation loom larger. Market projections suggest the Federal Reserve might up interest rates by a quarter percentage point by September, a sentiment echoed by the ECB and Bank of England.
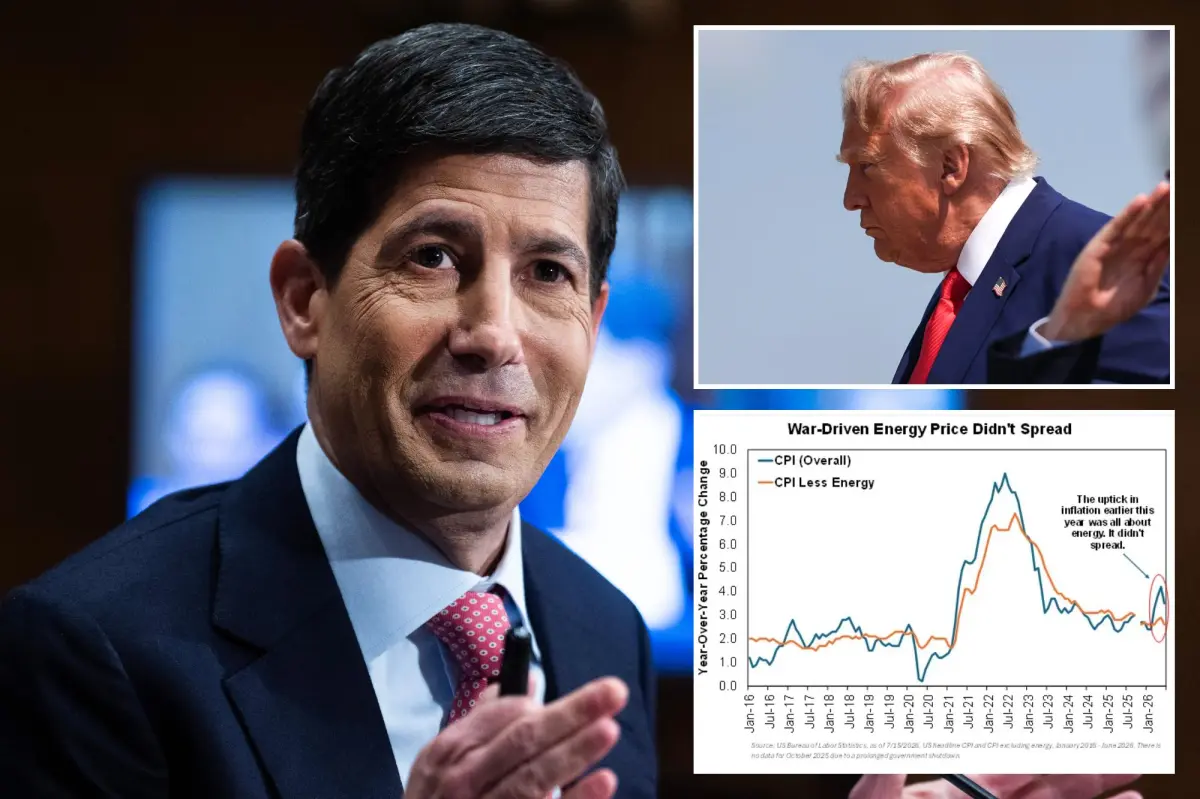
As I mentioned back in May, high oil prices don’t inherently lead to real inflation. Instead, they often result in lowered prices for non-essential goods (just look at the recent drop in luxury handbag sales) while pushing consumers toward alternatives, even as fuel costs climb.
For proof? The U.S. consumer price index (CPI) inflation spiked from 2.4% year-over-year in January to 4.2% in May, igniting chatter about potential rate increases from the Fed. Many anticipated a further uptick in June’s figures, but a surprising drop in energy costs helped slow CPI growth to 3.5% year-over-year.
Oil was the main driver behind the inflation surge and the recent decline. If we exclude energy costs, the CPI in June sat at 2.7% year over year—similar to January’s 2.6% and close to the Fed’s goal. Inflation metrics in Europe and the UK reflect this pattern, showing no significant inflation aside from oil fluctuations.
True, President Trump’s geopolitical decisions add layers of uncertainty. Last week alone, Brent crude oil prices soared past $100 per barrel, but that’s still down from the April high of $138. As I predicted back in March, oil began to drop quickly, moving back toward pre-war levels—likely due to peace negotiations. The recent uptick in July will probably reverse soon. It’s a tricky situation.
Central bankers obsessed with inflation really should reevaluate their focus. The inflation surge of 2022 was not solely due to oil prices. Rather, central banks inflated the money supply during 2020 and 2021, effectively devaluing currency amidst the pandemic.
Milton Friedman pointed out decades ago that inflation happens when too much money pursues too few goods and services. The broad U.S. money supply measure, M4, increased by 6.9% year-over-year in May, aligning closely with the historical average of 5.6%—but still far lower than the staggering 30.4% spike from June 2020. That was a troubling period—thanks to Fed actions. Yet today, the landscape is different.
While minor rate hikes might not drastically impact GDP or stock prices, they can influence lending. As I outlined last July, interest rate fluctuations alter the yield curve—the gap between short-term and long-term rates. Banks often borrow short-term to fund long-term loans. When short-term rates rise above long-term ones, lending slows, which can signal recession.
Currently, the U.S. yield curve was at 0.5 percentage points but is slightly improved at 0.8. Optimistically, the UK shows a rise from 0.7 to 1.1 points, which is also positive news. In Europe, where rates are climbing, the yield curve has narrowed slightly, but there are no immediate issues. For now, policymakers hold the reins on these decisions.
However, sharp interest rate hikes could flatten or invert the global yield curve, threatening lending and resulting in economic slowdowns—affecting GDP and stock markets. We haven’t seen that yet, but Warsh and his team ought to take heed: they need to ease up on tightening measures.
They should really reconsider their thinking.