Market Update: Concerns Over Tech Spending Impact Futures
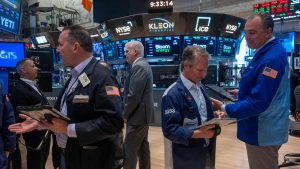
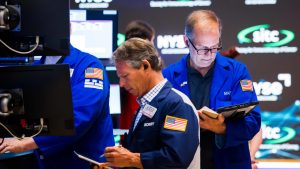
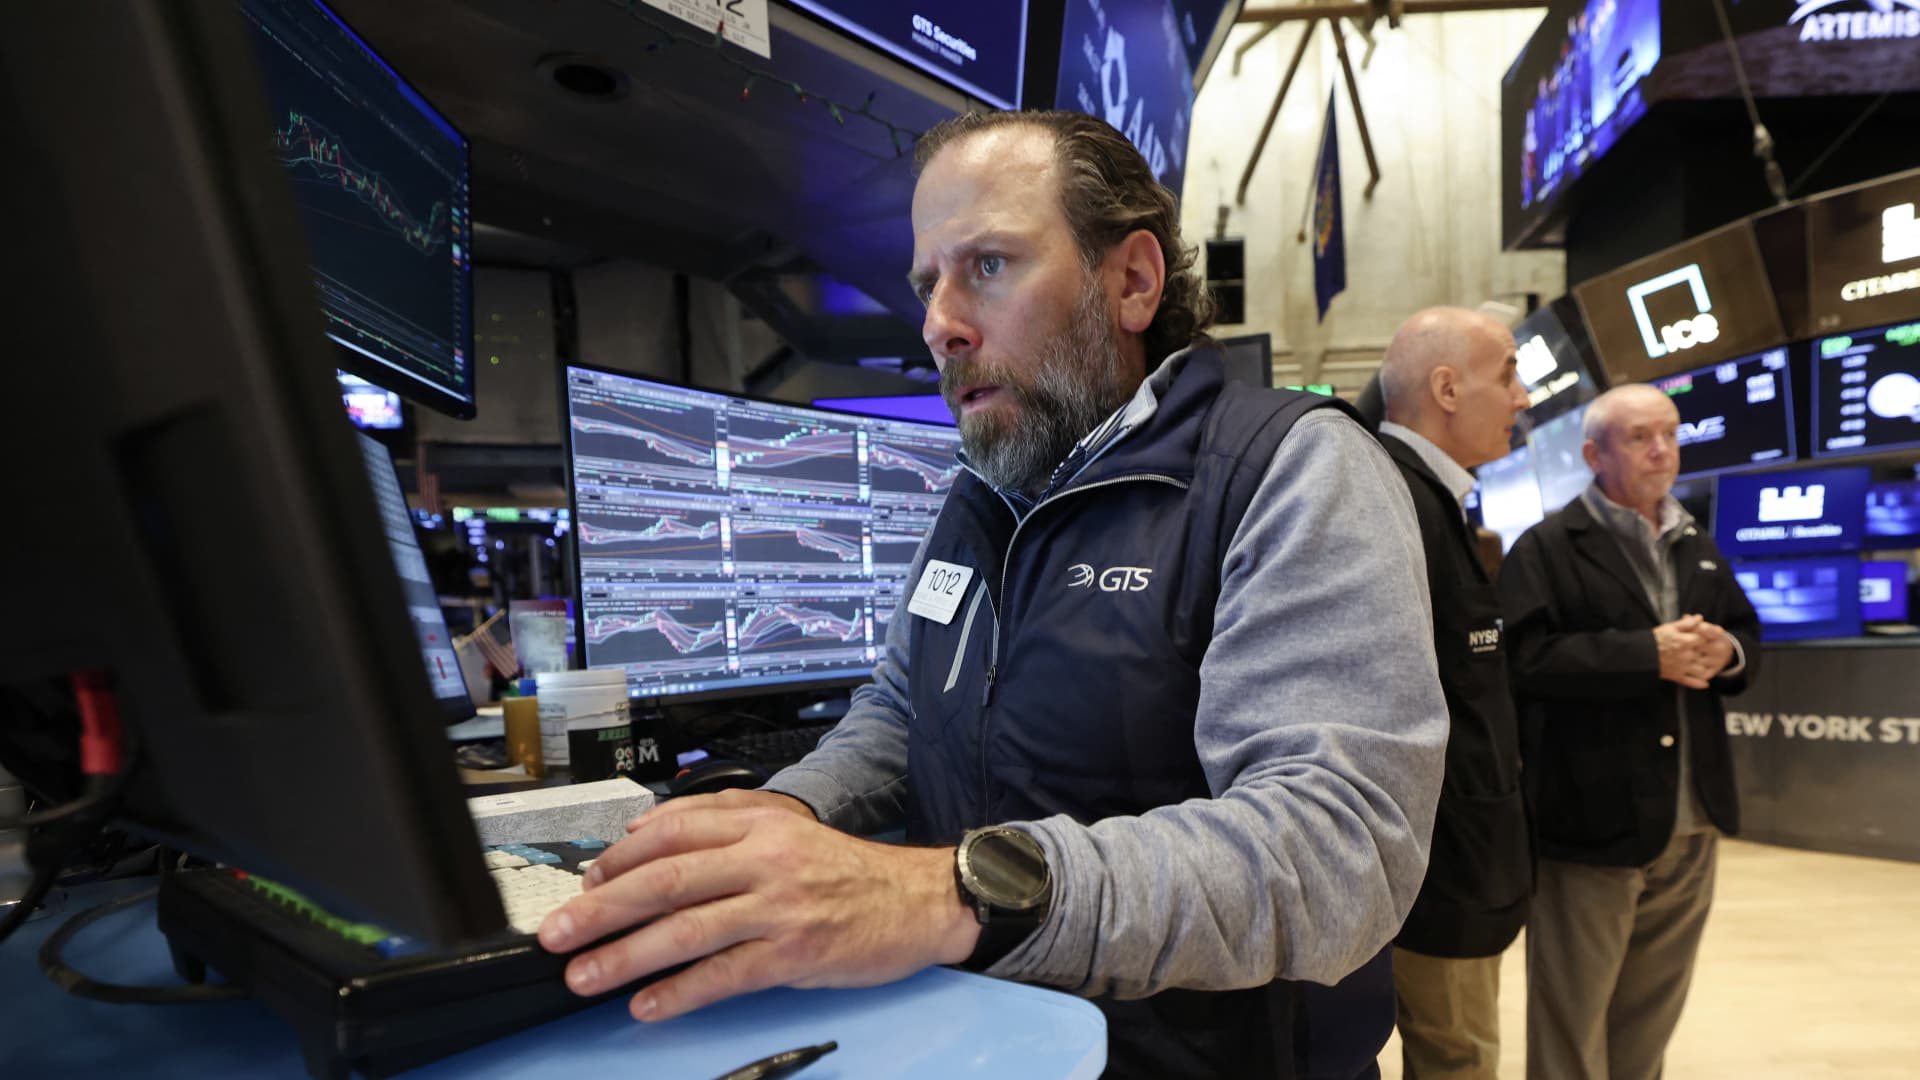
On April 30, 2026, at the New York Stock Exchange (NYSE), traders reacted to a dip in futures for the S&P 500 and Nasdaq-100. The decline stemmed from growing worries about tech companies overspending on artificial intelligence. Traders were also looking ahead to upcoming earnings reports and economic data after a rough previous day.
S&P 500 futures fell by 0.2%, and those linked to the Nasdaq-100 were down by 1.1%. In contrast, futures for the Dow Jones Industrial Average gained 150 points, translating to a 0.3% increase.
CoreWeave’s shares dropped 5% in premarket trading, extending losses from the previous session where the stock fell over 15%. Investors seemed anxious about the company’s increasing borrowing related to its AI expansion, and this raised concerns about corporate bond yields for CoreWeave as well.
Additionally, sources indicated to CNBC that Anthropic’s revenue grew to $16.8 billion in the third quarter. Yet, some traders expressed concerns that such growth might not suffice to justify the substantial gains seen by chipmakers.
Tech giants like Micron Technology and Advanced Micro Devices fell by 4% and nearly 3%, respectively. Other companies followed suit; Sandisk dropped 4%, while U.S.-listed shares of Sk Hynix decreased by 7%. Interestingly, South Korea’s Kospi index also saw a decline of over 7% overnight.
Despite the tech downturn, positive movements were noted in other sectors. Retailer Walmart’s shares rose by 3%, and pharmaceutical company Merck saw an increase of more than 1%.
Wall Street was still recovering from a significant drop the day before, with the Nasdaq Composite experiencing its largest one-day decline since July 23. The Dow and S&P 500 closed lower as well.
Adding to the unease, there were worries about potential aggressive tightening of monetary policy by the Federal Reserve, especially after September’s consumer prices showed a faster-than-expected increase year-over-year.
“Inflation is definitely heating up,” noted Jamie Cox, managing partner for Harris Financial Group. He pointed out that while the origins of inflation are becoming clearer, resolution might require ending two ongoing conflicts. Cox mentioned the Federal Reserve’s previous misstep of labeling COVID-era inflation as temporary and suggested they might be misjudging the current energy supply shock as well.
More inflation data is anticipated on Thursday, with the September producer price index set to be released at 8:30 a.m. ET, along with new retail sales figures and weekly jobless claims.