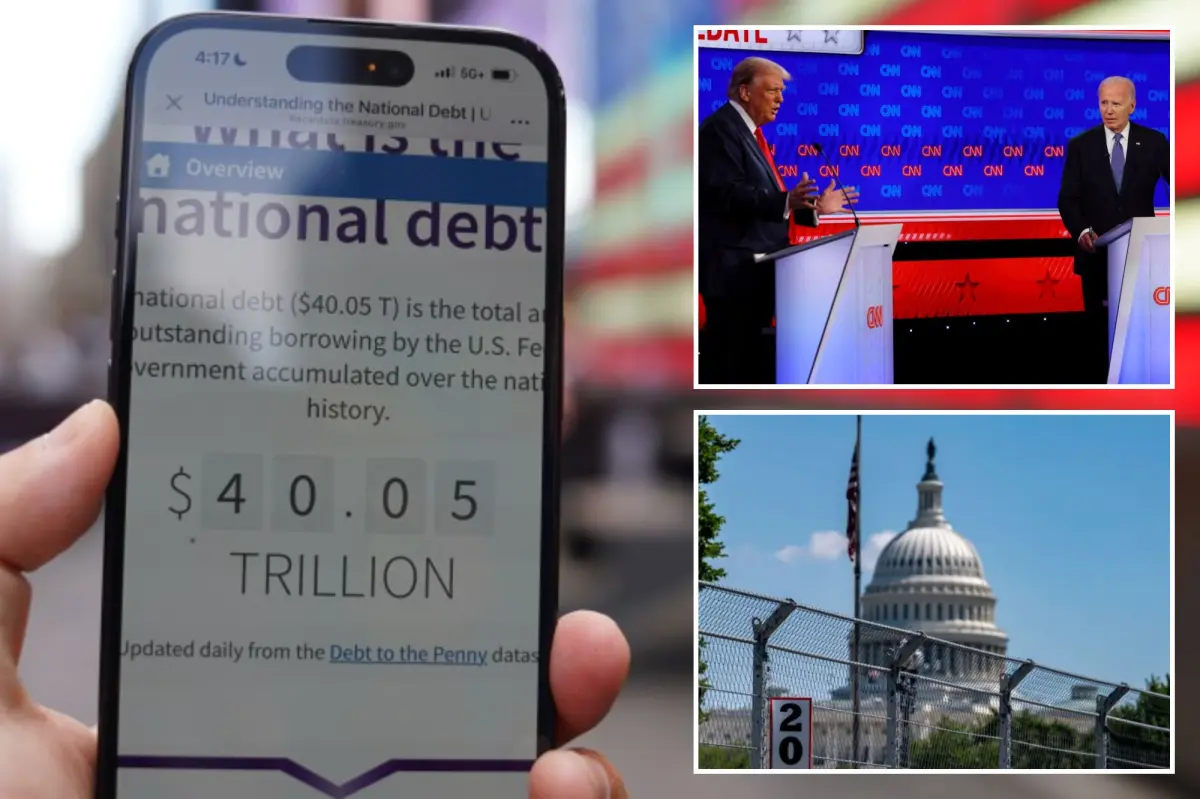
The U.S. has crossed the $40 trillion mark in national debt for the first time, according to the Treasury Department’s announcement on Wednesday. This raises new concerns about a potential fiscal crisis, as spending on social programs and interest payments significantly outstrip revenue, which has been suppressed due to tax cuts.
The latest report indicates that as of Tuesday, the national public debt stands at $40.047 trillion. This includes $32.266 trillion in Treasury securities held by the public and $7.782 trillion in debt owned by the government itself.
Federal borrowing has more than doubled within less than ten years, increasing from $19.95 trillion back in January 2017, around the time President Trump took office.
About one-third of this debt increase is attributed to the significant borrowing measures taken during the two years of pandemic-related government support from both President Trump and President Biden. The remaining debt growth has come from various fiscal policy decisions made by the two administrations and ongoing tax and spending issues.
Budget watchdog organizations had been predicting this debt threshold breach for some time and have expressed serious concerns that an outright debt crisis could be on the horizon unless lawmakers take action to address what they view as an unsustainable fiscal path. This could mean raising taxes, cutting spending, or possibly both.
“Carrying $40 trillion in debt isn’t just something reflected on paper; it has tangible effects on the economy and influences people’s financial situations,” noted Maya McGuineas, chair of the bipartisan Committee for a Responsible Federal Budget.
“The heavier our borrowing, the more we exacerbate inflation, which in turn complicates our budget priorities and increases our vulnerability to both domestic emergencies and international disruptions,” Treasury Secretary McGinius stated shortly after the Treasury released its figures.
He pointed out that the debt crossed the $40 trillion mark in less than five months after hitting $39 trillion. It’s noteworthy that it took fewer than two decades for the debt to quadruple since reaching $1 trillion for the first time in 1981. McGuineas emphasized how predictably the financial decline of powerful nations has become.
It seems that America’s global creditors are already quite attuned to the situation.
The yields on long-term Treasuries recently peaked at their highest in nearly two decades, following a $25 billion 30-year Treasury auction marked by the highest yield since 2021. This reflects investors’ demand for greater compensation against a backdrop of large U.S. debt issuance.
Treasury Secretary Scott Bessent announced measures to double the size of buybacks for 10- to 30-year bonds to a minimum of $4 billion per operation in an effort to lower long-term bond yields.
This week, the term premium for the 10-year Treasury — an indication of risk associated with holding such securities for over a decade — rose to its highest level in more than 12 years.
In spite of this, interest from foreign investors, who hold almost a third of all Treasuries, has been declining over the last year. This trend may lead to heavier flows of bonds to more price-sensitive buyers, which could escalate market volatility, according to John Canavan, chief financial markets analyst at Oxford Economics.
Spending during the pandemic and beyond
Last week, the Treasury reported the fourth-largest monthly deficit in U.S. history ($432 billion in July). This was influenced by three consecutive months of negative customs revenue due to tariff refunds and rising costs associated with Social Security and Medicare benefits for seniors. Notably, the deficit for the first ten months of fiscal 2026 has already surpassed the entire deficit of fiscal 2025, with two months remaining in the fiscal year.
During his two terms, Trump defended large spending practices, seemingly ignoring the dwindling number of Republican advocates for fiscal restraint. The public debt grew by $7.8 trillion during Trump’s first term, with more than half of this debt accrued during the last nine months when pandemic responses were underway.
After Trump resumed the presidency in January 2025, the national debt increased by $3.8 trillion, totaling an $11.6 trillion rise over both his terms.
Under Biden’s administration, the public debt rose by $8.4 trillion, a figure also fueled by significant recovery spending relating to COVID-19, alongside investment in infrastructure and clean energy initiatives championed by Democrats.
The Committee for a Responsible Federal Budget estimates that the policy choices made by Trump and Biden have led to a federal debt increase beyond what would have occurred under existing spending laws at their respective times of taking office.
For instance, Trump’s significant second-term legislation, known as the One Big Beautiful Bill Act, is projected to add an extra $4.7 trillion to the debt, according to the nonpartisan Congressional Budget Office.
Trump has presented his second term as one dedicated to cutting costs, including the early execution of job cuts ordered by the non-governmental Department of Government Efficiency. However, many of these budget cuts target “discretionary” programs, which represent the smallest part of the federal budget.
The Committee for a Responsible Federal Budget highlights that the fiscal decisions made by both Trump and Biden have significantly contributed to the federal debt exceeding what it would have been under existing spending laws upon their respective inaugurations.
The U.S. spends approximately $7 trillion each year, with around 60% allocated to obligatory programs like Social Security, Medicare, Medicaid, and veterans’ care, which typically grow in accordance with living costs.