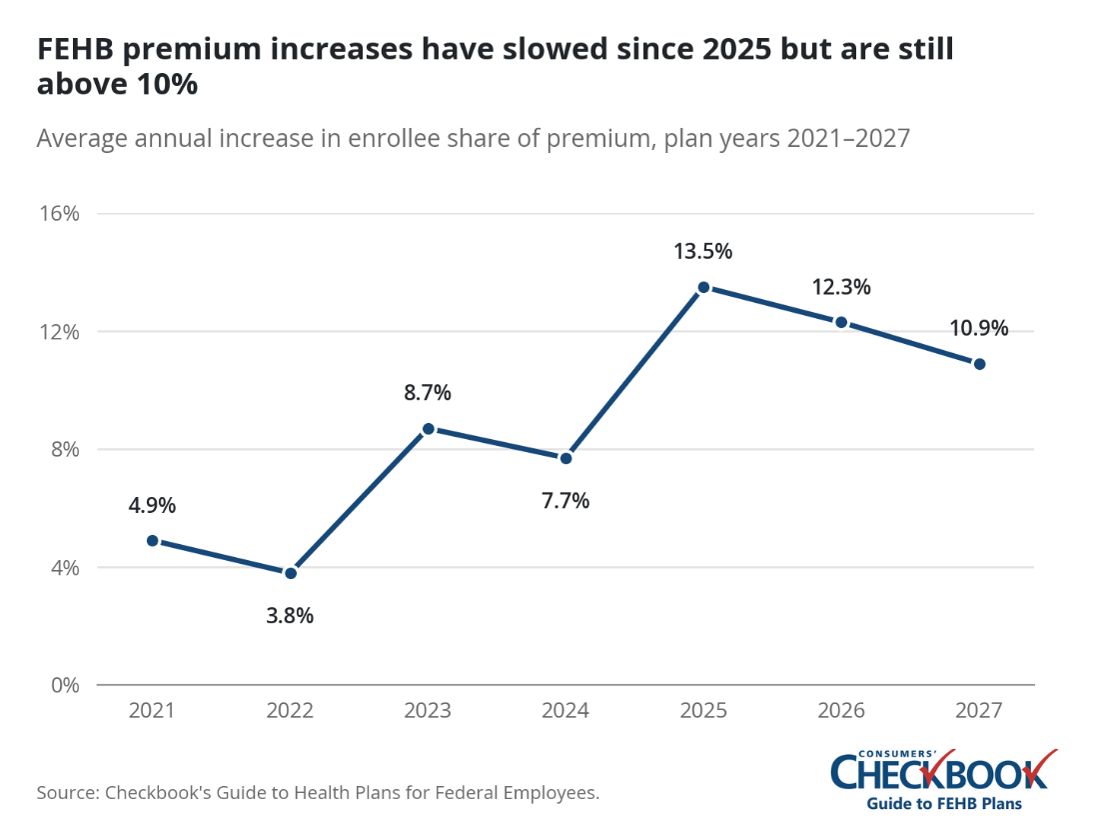
Federal employees and retirees will be facing a third consecutive year of significant increases in Federal Employees Health Benefits (FEHB) premiums, with a projected average rise of 10.9% in 2027. This uptick, while less severe than previous years, is attributed by the Office of Personnel Management to escalating costs within the healthcare sector. Notably, there’s been a spike in the use of mental and behavioral health services, alongside heightened spending on prescription medications, particularly GLP-1 weight loss drugs.
As we gear up for Open Season, I’ll provide insights into recent FEHB premium hikes, how these changes are distributed among different plans, and offer tips for enrollment, especially for those with two-person families. I’ll also touch on Postal Service Health Benefits (PSHB) premiums and what to expect from Federal Employees Dental and Vision Insurance Program (FEDVIP) options.
Recent History of FEHB Premium Increases
Just five years ago, the typical enrollee was contributing around 5% of the premium costs.
Healthcare inflation usually outpaces general inflation trends, signaling that federal employees and retirees might need to brace for ongoing premium increases in the future.
It’s worth noting that these hikes aren’t exclusive to FEHB; plans under the Affordable Care Act are seeing a median premium increase of 15% for 2027, while large-group employer plans are expected to rise by about 9.5% next year.
Changes in FEHB Premiums for 2027
Interestingly, not all plans will follow suit. Among the 117 FEHB plans available in both 2026 and 2027, 20 plans will actually see a decrease in self-only premiums, 5 plans will remain stable, while 53 will rise below the average increase of 10.9%, and 39 will see increases exceeding this average.
For instance, there’s a marked reduction for the M.D. IPA (JP1) plan in Washington, D.C., which is seeing a 46% drop in premium, equating to a savings of $2,626 for self-only enrollees. Conversely, the MHBP Standard (454) will witness a substantial rise of 63%, an additional $1,540 for self-only participants.
If you’re curious about how your plan is adjusting next year, it’s definitely a good idea to check, particularly since costs are expected to rise, even if you’re satisfied with your current coverage. You’ll soon be able to find updated premium information on the OPM Open Season page or in the back of the official FEHB brochure once it’s issued. There might be alternatives that offer better value.
Approximately two-thirds of federal employees are enrolled in Blue Cross Blue Shield (BCBS) plans, which include Standard, Basic, or FEP Blue Focus.
Both Basic and Standard plans have increased at rates below the average, whereas FEP Blue Focus has experienced a slight uptick.
If you’re enrolled in a BCBS plan, have you compared the alternatives lately? Open Season presents a great chance to reassess whether your current choice is still the right one. There are notable differences between the plans. For example, Standard remains the only option that allows you to:
- See out-of-network providers,
- Access mail-order prescription drugs (Basic is limited to mail-order coverage for annuitants with Part B),
- Utilize skilled nursing care benefits,
- And receive IVF coverage up to $25,000 annually.
For those who are on the Standard plan but don’t need these benefits, switching to Basic or FEP Blue Focus could mean significant savings. Families opting for Basic might save around $2,843, while switching to FEP Blue Focus could save up to $8,360.
Self-Plus-One vs Self & Family Enrollment
Married couples and two-person families have the choice between self-plus-one or self & family enrollment. Typically, self-plus-one is cheaper, yet there are 38 FEHB plans where self & family is more affordable.
This could lead to considerable savings. For example, a couple considering certain Kaiser High plans in Washington, D.C., Fresno, or northern California could save $76.29 biweekly by enrolling as self & family instead, totaling a yearly savings of $1,984.
To view these differences, look at the last page of the official FEHB brochure for the enrollee share of premium and choose the more economical enrollment option. The benefits remain unchanged regardless of how you enroll.
PSHB Premiums
There’s a silver lining for Postal Service employees and retirees: the overall premium increase for PSHB plans is expected to be lower at 8.2%, a reduction from the previous 11.3% rise.
FEDVIP Premiums
FEDVIP dental and vision plan premiums will continue to rise at a comparatively slow pace. For 2027, dental premiums will go up by an average of 1%, while vision premiums will see a 1.6% increase.
In Summary
In 2027, FEHB premiums are rising by an average of 10.9%, with numerous plans seeing even higher jumps. While premium costs are just one aspect of health plan selection, they inevitably impact your budget, making it crucial to review changes to your current plan and explore possibly better options.
Keep in mind that your total healthcare costs extend beyond premium alone. You should consider additional out-of-pocket expenses. A comprehensive guide will be released before Open Season to help rank FEHB plans based on estimated yearly costs, which combine premiums and expected out-of-pocket expenditures tailored to your profile.
Don’t forget to verify in-network providers, prescription drug coverage, and any specific benefits that matter to you before making a switch.
The 2027 FEHB Open Season is set from November 9 to December 14, allowing ample time for you to compare and make choices tailored to your needs.
I’ll be answering your questions regarding FEHB during Federal News Network’s Open Season Exchange on November 9. If you have inquiries about FEHB coverage or how Medicare integrates with it, feel free to submit them, and we’ll do our best to address as many as possible.