Credit Unions and Card Rewards
Credit unions have already built a foundation of trust with their members. To encourage more card usage, they might consider offering something concrete, like rewards for everyday spending.
This potential is highlighted in the third main point of a report titled “The Top-of-Wallet Challenge: Why Trust Alone Is Not Enough to Drive Card Usage,” part of the July 2026 Credit Union Tracker® by PYMNTS Intelligence, in partnership with Velera. The findings suggest that while strong relationships and high levels of satisfaction exist, they don’t always make credit union cards the preferred choice for members. Introducing rewards could serve as a practical solution to bridge that gap. Trust provides credit unions with an opportunity, while attractive card benefits could encourage members to use their cards more often. Essentially, it seems that enhancing the value members receive each time they transact could lead to greater spending overall.
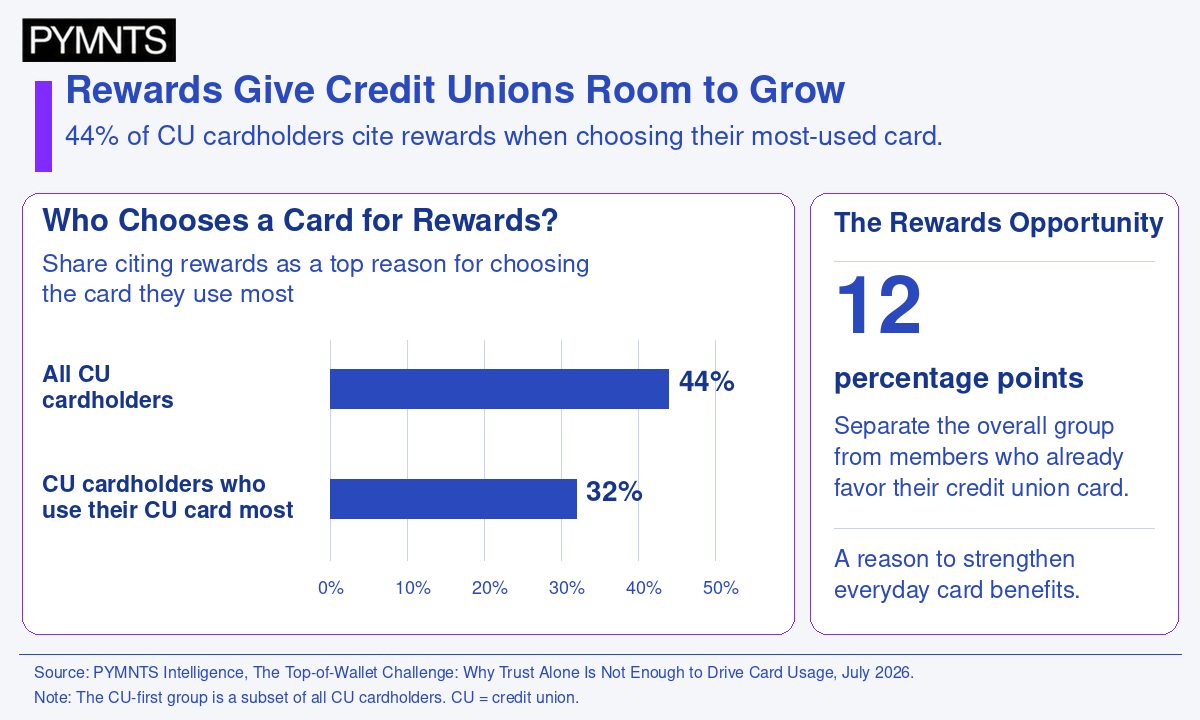
- Rewards play a significant role in cardholder choices. About 44% of credit union cardholders identify rewards as a primary factor in choosing their card. For those who already mainly use their credit union card, this number drops to 32%, indicating a 12-point difference. This discrepancy suggests that there’s potential for credit unions to target those members whose decisions are more influenced by rewards. This group also values features like contactless payments and customer service, providing a solid starting point for expanding card programs.
- Credit unions lag behind national banks in becoming the first-choice card for users. According to the report, only 48% of credit union customers prioritize their cards, compared to 69% for national banks. This gap remains significant even though 61% of members consider their credit union their main financial institution. Thus, having a primary relationship doesn’t necessarily dictate which card is chosen at checkout. The key is to connect the established relationship with benefits that members can easily recognize and appreciate.
- Improved rewards could encourage 41% of consumers to switch their secondary card. Research from Mastercard included in the report indicates that many consumers would elevate a different card to primary status for better rewards and benefits. This highlights the shifting landscape of payment preferences. Credit unions could customize their approach, as younger members tend to seek rewards aligned with financial goals, while small-business members may prefer budgeting tools associated with other institutions’ cards.
Additional insights reveal that credit unions possess significant strengths to leverage. Among consumers who consider their credit union as their primary bank, a remarkable 87% report being very or extremely satisfied. Furthermore, credit union cards surpass national banks in terms of usage for utility bills, with 37% compared to 34%, and for internet and mobile services at 35% versus 33%. By combining these established relationships with appealing rewards, credit unions could significantly increase their members’ everyday spending.