The Weekly Wrap: Greenland Is Ours!
Happy Friday, everyone!
This week, it seems the U.S. has effectively claimed Greenland. Take that, all you persistent naysayers! The bond market, feeling a bit ignored amid the buzz about AI doom, decided to shine bright, climbing to a notable five percent before seemingly taking off on its own. Meanwhile, the economy is on a roll—core capital expenditures have seen a double-digit increase compared to last year. And, what’s more, even the services sector is finally joining the growth party.
Let’s dive in.
This Land Is Greenland, Just Like Our Land
When President Donald Trump first eyed Greenland, his critics were quick to denounce him as out of touch. “It’s nuts. It’s just crazy,” said Democratic Representative Jim Himes in an interview.
Trump’s reasoning wasn’t totally outlandish, though. “We need Greenland for national security reasons,” he explained back in January. “We’re talking about safeguarding the free world. Just look around—there are Chinese ships and Russian vessels everywhere. We can’t let that continue.”
But his critics just wouldn’t let it go. Stephen Colbert, famously, lampooned Trump for wanting to lay claim to a “frozen gravel pile,” even suggesting this could lead to a conflict with NATO.
Here’s a glimpse of the back-and-forth from the media at that time:
Anderson Cooper on CNN: “European leaders seem focused on de-escalating and reasoning with Trump. Do you think that will work?”
Senator Ruben Gallego (D-NM): “No, and it’s clear—he’s lost it. He’s only thinking of his own interests.”
Cooper: “You genuinely think he’s not sane?”
Gallego: “Yes! At what point do we recognize that something is seriously wrong? He’s threatening our NATO allies. This isn’t rational.. He’s damaging our global standing because he’s being childish. Let’s accept what we see; it’s not logical.”
Well, to say no one listened is a stretch. We paid attention, even calculated how much it might cost to buy Greenland—around $300 billion, we thought. Leasing it seemed a better idea, perhaps around $2.5 billion a year.
But it turns out Trump managed to secure an even smarter deal.
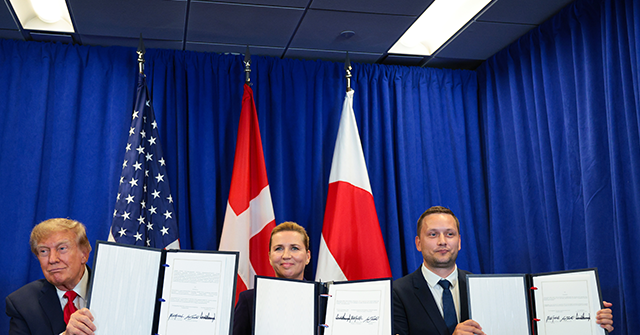
The agreement made on September 22 between the U.S., Denmark, and Greenland is a significant strategic victory. The U.S. now has permanent basing rights, access, and overflight privileges, with no expiration date—even if Greenland decides to break away from Denmark. This addresses a significant flaw in the old 1951 arrangement, which was tied to NATO agreements that could have ended. We didn’t actually buy Greenland, but we have the freedom to operate there indefinitely.
The agreement also opens the door to developing two more U.S. military bases and introduces a proposed “Golden Dome” missile defense system. It prevents countries like China and Russia from establishing military bases in Greenland and restricts sensitive investments by non-allied nations, safeguarding the island’s mineral resources as new shipping routes open in the Arctic.
This setup is better than any purchase or lease. Why buy the cow when you can have the milk for free?
Concerns Over the Bond Market
While many were worried that artificial intelligence—sorry, superintelligence—might lead to our downfall, the bond market quietly stepped in to remind us of its power.
The yield on the 10-year Treasury has jumped 50 basis points in just a month, nearing 5.2 percent by Friday. Market analysts were quick to predict doom, viewing the five percent mark almost like a critical boundary that once crossed could spell chaos. It hadn’t been breached since 2007—19 years ago! Every small increase stirred panic. Headlines claimed a “bond market rout” was getting worse.
Yet on Friday, even as yields rose, major equity indices were trending upward for the day and were higher than the previous week. It seems the feared doom was more a product of over-the-top reactions from some analysts.
One theory claiming the bond issue was alarming suggested it showed escalating fears of inflation. This, however, appears to be a misjudgment. While short-term consumer inflation expectations are up, mainly due to rising gas prices, market-based inflation expectations have hardly budged. Inflation breakevens remain stable, where they’ve been for years. The rise in nominal yields can largely be attributed to real yields climbing.
Another narrative suggested rising yields indicated global investors were shying away from U.S. debt. But that seems to be more wishful thinking. Demand for U.S. equities has risen significantly, and the appetite for Treasuries remains strong. Moreover, there’s no indication that growing AI-related debt is pushing out Treasuries; instead, it’s counter to what deficit hawks feared—that public debt would suffocate private investment.
What’s really occurring is straightforward. The yields on long-term bonds are shaped by expectations concerning short-term yields—and, in the end, by anticipated Fed policy. With a booming economy, partly thanks to a surge in business investments linked to AI and Trump’s supportive tax reforms, the Fed can adjust policy rates upward without hindering growth. In essence, expectations for growth and investment returns are on the rise, and bond yields reflect that.
Significantly, bond yields can now truly mirror economic expectations as they haven’t for nearly two decades because Kevin Warsh has freed the Fed from its previous constraints. In the past, rapid yield increases brought a strong Fed response to push them back down through guidance and large asset purchases. Now, the Fed has let rates rise naturally, allowing them to seek market balance. Quantitative easing has ceased.
The Economy Is Thriving
“US business activity growth picked up for four consecutive months in September, reaching its fastest rate in over five years,” reported S&P Global this week.
The composite flash PMI shot up to 58.4, an increase from August’s 56, marking the highest level in 62 months—surpassing even the rosiest expectations. The manufacturing index surged to 57.0 from the previous month’s adjusted 53.9. Earlier forecasts expected it to stabilize. The services index hit 58.7, up from 65.6, defying predictions of a downturn.
As Chris Williamson, chief business economist at S&P Global Market Intelligence, put it:
“US business is booming, with output at the fastest pace in five years this September. Historical data suggests this could indicate annual growth around 5%, with a 4% increase projected for the third quarter. Putting this growth surge in context—besides the boom post-COVID lockdown—this is the most significant progress since early 2015. Both manufacturing and services are clearly flourishing right now.”
The hard data backs up this boom. August’s durable goods orders showed a 1.6 percent increase in non-defense, ex-transportation orders for the month, on the heels of previous gains of 0.6 percent in July and 1.7 percent in June. Compared to last year, these core capital goods orders are up 10.6 percent.
As of Friday, the Atlanta Fed’s GDPNOW projects economic growth at 5.0 percent for the third quarter.
However, consumer sentiment continues to lag. It’s strange—so many people feel dismal about an economy that’s otherwise thriving.
A Look Back: Henry Ford and the Weekend
On September 25, 1926, Henry Ford declared that his factories would switch to a five-day, 40-hour workweek.
The eight-hour workday was already well established at Ford, as it had been introduced in January 1914 along with the notable $5 daily wage, cutting shifts from nine hours to eight. But in 1926, the new change was eliminating Saturday work.
Ford had piloted the shorter week in certain departments earlier that year before officially adopting it. Back then, a six-day workweek was the norm in American industries, with many workers working much more than 48 hours weekly.
In essence, Ford was creating the modern weekend. Workers would no longer just have Sunday off; now, Saturday was also a day of rest. It was the first time Friday marked the true end of the workweek for so many laborers.
For Ford, this wasn’t a charitable gesture. He believed that more time off would lead to increased spending. People would buy clothes for outings, travel, take on hobbies, and, notably, drive cars. In his view, a mass-production economy required leisure time to really thrive; without more than just Sunday off, there was little incentive for workers to own vehicles.
Interestingly, the announcement coincided with the anniversary of the first Model T rolling off the assembly line in Detroit in 1908.
Significantly, this development of the weekend was not mandated by the government. The federal standard of a 40-hour workweek wasn’t established until the Fair Labor Standards Act of 1938, which began implementation by 1940.