Warsh’s Keynote at Jackson Hole Addresses Inflation and Future of Monetary Policy
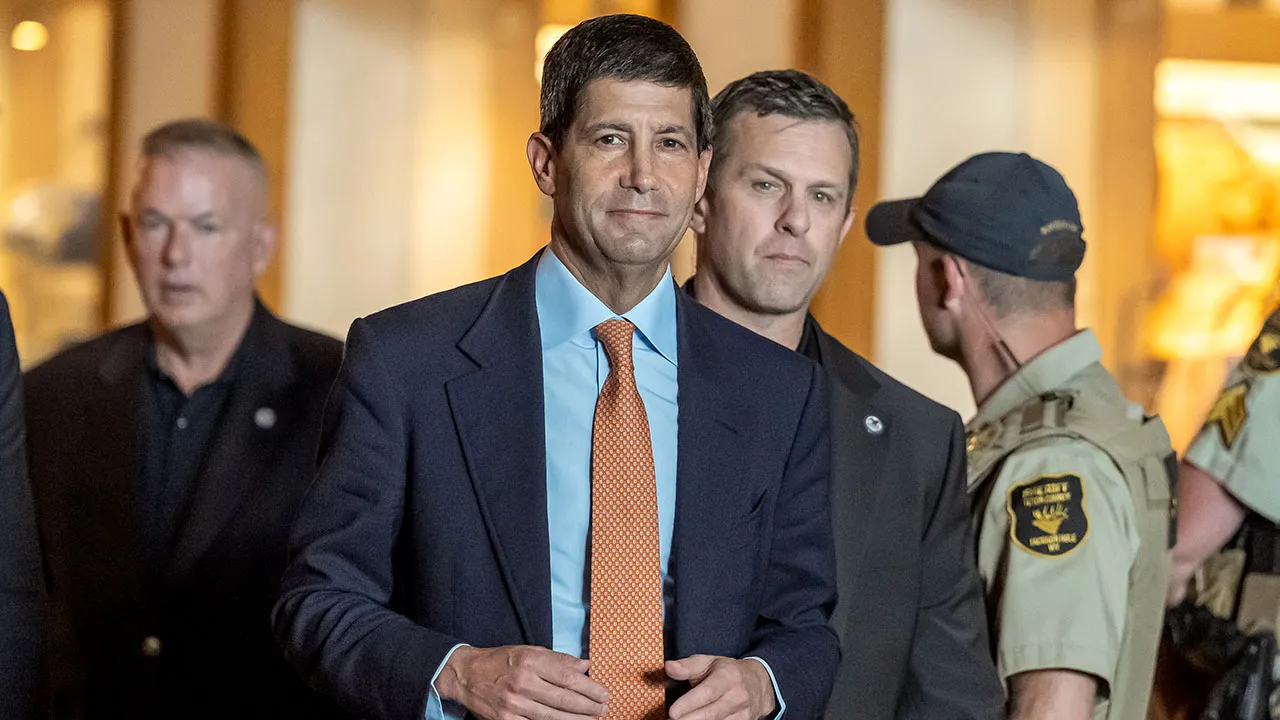
On Friday, Federal Reserve Chair Kevin Warsh gave his inaugural keynote speech at the annual monetary policy conference held in Jackson Hole, Wyoming. The event comes amid significant uncertainty regarding inflation and what direction policymakers might take regarding interest rates.
In recent months, the Federal Reserve has opted to maintain steady interest rates across its five meetings, all while grappling with ongoing inflation that continues to drift away from the central bank’s targeted 2% rate, particularly influenced by the war in Iran.
This annual gathering in Jackson Hole typically provides central bank leaders a platform to reframe expectations around monetary policy and discuss the evolving economic landscape, both in the short and long term.
Focus on Inflation and Policy Direction
Warsh has expressed reservations about providing so-called forward guidance regarding future monetary policy moves. This has led some analysts and observers to hope for greater clarity on how he interprets incoming data and the trajectory of the economy.
In outlining his speech, Warsh humorously suggested that it could serve as a rough outline or map rather than actual guidance. He indicated plans to discuss the practice of forward guidance and the interaction between the markets and the central bank, along with the ramifications of artificial intelligence (AI) on the economy and foundational principles behind monetary policy.
“With the unchanging picture of the Tetons as our backdrop, we are here to survey an economic landscape that is anything but static,” he remarked, indicating that we stand at a pivotal moment in history.
Warsh noted that advancements in AI have exceeded expectations, suggesting the potential for significantly higher growth as vast investments flow into AI-related infrastructure. “A sort of super Moore’s law appears to be developing,” he observed.
He added that the Fed has formed an AI task force to review aspects such as AI’s effects on productivity and employment, as well as tracking development within the industry and returns across key sectors driving it.
Concerns Over Monetary Policy Guidance
He stressed that in normal circumstances, forward guidance should be “limited and circumscribed,” as it risks creating confusion while aiming for transparency.
Warsh found it vital for the Fed to maintain a humble perspective. “Our tools are powerful, and we have a crucial role in the economy,” he said, but cautioned against a reliance where market participants look primarily to the Fed for direction.
“If we misjudge inflation and the economy, it’s hardworking Americans who ultimately bear the brunt of those mistakes,” he noted.
Emphasizing Price Stability
As he discussed monetary policy principles, Warsh reiterated that data must be relevant, accurate, and actionable for the Fed’s functions. The overall aim is to align aggregate demand with aggregate supply, even if finding the right balance can be tricky.
“Make no mistake, the Fed’s target of 2% price stability is non-negotiable. It’s our responsibility to ensure stable prices, no excuses,” he emphasized. He reaffirmed the dual mandate of the Fed, articulating that high inflation could harm economic prosperity, thus the two objectives should complement rather than contradict each other.
He also noted the importance of short-term interest rates as a primary tool, mentioning that unconventional policies should be reserved for genuine crises rather than common practice.
Warsh stated that the central bank must closely monitor its impact on money supply to gauge its effects on financial conditions and prices. A well-calibrated Fed is more likely to achieve its objectives and remain accountable to the public.
In terms of the economic outlook, he referred to the Federal Open Market Committee’s view in July, highlighting stable labor markets and solid output, while still recognizing that inflation remains a concern. “From where I sit, I’m encouraged by the economy’s performance, which seems to be strengthening,” Warsh remarked, adding that both Main Street and Wall Street have shown resilience amid recent economic challenges.
Future Focus on Inflation
As for the economy, Warsh observed that firms in the S&P 500 have seen profits exceed 20% over the past year, with profit margins being relatively high and low market volatility. He acknowledged strains in sectors like housing and agriculture but maintained that overall financial conditions weren’t overly restrictive.
The labor market appears stable, with the unemployment rate at 4.1%, and Warsh suggested that low turnover rates reflect the effective matching of job seekers and employers in the post-pandemic world. Still, he acknowledged challenges for specific demographics, like recent graduates.
“As of now, I find the labor markets generally support full employment,” he stated. However, on inflation, Warsh pointed out the more troubling figures, noting the PCE inflation rate at 3.7% year-over-year, indicating that inflation remains above the Fed’s 2% target. “Our main focus must right now be on prices,” he concluded.
Despite previous declines in PCE and CPI inflation, Warsh observed that recent improvements have been modest, and trends do not indicate significant progress. He insisted that the central bank is responsible for the prolonged period of elevated inflation and stated that assurance is needed that underlying inflation trends are moving towards the objective definitively and promptly.
In closing, he expressed gratitude for his role at the Federal Reserve and the support he’s received in his early days back in this position.