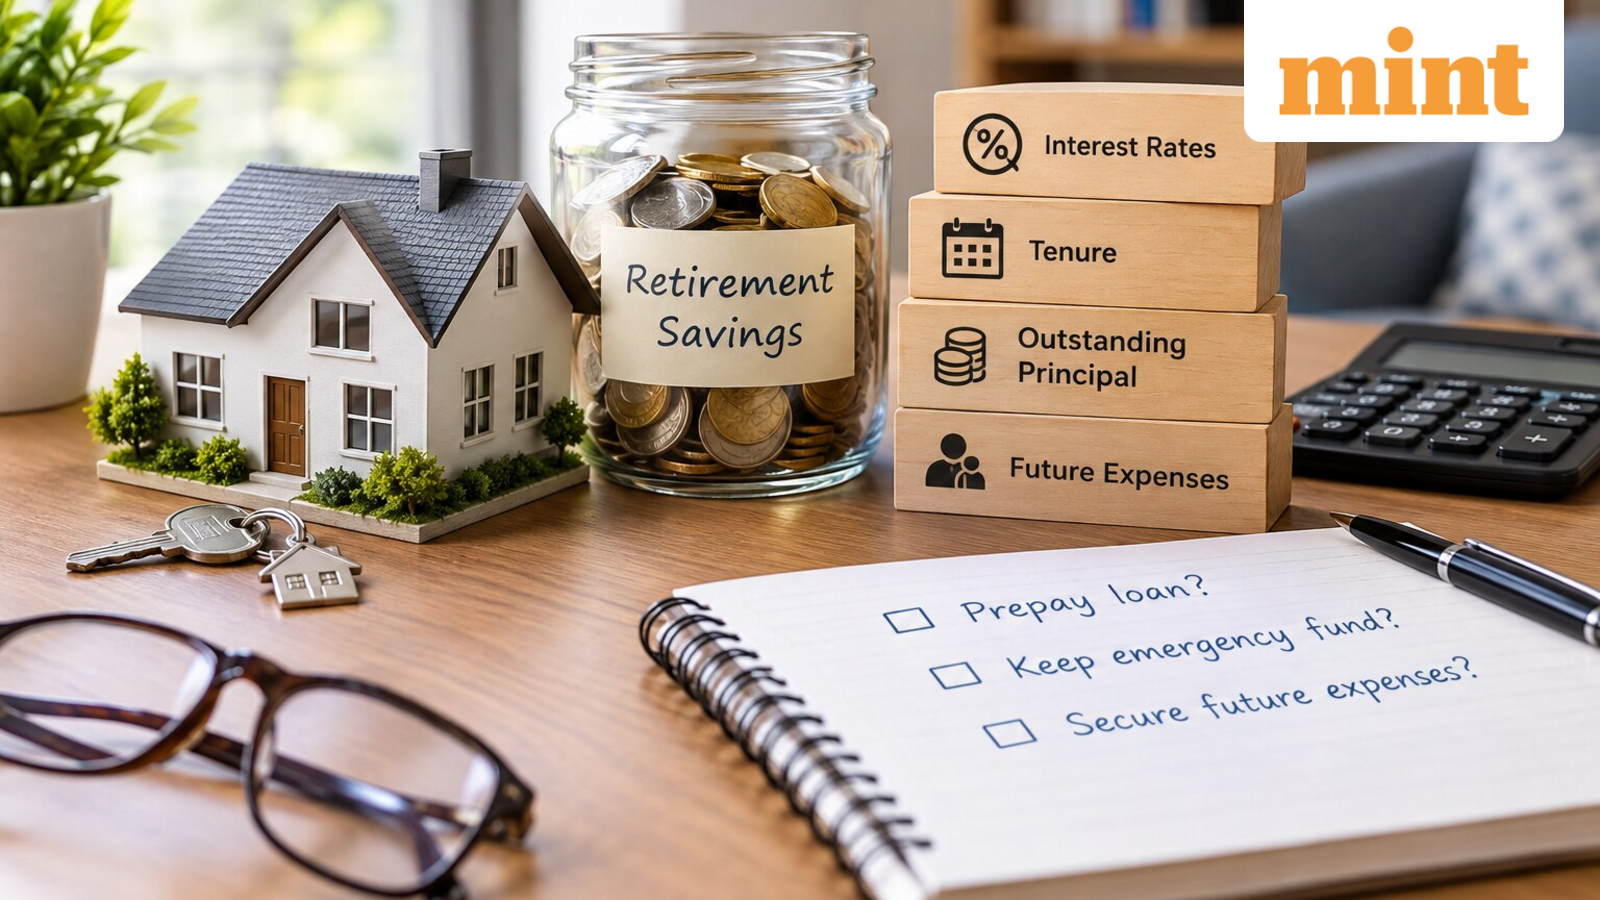
Retiring while still having a home loan can be quite challenging. It puts pressure on borrowers to make a tough choice: Should they tap into their retirement savings to pay off the debt, or keep up with the monthly payments and safeguard their savings?
There’s really no one-size-fits-all answer here. Continuously paying down a home loan can ease interest expenses and eliminate a fixed monthly payment, but draining too much of your retirement nest egg can introduce financial strain and uncertainty later on. You could find yourself facing unexpected medical costs or other crucial expenses, which, well, makes it even trickier.
So, tackling this situation effectively means avoiding the temptation to empty out your retirement savings just to close the loan. Borrowers should think carefully about their outstanding principal, the remaining loan term, the interest rate, and their cash flow needs after retiring. It’s also important to consider what they’ll need for future expenses.
Should you use retirement savings to repay the home loan?
Sarosh Amaria, MD of Tata Capital Housing Finance Limited, elaborated on this topic, emphasizing that generally, using retirement savings to pay off a home loan at age 60 isn’t advisable unless you have enough resources left to comfortably handle both the repayment and future costs. While it could relieve you from monthly payment stress and lower the total interest, you’d miss the chance to replenish your savings. This could, in turn, jeopardize your financial stability down the line. Draining your funds makes you more vulnerable to emergencies and inflation, so it’s often better to liquidate assets not tied to retirement or utilize available cash flows to systematically reduce the home loan without risking your essential retirement savings.
Kapil Makhija, COO of MinEMI, shared some insights on this too. He mentioned that at age 60, carrying a home loan means dealing with interest rates of 8 to 9 percent while your retirement savings might only yield 7 to 8 percent. Simply put, the numbers suggest paying off the loan makes sense. If it’s your primary residence, eliminating the mortgage not only secures your housing but also removes a significant payment from a fixed income. However, for an investment property where rent covers the mortgage and the property value is increasing, it may be fine to keep the loan. The most important rule? Do not deplete your entire savings for this purpose. Always maintain liquid funds for at least three to five years of expenses because at that age, banks may not lend again if an emergency arises.
What should retirees consider before prepaying?
Atul Monga, CEO and Co-Founder of BASIC Home Loan, pointed out several factors for retirees to mull over before deciding to prepay their home loan at 60. He suggested evaluating the retirement corpus alongside future cash flow needs. For loans with an interest rate around 7-9%, it’s wise to compare the loan cost against the post-tax returns on savings and investments.
Atul further emphasized that retirement savings shouldn’t be drained just to achieve debt freedom. It’s crucial to maintain an adequate emergency fund and ensure there are resources for future costs. If there’s enough left even after accounting for these essentials, making partial payments might reduce the principal and the interest burden. The decision should be guided by considerations like the loan rate, remaining tenure, outstanding amount, and the borrower’s overall financial situation.
In essence, using retirement savings to clear a home loan at age 60 could be reasonable only if there are adequate funds left to support future living expenses, healthcare, and unforeseen costs. If paying off the entire loan significantly diminishes a person’s retirement savings, it might be wiser to consider partial repayment or continue with regular payments. The goal should be to strike a balance between financial stability and economic health.
Effective financial planning is key when navigating the challenges of loan repayment, as the best approach really varies based on personal circumstances. Consulting with a professional financial advisor before making decisions is usually a smart move.
Ultimately, while being debt-free can contribute greatly to peace of mind in retirement, it shouldn’t come at the expense of long-term financial security.
Disclaimer: This article is intended for informational purposes only and does not provide financial advice. Consider your individual financial situation, loan details, and retirement needs carefully before making any prepayment decisions.