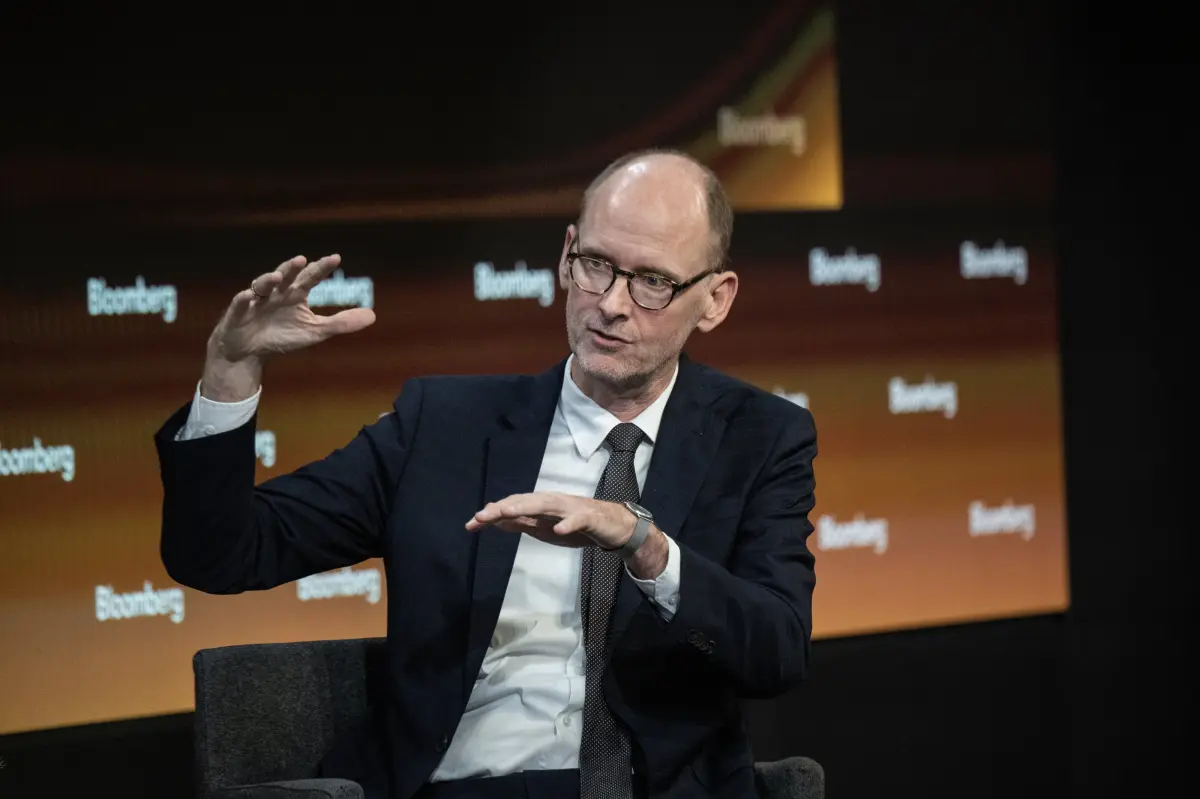
According to Torsten Sløk, chief economist at Apollo, AI agents might lead to a new type of bank run by automatically pulling consumers’ cash from low-paying checking accounts to pursue higher interest rates. This is part of a broader discussion about the potential risks of artificial intelligence.
Sløk pointed out that as personal AI tools, like Meta’s recent Muse, gain access to users’ financial data and take on more responsibilities, they could create significant challenges for banks. He suggested that if households start using AI to maximize their cash returns, banks might lose a substantial amount of the inexpensive deposits they depend on for lending, potentially threatening the entire financial system.
It’s easy to see why consumers would be tempted; for instance, a $10,000 balance at 0.1% interest generates about $10 annually, whereas at a 5% interest rate, that same amount would earn around $500. Sløk’s note mentioned several fintech and online accounts with interest rates between 3.3% and 5%, with AdelFi offering 5% and SoFi providing 4.5%.
When looking at the national averages provided by the FDIC, savings accounts yield an average of 0.4% while checking accounts only yield 0.1%. However, the prospect of increased earnings for consumers could complicate matters for banks, as AI agents could facilitate large-scale withdrawals from low-interest accounts. Banks typically thrive when customers keep their cash in these low-yield accounts since it allows them to offer lower rates to depositors while lending at higher rates.
Sløk noted that AI agents could disrupt this balance by simplifying the process for consumers to find and switch to better return options. Meta introduced Muse on September 8, highlighting its capability to perform tasks for users instead of merely responding to queries like other AI bots.
Plaid, a financial services firm, claims that Muse can access user-authorized data from over 12,000 financial institutions and apps in the U.S., covering aspects like balances, transactions, and investments. However, it remains unclear if Muse can facilitate money transfers between accounts.
Sløk suggested that the automatic movement of funds could happen “soon” but emphasized that this is not a current feature of Muse. His warning hinges on widespread adoption of these technologies.
While Sløk didn’t provide estimates on the volume or speed of potential fund transfers from traditional banks, Shama Hyder, a professor at the Link School of Business in Miami, acknowledged Sløk’s concerns but argued that the technology isn’t yet ready to trigger a mass withdrawal of deposits.
“The timing is crucial; achieving a run-like event requires millions of households to fully trust AI agents with their checking accounts, and we aren’t there yet,” Hyder remarked. “People are likely to use AI tools long before they feel comfortable letting them handle their money transfers.”
Nonetheless, she noted that banks relying heavily on low-yield deposits might face increasing challenges as AI simplifies the process of finding better rates. “A bank that thrives on customers not actively searching for better options operates on a model of friction, and AI is quite adept at eliminating that friction,” she observed.
The Post has attempted to get a response from both Meta and Plaid.